Shanghai, China | Tuesday, July 28, 2026 

The focus in building the next generation of artificial intelligence has moved from software to hardware. In just a few weeks, two major memory industry public offerings have illustrated that reality. CXMT IPO follows SK Hynix, denoting a key moment for the semiconductor industry as investors put money into companies set to benefit from the rising need for high-performance memory chips. SK Hynix’s $26.5 billion Nasdaq debut earlier this month and CXMT’s major Shanghai listing have started what analysts are calling the memory chip listing wave of 2026. Even with ongoing global disputes and technology restrictions, investors stay eager as AI changes the global semiconductor market.  

CXMT IPO Follows SK Hynix as Memory Companies Attract Record Capital 

The CXMT IPO follows SK Hynix’s Nasdaq listing, making this one of the busiest months ever for memory chip companies going public. ChangXin Memory Technologies (CXMT), China’s top DRAM maker, had a strong debut on Shanghai’s STAR Market, raising about $8.6 billion and seeing its shares jump on the first day. For a short time, this made CXMT one of China’s biggest listed tech companies, showing that investors are confident in local semiconductor manufacturing even with growing international trade restrictions.  

Earlier this month, SK Hynix completed its landmark U.S. listing valued at approximately SK Hynix $26.5 billion Nasdaq, increasing access to global investors while strengthening its position as one of the world’s dominant suppliers of advanced DRAM and High Bandwidth Memory (HBM) products for AI servers. Together, these transactions demonstrate how capital markets are rewarding companies supplying the memory required for increasingly complex AI workloads.  

Memory Chip Listing Wave 2026 Reflects AI Investment Boom 

The memory chip listing wave of 2026 continues as semiconductor companies seek more funding than ever before. AI training clusters now need much more DRAM and HBM than older computing systems. Each new generation of AI models uses more memory bandwidth, which keeps investment flowing through the supply chain. 

The memory chip listing wave of 2026 is about more than just raising money. Manufacturers need billions of dollars to grow their factories, buy advanced equipment, improve packaging, and get raw materials. Public markets offer long-term financing that private investors often cannot provide.  

Industry analysts still expect strong demand as large cloud providers invest more in AI infrastructure. Big tech companies have put tens of billions of dollars into new data centers, which is driving up memory use. This demand has reduced inventories in several categories, causing a global memory chip shortage in advanced AI-oriented products.  

AI Demand Continues to Tighten Global Supply 

The current global memory chip shortage is different from past chip shortages. Instead of being caused mainly by consumer electronics, today’s shortage comes from the rise of enterprise AI projects. 

Large language models, suggestion engines, self-driving platforms, and business AI applications all need huge amounts of memory to handle big datasets quickly. High Bandwidth Memory is especially important because it greatly boosts the performance of AI accelerators. 

Samsung Electronics, SK Hynix, and Micron still lead in high-end memory production, but CXMT has been growing its share in standard DRAM markets. Research firms say the Chinese company already makes up a larger part of global DRAM shipments and plans to keep increasing its share in the coming years.  

CXMT Chip Equipment Restrictions Remain the Company’s Biggest Challenge 

Although investor enthusiasm surrounding the IPO remains strong, CXMT chip equipment restrictions continue to represent the company’s most significant strategic obstacle. 

The United States has expanded export controls limiting Chinese companies’ access to advanced semiconductor manufacturing equipment. These restrictions affect cutting-edge lithography systems, deposition tools, etching equipment, and inspection technologies needed for leading-edge memory production. 

As a result, CXMT chip equipment restrictions may slow the company’s ability to compete with global leaders within next-generation memory, especially High Bandwidth Memory for AI accelerators.  

Chinese Equipment Makers Dependency Shapes Manufacturing Strategy 

Since CXMT cannot get many of the world’s most advanced fabrication tools, it has had to depend more on Chinese equipment makers dependency to expand production capacity. 

Local suppliers have sped up work on etching, cleaning, measurement, and deposition systems to replace imports when they can. The Chinese government has invested a lot to build a more self-sufficient semiconductor industry and encourages equipment makers and chipmakers to work together. 

Nevertheless, Chinese equipment makers’ dependency presents technical and operational problems. Many locally produced tools continue to lag the precision, throughput, and reliability offered by established international suppliers. That gap affects manufacturing efficiency, yields, and the speed at which advanced process technologies can be commercialized.  

Investors See Opportunity Despite Rising Risks 

Despite these challenges, capital markets seem ready to overlook them. 

Investors know that China’s need for semiconductors is huge. The country imports chips worth hundreds of billions of dollars each year, so making more chips locally is a top national goal. 

For portfolio managers, CXMT gives access to one of the fastest-growing parts of the semiconductor industry. At the same time, SK Hynix still benefits from high prices for AI memory products and stays a global leader in HBM technology. 

However, there are still big risks. Growing geopolitical competition, changing export controls, limits on technology licenses, and possible oversupply could all quickly change the market. After the CXMT listing, several memory stocks became more volatile as investors reconsidered future competition.  

What the Dual Listings Mean for the Semiconductor Industry 

The fact that the CXMT IPO follows SK Hynix within the same month reflects more than coincidence. Both offerings demonstrate that memory has become one of the most strategically valuable segments of the global semiconductor market. 

SK Hynix’s $26.5 billion Nasdaq listing showed that international investors want to back leading AI infrastructure companies. At the same time, CXMT’s IPO right after SK Hynix’s signals China’s strong push to build up its own semiconductor industry, even with ongoing trade restrictions. 

As AI adoption accelerates across cloud computing, healthcare, automotive technology, manufacturing, and enterprise software, the requirement for advanced memory is expected to remain strong. That outlook explains why the Memory chip listing wave 2026 continues despite geopolitical uncertainty. 

For investors, policymakers, and tech companies, these IPOs are about more than just raising money. They show that memory chips are now a key strategic asset in the AI era. Companies that can grow production and handle supply chain and export challenges will likely lead the next phase of global semiconductor competition.

Source: China memory chipmaker CXMT’s shares soar in blockbuster listing 
Frankfurt, Germany | Dateline: Tuesday, July 28, 2026 

One weekend headline quickly changed the mood after days of nervous trading across Europe. Investors who had spent most of July worried about more conflict in the Middle East instead woke up Monday to news of a pause in fighting between the United States and Iran, and they responded the way markets usually do when the worst-case scenario doesn’t materialize, they bought. The result was a broad European stocks rally Iran pause that swept from Frankfurt to Milan, with every major regional index rising and oil-sensitive sectors also gaining. 

A Relief Rally Rooted in De-Escalation 

Traders do not need a full resolution to feel more confident. What matters most is that tensions do not get worse, and that is what happened. The weekend pause in US-Iran hostilities did not solve the conflict, but it removed the immediate risk of a wider war that could disrupt the Strait of Hormuz and global energy supplies. Oil prices fell as a result, which was enough to improve the trader’s sentiment for the new trading week. 

The DAX’s 1.28 percent gain in Frankfurt was the clearest sign of this change. Germany’s export-focused index often reacts strongly to political risks because of its ties to global manufacturing and energy costs. On Monday, it saw its biggest single day jump in weeks. Industrial and chemical companies, which are especially sensitive to energy prices, led the way investors saw less risk of a long-lasting oil price shock. 

German DAX Frankfurt Monday: Reading the Numbers 

The German DAX Frankfurt Monday session opened higher on Monday and kept its gains until the market closed. Strategists saw this as a sign of real confidence, not just a quick reaction. Unlike some of the sharp swings seen earlier this year, Monday’s rise was steady and did not fade. This kind of rally often attracts more institutional investors, not just fast-moving traders reacting to news. 

It is important to put this number in context. A gain of more than one percent on a major European index does not happen every day. Usually, it takes strong earnings or a big surprise in the economy. On Monday, there was no major earnings news. The move was driven almost entirely by improved sentiment, showing how much geopolitical risk had been holding back the DAX in recent sessions. 

France and Italy Join the Advance 

Frankfurt was not the only market moving higher. The gains in the CAC, FTSE MIB on Monday showed that the rally was continental in scope, not a German-specific phenomenon tied to any single domestic catalyst. In Paris, the French CAC 40 up 0.70 percent, with the biggest gains in luxury goods, industrials, and financials. These sectors had struggled during the worst of the Iran-related uncertainty and were ready to rebound once the pressure eased. 

Milan saw a similar trend. The Italian FTSE MIB rose by a modest but still significant 0.54 percent. While this was less than the gains in Frankfurt and Paris, it was still a clear positive. Italian banks, which make up a large part of the FTSE MIB, also benefited from the improved risk appetite, even though there was no specific local news driving the move. 

FTSE 100 Advances 0.66 Percent as London Joins In 

Across the Channel, the FTSE 100 advances 0.66 percent, placing London’s benchmark comfortably in the middle of the pack, ahead of Milan but behind both Frankfurt and Paris. The FTSE 100’s heavy weighting toward energy majors typically makes it a laggard during oil-price relief rallies, since falling crude prices can pressure the earnings outlook for companies like Shell and BP even as the wider market cheers reduced geopolitical risk. That the index still managed a solid advance speaks to how widespread Monday’s buying was across sectors apart from energy. 

Why the Rally Tracked US Markets So Closely 

This wasn’t just a European story. The same positive sentiment was also lifting Wall Street, with US futures rising before European markets opened. When European and American markets move together because of a geopolitical event, it shows the issue is global, not just regional. Energy traders, currency desks, and equity investors were all focused on the same key question: whether the Strait of Hormuz, which handles one-fifth of global oil flows, would stay open. 

Financial media used similar headlines on Monday, such as “European stocks rally DAX 1.28 percent,” to show both the size and cause of the move. News services and data providers reported almost the same numbers for the DAX, CAC, FTSE, and FTSE MIB. This consistency showed that the rally was driven by one main factor, not a mix of different local events. 

What Comes Next for European Equities 

The big question now is whether these gains will last. Relief rallies that happen because bad news is avoided, rather than because of good news, are often fragile. If the pause in fighting continues, strategists think the gains will likely hold steady instead of rising much more, and attention will shift back to earnings and central bank decisions. If fighting starts again, Monday’s gains could disappear just as quickly. News coverage calling it a “CAC FTSE MIB advance Iran pause” captured this uncertainty well. The rally is real, but it depends on a geopolitical situation that could change at any time. 

For now, portfolio managers in Frankfurt, Paris, London, and Milan see Monday’s session as a real, broad-based rally, not just a random jump. Trading volumes were strong, gains were spread throughout different sectors, and the rally lasted until the market closed. Whether this is a lasting turning point or just a short break in a period of volatility will depend on what happens next in the Middle East, which is beyond the control of investors. What is clear is that, at least for one day, European investors decided to be optimistic.

Source: European stocks rally on easing Iran tensions, oil decline 

New York, New York | July 28, 2026 

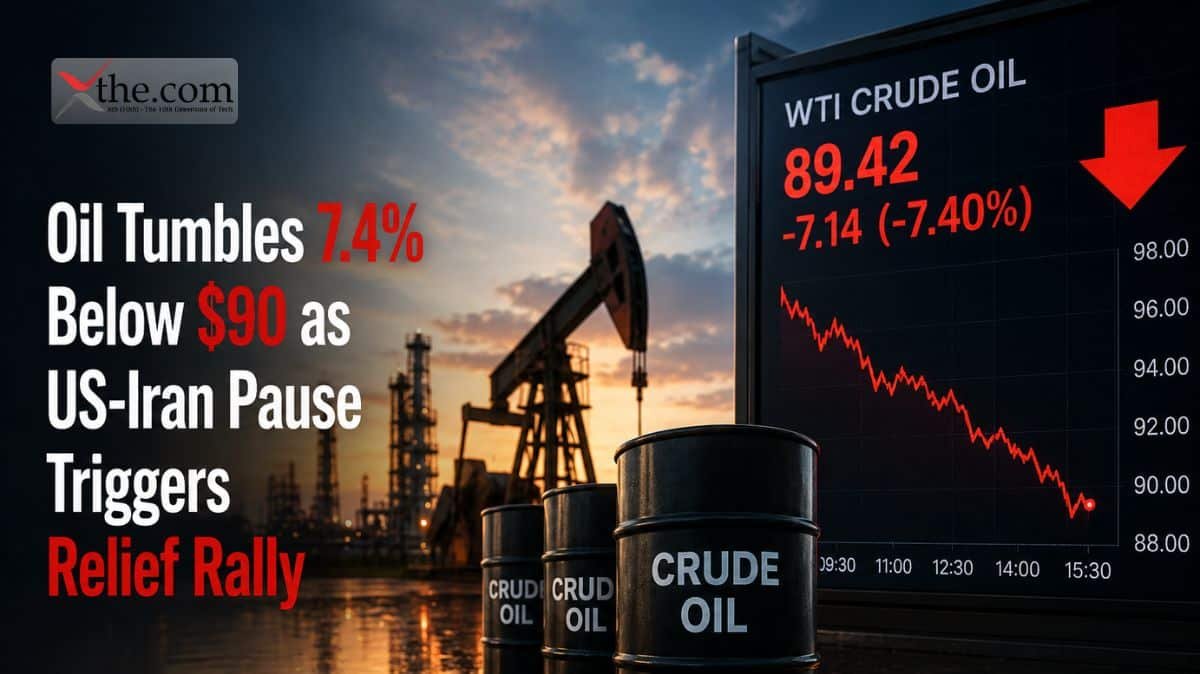
Oil traders spent nearly two weeks pricing in the possibility of a wider Middle East conflict. Within hours, sentiment changed dramatically. Oil tumbles below $90 became the defining market headline after the United States and Iran refrained from launching additional military strikes, causing a broad-based US-Iran strike pause rally across global financial markets. At the same time, Brent crude falls 7.4 percent, while investors shifted capital toward equities, government bonds, and precious metals since geopolitical fears eased. 

This sudden turnaround showed how fast commodity markets move when geopolitical risks fade. Traders expecting long-term supply problems instead saw one of the biggest one-day drops in crude prices this year. 

Oil drops below $90 because tensions ease. 

The oil market responded right away once it was clear that the US paused its military campaign against Iran and Tehran did not launch new attacks. 

This outcome was what investors wanted—a lower risk of immediate supply problems. 

The market witnessed “Oil tumbles 7.4 percent below $90” as Brent crude dropped as much as 7.4 percent below $90 before recovering about half of those losses later in the day. Even after bouncing back, prices stayed well below the highs reached during the worst of the tensions. 

This drop wasn’t only about profit-taking. It showed that a big geopolitical risk premium, added to oil prices in recent weeks, had been removed. 

Traders see the Strait of Hormuz as a key route for global energy. Any threat to shipping there quickly raises worries about oil supply, transport costs, and refinery operations. When those worries eased, many speculative bets were quickly reversed. 

Understanding the US-Iran strikes pause rally. 

The US-Iran strikes pause rally extended well beyond the energy market. 

Stock markets rose as investors became more willing to take risks, while government bonds attracted those looking for balance during ongoing uncertainty. Gold also rose, showing that people still wanted safe-haven assets even as oil prices fell. 

The combination created an unusual but understandable market response in which bonds gold gain relief rally became one of the defining investment themes of the day. 

Government bond yields fell as more investors bought Treasuries, and gold stayed popular even as military tensions eased. Analysts pointed out that while the risk of immediate escalation dropped, ongoing uncertainty kept demand for safe assets high. 

Meanwhile, the dollar weakened Monday against other major currencies as investors moved away from this usual haven. The weaker dollar also helped steady commodity markets after oil’s sharp drop. 

Brent remains significantly higher despite the correction. 

While the headlines featured the sharp drop that day, the bigger picture is different. 

Even after Brent crude falls 7.4 percent, the international benchmark remains substantially above where it began the year. In fact, Brent up 50 percent year-to-date, illustrating the remarkable resilience of energy prices despite intermittent periods of volatility. 

Ongoing instability in the Middle East, shipping problems, production worries, and higher geopolitical risks have all pushed crude prices up during 2026. 

So, this recent drop is just a pullback in a very strong year for oil, not a sign that the basics of the market have changed. 

Energy analysts keep warning that oil supply is still at risk from new geopolitical shocks. Any trouble with major exporters or shipping routes could quickly bring back the risk premium that faded on Monday. 

Relief spreads over financial markets. 

As military tensions eased, different types of assets responded in sync. 

Global stock markets reacted favorably to lower energy costs, since cheaper oil usually means less inflation for transport companies, manufacturers, airlines, and consumers. Investors saw the pause in military action as removing a major risk for the world economy. 

The fact that both bonds and gold rose at the same time showed that investors were still careful, even as the mood improved. 

This mix of hope and prudence matches today’s geopolitical reality. People in the market know that ceasefires or pauses do not solve deeper regional issues. 

The “US Iran pause triggers relief rally” therefore represents an immediate reaction to reduced escalation risks rather than a definitive signal that geopolitical uncertainty has disappeared. 

Why oil prices remain highly sensitive 

Oil markets are especially sensitive to political events because most production happens in just a few areas. 

The Middle East still supplies a large part of the world’s crude oil, so traders, refiners, shipping companies, and decision-makers watch every military move closely. 

Even small changes in how people see supply risks can cause big swings in prices. 

For example, worries about tanker traffic in key waterways can move prices even before anything actually happens. In the same way, news about diplomatic restraint often leads traders to sell quickly and remove extra risk premiums from futures contracts. 

Monday’s trading showed just how quickly these expectations can change. 

Investors remain focused on the next move. 

Even with the relief rally, professional investors are still careful. 

Energy markets are still watching official statements from the US and Iran, naval movements in the Gulf, and diplomatic talks with regional allies. 

Should tensions re-emerge, oil prices could quickly bounce back from Monday’s drop. dually reduce volatility and encourage further normalization across commodities and currency markets. 

For central banks, lower oil prices might help a bit by easing inflation, especially when policymakers try to manage growth and stable prices. 

Market outlook 

This sharp drop is a sign that international affairs are still a major force in commodity markets. Oil falling below $90 got investors’ attention because it showed a sudden change in expectations, not in global demand. Even though Brent crude’s 7.4 percent fall was one of the biggest daily moves this year, the fact that it’s still up 50 percent shows how strong energy prices are despite ongoing supply worries. If diplomacy holds, the rally could continue, but if tensions increase again, the risk premium could return just as fast, keeping oil one of the most closely watched and volatile assets.

Source: Oil prices settle at lowest in over a week, as US pauses attacks on Iran 

New York, New York — Tuesday, July 28, 2026 

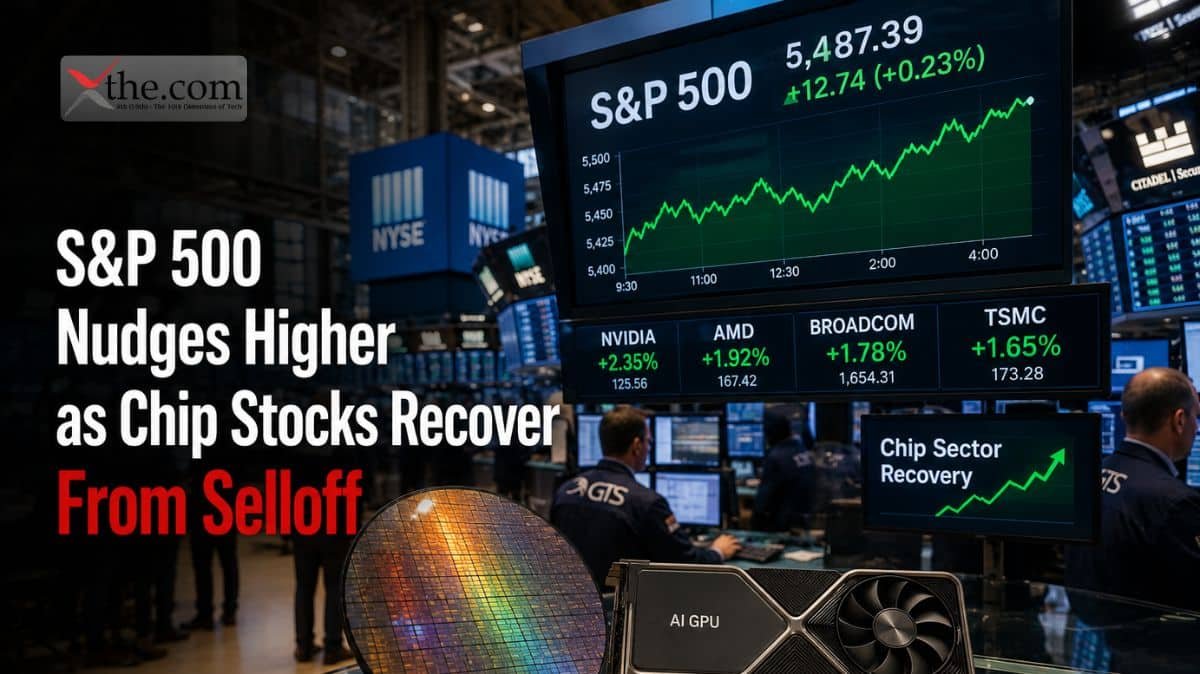
A two-cent gain rarely makes headlines. On Monday, it did. The S&P 500 nudges higher Monday, closing up just 0.02%, and that razor-thin advance was enough to end a three-session skid that had investors bracing for a rougher week. The real story, though, sat one layer down: chip stocks recover selloff losses that began building last Friday, clawing back ground even as the sector as a whole stayed deep in the red. Blue-chip names carried the tape higher, with the Dow 260 points higher, while the Nasdaq barely moved, down a fraction of a percent as traders sorted winners from losers inside a semiconductor sector that has whipsawed for two straight weeks. 

This session showed what Wall Street strategists have been saying for months: the market is no longer acting in unison. Software and large tech companies are driving gains, while chipmakers are dealing with the ups and downs caused by China’s fast-growing semiconductor industry. 

A Fragile Recovery in Chip Stocks 

It was more of a bounce than a full rebound. Semiconductor stocks started Monday strong after ChangXin Memory Technologies, a Chinese memory-chip company, had a major IPO on the Shanghai Stock Exchange. Traders saw this as a sign that global chip demand is still solid, and futures for chip-heavy indexes rose before the market opened. 

That optimism diminished rapidly. Reports came out that Chinese manufacturers are working on their own deep ultraviolet lithography machines, the specialized equipment used to make silicon chips, a field long led by Dutch supplier ASML. For an industry already worried about the pace of AI spending, this news was a shock. It turned China from a customer into a competitor in just a few hours, and the sector’s early gains disappeared by midday. 

By the closing bell, the damage was contained but visible. The SMH ETF, 2 percent lower, told the headline story: the VanEck Semiconductor ETF, which follows the industry’s top companies, continued a decline that started on Friday. This was the fund’s fourth significant drop in a month, even though the wider Philadelphia Semiconductor Index is still up a lot for the year. 

Where the Pressure Landed Hardest 

The moves in individual stocks showed how uneven Monday’s trading was. AMD Teradyne decline 4-5 percent, capturing the two biggest single-day laggards among chip stocks, with Advanced Micro Devices dropping about 5% and testing equipment maker Teradyne falling nearly 4%. Both companies are heavily involved in AI infrastructure spending, making them stand-ins for how investors feel about the sector’s main growth story and its biggest risk. 

Memory-chip giant Micron Technology also slid; early commentary on the move cited Micron sheds 3 percent, though Monday’s closing tape put the decline closer to 2%, as investors considered the company’s exposure to Chinese competition against strong demand for high-bandwidth memory in data centers. Dutch equipment maker ASML, whose lithography machines were at the center of Monday’s concerns, dropped nearly 6% in US trading, showing how much the DUV news affected the supply chain. 

Blue Chips Do the Heavy Lifting 

While chip stocks struggled, the Dow Jones Industrial Average had a steady session. Industrial and financial stocks made up for the weakness in semiconductors, and the index finished at a new high for the week. Traders also noted that falling oil prices helped: crude dropped again on Monday, lowering costs for transportation and manufacturing companies and allowing the Dow to rise even as growth stocks slowed. 

This split—industrials rising, chips falling, and software staying steady—is becoming a common pattern this earnings season. Portfolio managers see it not as a rotation, but as a review. Thomas Martin, a senior portfolio manager focused on technology, told financial media that uncertainty about Chinese competitors is now a lasting concern, not just a one-day worry, because product markets are tight and Chinese suppliers are advancing quickly. 

A Market Increasingly Split in Two 

In recent weeks, the link between chip-focused and software-focused technology funds has weakened, dropping from a long-term average of about 0.75 to nearly zero. In simple terms, owning ‘tech’ stocks no longer means making just one bet. Cybersecurity and data-protection companies have quietly done well, while memory and equipment makers have taken up most of the sector’s hits. 

For headline writers, S&P 500 nudges higher chips recover’ summed up Monday in five words: modest gains for the overall market, while the chip industry is still trying to stabilize. For traders watching closely, ‘Dow 260 points higher Monday session’ was the key number, showing that chip sector troubles did not stop the wider rally. 

What Investors Should Watch This Week 

Monday’s session was just a preview. The Federal Reserve’s next rate decision arrives midweek, and several Magnificent Seven earnings reports—led by Microsoft and Meta, with Apple close behind—will test if AI-related spending can support current stock prices. If there are signs that big tech companies are cutting back on infrastructure budgets, it could hurt chip stocks again just as they seemed to be recovering. 

In the long run, the competitive threat from Chinese semiconductor makers is here to stay. Domestic lithography development, once thought to be years away, is now moving faster, forcing US chipmakers and investors to rethink risks as they happen. Whether Monday’s partial recovery lasts or is just a short break before another drop will depend more on what companies say about spending, competition, and demand in the coming days than on Monday’s numbers. For now, the market is showing strong confidence in the US economy but is watching anything related to advanced chip manufacturing much more closely.

Source: Dow closes more than 250 points higher, aided by cooling oil prices 

Hawthorne, California | Tuesday, July 28, 2026 

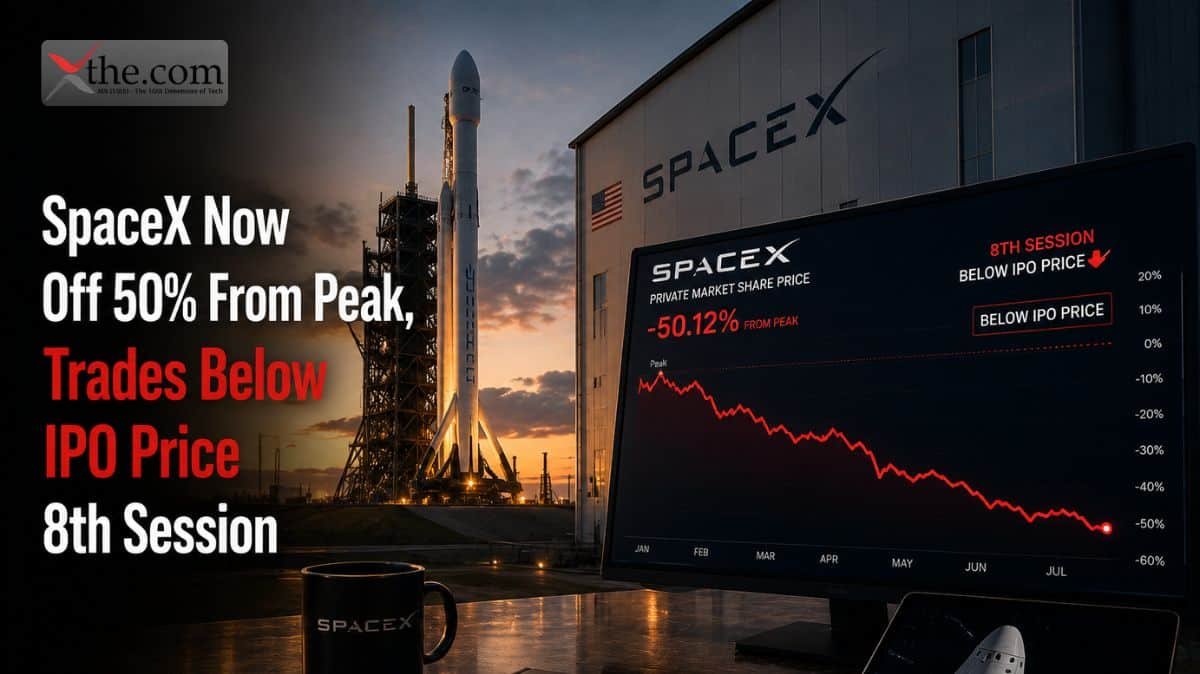
More than half of a company’s market value can vanish in just a few weeks—even after one of the most anticipated public offerings in years. That is the reality confronting investors as SpaceX, off 50 percent from its peak, becomes one of the most discussed market stories following the aerospace company’s blockbuster debut. With SpaceX below IPO price eight sessions and heading toward SPCX 10th negative session, investors are questioning whether the selloff is due to weakening fundamentals or just the typical volatility that follows big IPOs. 

Shares traded near SpaceX trading $109.40 Monday, representing a decline of more than 51% from the SpaceX high of $225.64 post-IPO reached soon after the June 12 listing. This ongoing weakness has drawn more attention from institutional investors, analysts, and retail traders. 

SpaceX Off 50 Percent From Peak Prompts Questions About Post-IPO Valuation 

The phrase ‘SpaceX off 50 percent from peak’ is more than merely a headline. It shows how quickly investor outlook has changed in only a few weeks. 

After its June IPO, enthusiasm surrounding SpaceX drove the stock to an all-time high of SpaceX high $225.64 post-IPO. Investors were betting that the company’s dominance in commercial space launches, satellite communications, and government contracts would support a high valuation. 

But that optimism diminished rapidly. 

By Monday morning, the stock was SpaceX trading $109.40 Monday, leaving shares more than 50% below their record level. The decline also means “SpaceX off 50 percent from all-time high” has become an accurate description of the company’s market performance since its debut. 

Big price swings like this are common after major IPOs. New public companies often see a lot of volatility as early investors take profits; institutions rebalance their portfolios, and the market finds a more stable value. 

SpaceX Below IPO Price Eight Sessions Signals Persistent Selling Pressure 

A worrying trend is that SpaceX below its IPO price for eight sessions in a row, making this more than just a brief drop. 

SpaceX started trading publicly at $135 per share. Staying below that price for eight straight sessions shows there is ongoing selling pressure, not just random market swings. 

This situation also fits the search phrase ‘SpaceX below IPO price eighth session,’ showing how long the stock has stayed under its original price. 

Investors pay close attention to the IPO price because it is an important psychological support level. Staying below that mark for several days can hurt market trust, especially for those who bought shares at the IPO. 

SPCX 10th Negative Session Highlights Weak Market Momentum 

The stock’s recent trading shows its momentum is getting weaker. 

Monday’s decline positioned the company for SPCX’s 10th negative session since becoming publicly traded. At the same time, SpaceX’s 10 of 12 sessions negative demonstrates that sellers have controlled the market for the overwhelming majority of trading days since the IPO. 

Instead of just a few corrections, a string of declines often points to bigger changes in how investors are positioning themselves. 

Portfolio managers often cut back on new stocks during unstable times, especially when prices are still high compared to older aerospace and defense companies. 

Even though SpaceX still has strong advantages in launches and satellite infrastructure, the stock market often treats long-term business strength differently from short-term stock performance. 

Why Investors Are Reassessing SpaceX 

Several things seem to be driving the recent drop. 

First, valuation is a big concern. SpaceX started with very high expectations, so there is little room for disappointment, even if the company is performing well. 

Second, early investors often start selling as IPO lockup periods end, which adds more selling pressure. 

Third, the overall market has become less friendly to growth-focused tech and aerospace stocks. Higher interest rates, cautious moves by big investors, and more market swings have made people less willing to pay high prices for growth companies. 

Finally, expectations for future earnings are still high. Investors are watching to see if growth from Starlink, launch contracts, and defense deals can support the earlier high valuations. 

Does the Decline Reflect Business Fundamentals? 

It’s important to note that the recent stock drop does not mean the company’s business is getting worse. 

SpaceX is still one of the top commercial space companies, with revenue coming from launches, satellite broadband, government contracts, and deep-space projects. 

The company is still signing launch deals and growing Starlink’s subscriber base worldwide. Not much has changed in its operations since the IPO. 

Instead, most of the recent drop seems to be about adjusting the stock’s valuation, not about the company’s fundamentals getting weaker. 

History shows that many big tech IPOs have had large drops in their first months before stabilizing as their earnings became clearer. 

It’s still unclear if SpaceX follows the same path. 

Institutional Investors Are Watching Key Support Levels 

Professional investors usually care less about daily price changes and more about whether key support levels hold over several weeks. 

With SpaceX trading at $109.40 on Monday, people are watching to see if buyers start picking up shares at these prices or if more selling will push the stock down further. 

Recent trading volumes suggest that big institutions are active, showing that portfolios are being adjusted, not just retail investors speculating. 

Analysts will probably pay close attention to the next quarterly results, company guidance, and what management says about launch demand, Starlink’s growth, and long-term spending plans. 

These factors will help decide if the current selloff is just a short-term correction or the start of a longer reset in the stock’s value. 

Market Mood Could Shift Quickly 

Although current headlines emphasize SpaceX off 50 percent from its peak, opinions about high-profile growth companies can change quickly. 

Good earnings, big government contracts, successful launches, or faster Starlink subscriber growth could help restore investor confidence. 

On the other hand, if the stock stays weak below the IPO price, more investors might sell to avoid the risks of a new and volatile stock. 

Right now, the numbers are difficult to overlook. SpaceX has been below its IPO price for eight sessions, is facing its tenth negative session, traded at $109.40 on Monday, and has had 10 out of 12 sessions in the red. Together, these stats show one of the sharpest post-IPO reversals in recent aerospace history. 

The next few weeks could be vital. Investors will look past daily price changes to see if the company’s strong operations can ease worries about its valuation. If management keeps delivering its growth plans and shows real financial progress, today’s drop might be an example of post-IPO volatility, not a final judgment on one of the world’s leading aerospace companies.

Source: SpaceX stock plunge sends a big reminder to those who want to get in on or near IPO day 

London, United Kingdom |July 26, 2026 

Investec, a £5.6 billion bank that many American investors have never heard of, just earned a seat at the table of Britain’s most-watched equity benchmark. That is the practical reality behind Investec joins FTSE 100, a development that has quietly changed how index funds, pension managers, and international investors view UK banks. After years of moving between the FTSE 250 and other ranks, this promotion is significant. It shows that the market now sees Investec, known for private banking in Johannesburg and wealth management in London, as worthy of blue-chip status on one of the world’s largest stock exchanges. 

The timing matters. UK bank index inclusion events tend to arrive alongside a wave of institutional re-rating, and Investec’s case is no exception. Fifteen sell-side analysts now cover the stock with fresh eyes, and their collective read is notable less for eagerness than for steadiness. 

UK Bank Index Inclusion Signals a Turning Point 

Index promotions follow a set process: when a company’s market value reaches a certain level, FTSE Russell adds it to the index at the next review. However, the effects go beyond this. Funds that track the FTSE 100 must buy the stock, which can push up its price even if earnings do not change. For Investec, which is listed in both London and Johannesburg, joining the index means more investors beyond those focused on South Africa will now own its shares. 

This is where UK bank index inclusion dynamics diverge from a typical earnings story. A company does not need a big earnings jump to see its value rise; it just needs more visibility with investors. Before this promotion, Investec’s focus on corporate banking, private banking, and wealth management in the UK and Southern Africa meant it was less known to big investors. Now, that is changing. 

Investec Joins FTSE 100: What the Numbers Say 

The fifteen analysts now following Investec expect steady, disciplined growth. It is not dramatic, but it is the kind of progress that institutional investors usually value over time. 

Analyst Revenue Forecast of £10.1 Billion Points to Growth. 

The analyst revenue forecast of £10.1 billion for 2026 represents a 3.8% increase year over year. That is not a dramatic acceleration, but it is a meaningful one for a bank whose core business depends on steady net interest income and fee generation rather than volatile trading revenue. A 3.8% top-line expansion, compounded across a loan book that has already shown double-digit growth in recent periods, suggests management is converting balance sheet expansion into revenue without taking on outsized risk. 

Investec EPS Steady Outlook: UK£1.27 EPS Projection Holds Firm 

Perhaps the most telling detail in the consensus is what has not moved. The UK£1.27 EPS projection has remained essentially unchanged even as the stock’s index status shifted. That stability matters. When a stock joins a major index, sell-side analysts sometimes revise earnings estimates upward to justify a re-rating — a pattern institutional investors have learned to distrust. Here, the Investec EPS steady outlook implies analysts are pricing the FTSE 100 promotion as a liquidity and visibility event, not an earnings catalyst. That distinction should reassure investors who worry about chasing a stock on sentiment alone. 

Investec Price Target £33.85: Analysts Weigh In 

Price targets tell a similar story of measured confidence. The Investec price target of £33.85 sits well above where the stock has recently traded, but the dispersion around that figure is wide: estimates range from £21.20 to £50.70. That £29.50 spread across fifteen analysts is not unusual for a bank with dual-market exposure and currency translation risk between sterling and the South African rand, but it does underline genuine disagreement about how much credit the market should give Investec for its FTSE 100 status versus its underlying loan growth. 

Some of the Investec price target £33.85 analysts have cited reflect a base case built on continued net interest margin resilience. At the same time, the more bullish outliers assume Investec’s wealth management arm captures a larger share of high-net-worth clients now that its profile has risen. The bears, by contrast, point to South African macroeconomic exposure as a persistent drag on multiple expansion, regardless of index status. 

Investec Joins FTSE 100 Steady EPS Outlook: What It Means for Passive Fund Flows 

For US-based investors who rarely trade London-listed banks directly, the more relevant question is structural: what does Investec joins FTSE 100 steady EPS outlook mean for capital flows into the wider UK financial sector? The answer lies in how passive capital moves. FTSE 100 tracker funds, UK-focused ETFs, and global bank sector funds that benchmark against the index are now structurally required to hold Investec shares in proportion to its market weighting. That is new, permanent demand that did not exist a year ago. 

This is important for more than just Investec. When a specialist bank becomes a blue-chip, it shows that UK financial services3 still have areas of real growth, even though US mega-banks usually get more attention. American fund managers looking for global banking opportunities are now more likely to notice mid-sized banks like Investec that show steady earnings, growing revenue, and more liquidity from index inclusion. 

Risk and Opportunity: Reading Past the Headline 

The opportunity is clear. Steady earnings, rising revenue, and new demand from passive funds support the case for Investec’s value to keep rising, especially if its wealth management arm keeps attracting wealthy clients in London and Sandton. The risk is also clear: the wide range in price targets shows real uncertainty about currency risks and South Africa’s economy, as well as whether the extra buying from index funds will last. 

Investors considering UK banks should see the FTSE 100 promotion as just one factor, not the whole story. Being added to the index changes the ownership mix, but it does not automatically make the business more valuable. 

Glancing Forward 

Investec’s move up comes at a time when global investors are looking for banks beyond the big US names that have led for years. Whether the stock stays near the lower end of its price range or rises above, expectations will depend more on management’s ability to keep turning loan growth into dependable earnings than on its new index status. For now, Investec has earned its spot in the FTSE 100 by being consistent, and in banking, consistency is often a good thing.

Source: Investec FTSE 100, UK bank index inclusion, Investec EPS outlook, UK banking stocks, FTSE 100 index constituents  

Milwaukee, Wisconsin | July 26, 2026 

Stocks trading under a dollar usually don’t get much attention from Wall Street. But on Friday, LiveWire Group stood out. Shares of the Milwaukee-based electric motorcycle maker jumped sharply, and by the end of the day, ‘LiveWire Group soars 86 percent’ was the most-searched phrase among small-cap traders. After spending much of July near its lowest point in a year, this move was more than simply a typical rally. 

The catalyst remained straightforward on paper and dramatic in practice: a second-quarter earnings report that beat expectations on nearly every operational metric that matters to growth investors, even as the bottom line stayed in the red. That combination — real top-line momentum paired with a stock priced for pessimism — is exactly the kind of setup that produces an electric motorcycle stock surge of this magnitude. 

What Sent LiveWire Group Shares Into Overdrive 

LiveWire, majority-owned by Harley-Davidson and headquartered in Milwaukee, Wisconsin, reported second-quarter revenue of $9.1 million, a 55% jump from the same period a year earlier. Net losses remained substantial, with the company posting a loss of $0.09 per share, roughly flat against the prior year. On its own, a company still losing money rarely triggers this kind of reaction. The details underneath the headline number did. 

A Revenue Beat With Teeth 

Electric motorcycle unit sales rose 386% compared to last year, a number that caught traders’ attention. Growth like this is unusual for established products and suggests the company is reaching a turning point. LiveWire also reported it now has 76% of the U.S. market share in the 50-plus kilowatt on-road electric motorcycle segment, which is a small but important sign for a company often seen as just a Harley-Davidson offshoot. 

Unit Sales Tell the Real Story 

During the quarter, LiveWire started producing its new S4 Honcho platform, which targets a lower price point in the on-road electric motorcycle market. The company also completed its purchase of Dust Motorcycles, moving into electric off-road bikes for the first time. These steps show LiveWire is expanding its possible customer base instead of just trying to hold onto its current market, and investors reacted favorably. 

Why the LWLW Earnings Reaction Hit This Hard 

Markets rarely move 80-plus percent on operational improvement alone. The LWLW earnings reaction was amplified by organizational factors specific to LiveWire’s stock, not just the numbers in the press release. 

Low Float, High Short Interest 

With a market capitalization that had shrunk to roughly $185 million before the report, LiveWire was thinly traded and, by several accounts, heavily shorted. When a stock with a small float and a large short position delivers a genuine surprise, the reaction is rarely linear. Short sellers rushing to cover positions can turn a solid quarter into a violent squeeze, which is precisely the mechanism analysts pointed to as shares spiked intraday to roughly $2.09 before settling into the $1.40 range by the close — still a gain that qualifies as one of the more extreme single-session moves among small-cap EV earnings surprise stories this year. LiveWire also registered as a LiveWire stock premarket gainer well before the opening bell, as early trading absorbed the scale of the unit-sales beat. 

Managing cash flow was also important. Free cash flow usage improved by 19% so far this year, showing that management is reducing spending even while investing in two new product lines. For a company still relying on financial help from Harley-Davidson, this progress gave buyers enough confidence to stay interested after the initial jump. 

What This Means for the Electric Two-Wheeler Market 

Electric two-wheelers have spent the better part of two years eclipsed by Tesla-dominated EV headlines, with most investor attention flowing toward four-wheeled passenger vehicles and away from niche categories like motorcycles. LiveWire’s report is an indication that the category has not been standing still. This electric motorcycle firm’s earningsresult arrives at a moment when riders are showing renewed appetite for electric choices that don’t ask them to compromise on performance, and when a legacy manufacturer’s backing is starting to look like an advantage rather than a liability. 

Expanding into off-road electric motorcycles by acquiring Dust Motorcycles is also a key tactical move. Off-road riding has usually favored gas-powered bikes because battery range and charging options have not kept up with off-road needs. Having Harley-Davidson’s manufacturing and dealer network behind LiveWire could help change this, even if only a little at first. 

Risks Beneath the Rally 

These positive developments do not remove the challenges LiveWire still faces. The company expects a full-year operating loss of $70 million to $80 million, which is much larger than its current quarterly revenue. Retail sales and market share in Europe both fell during the quarter, showing that most of the company’s progress is in the United States. Also, one big trading day does not guarantee a lasting turnaround, since rallies driven by short sellers often fade once the pressure eases. 

Investors chasing the move should also weigh how much of Friday’s “Electric motorcycle stock surge Friday” action reflected durable business improvement versus mechanical repositioning by traders who had bet against the stock. Both were almost certainly present. Separating the two will take another quarter or two of the data, not one earnings report. 

What Comes Next 

LiveWire’s next scheduled report, covering theLiveWire’s next report, which will cover the third quarter, will show whether Friday’s jump was a real turning point or just a temporary spike. If unit sales keep growing and the S4 Honcho platform and Dust Motorcycles integration meet expectations, the ‘LiveWire Group soars 86 percent earnings headline could be the start of a bigger trend. For the electric two-wheeler market, this could be important far beyond Milwaukee.

Source: LiveWire Group (LVWR) Stock Faces Ongoing $18 Million Quarterly Loss Reinforcing Bearish Narratives 

New York, New York | July 27, 2026 

A sharp divide has emerged in the technology sector. While some of Wall Street’s biggest AI winners continue to report strong revenue growth, investors are paying less attention to earnings headlines and more attention to cash flow. That shift has fueled a significant rotation across the market, with the Magnificent Seven ETF falls 5 percent, standing in sharp contrast to semiconductor funds that finished the week in positive territory. The growing gap reflects mounting concerns that the race to dominate artificial intelligence may be becoming increasingly expensive. 

The MAGS weekly decline has become one of the clearest indicators of changing investor outlook. At the same time, semiconductor ETFs’ higher week performance implies that investors are becoming more selective, favoring companies that directly benefit from AI infrastructure demand while questioning the spending strategies of large technology platforms. 

Magnificent Seven ETF falls 5 percent, highlighting market rotation. 

The Magnificent Seven ETF falls 5 percent over the week, showing how quickly investor priorities might change. The Roundhill Magnificent Seven ETF (MAGS), which tracks Apple, Microsoft, Alphabet, Amazon, Meta, Nvidia, and Tesla, lost over five percent even though many of these companies reported solid results. 

The Roundhill MAGS ETF performance reflected a wider review of valuation rather than deteriorating business fundamentals. Investors progressively questioned whether the enormous capital expenditures required to build AI infrastructure will generate acceptable returns within a reasonable timeframe. 

This week’s market moves show that strong revenue growth is no longer enough for investors. They now want proof that AI investments will lead to lasting profits and steady cash flow. 

Why the MAGS Weekly Decline Accelerated 

The MAGS weekly decline gathered momentum after several earnings reports showed companies planning to spend heavily on expanding artificial intelligence. 

Investors focused on Alphabet this week. Even though its earnings beat expectations, the company confirmed it would spend billions more on AI infrastructure and data centers. This spending plan took attention away from its otherwise healthy financial results. 

One market strategist summarized the prevailing mood by stating, “Investors are really scared that these companies are spending all their cash flow on all this AI and data centers and so forth.” 

This comment gets to the main issue. The question isn’t if AI will change industries, but whether companies can make enough returns before their heavy spending starts to hurt earnings and cash flow. 

The growing concern surrounding investors scared AI spending cash flow has become one of the dominant themes influencing technology valuations this earnings season. 

Semiconductor ETFs Higher Week Shows Investors Prefer AI Suppliers 

While large technology stocks struggled, semiconductor ETFs’ higher-week performance highlighted a very different story. 

Chip manufacturers occupy a distinct position within the AI ecosystem. Regardless of which software platform ultimately dominates artificial intelligence, the requirement for advanced processors, memory chips, networking equipment, and specialized AI accelerators continues to expand. 

This trend helped semiconductor-focused ETFs outperform the wider technology market. 

The phrase “Semiconductor ETFs end higher AI fear” sums up this split well. Instead of leaving AI investments, big investors seem to be shifting toward companies that supply the hardware for AI, rather than those taking on the biggest spending. 

This difference matters more now for portfolio managers who want exposure to AI but also want to limit financial risk. 

Data Centers Cash Flow Fear Reshapes Technology Valuations 

Much of the current selling pressure centers on data center cash-flow fears. 

Major technology companies have announced unprecedented investments in AI infrastructure. Building hyperscale data centers requires billions of dollars in spending on land acquisition, construction, cooling systems, networking equipment, and advanced semiconductors. 

These investments lower free cash flow in the short term, even though they may create valuable assets over time. 

For investors used to steady profit growth and strong cash flow, this is a big change in how companies manage their finances. 

As a result, investors scared AI spending and cash flow now play a bigger role in how investors value companies, more than just revenue growth forecasts. 

Companies that used to get high valuations for their earnings growth are now being watched more closely for how they spend their money. 

Roundhill MAGS ETF Performance Shows Higher Expectations 

The recent Roundhill MAGS ETF performance should not necessarily be interpreted as evidence that the largest technology companies are losing their competitive advantages. 

Instead, expectations for these companies had become extremely high. 

When stock prices already expect years powered by AI growth, even good quarterly results may not please investors if spending is rising quickly. 

That’s why some companies reported solid results but still saw their stock prices drop right after earnings announcements. 

Markets often care less about what companies have done and more about what they plan to spend in the future. 

This focus on the future helps explain why the Magnificent Seven ETF falls 5 percent week became one of the defining market stories despite otherwise healthy corporate earnings. 

AI Spending Is a Long-Term Opportunity 

Even though there’s more short-term volatility, most analysts still see artificial intelligence as strategically important. 

Cloud providers, software developers, cybersecurity firms, and chip makers are all still investing heavily, since demand for AI isn’t slowing down. 

The main debate now is about timing. 

Investors want to know when today’s infrastructure spending will start to bring higher profits, better cash flow, and steady returns. 

Until there’s more clarity, tech stocks with the biggest spending plans may keep seeing big price swings. 

At the same time, semiconductor companies may keep benefiting as demand for hardware grows throughout different AI platforms. 

What Investors Should Watch Going Forward 

The gap between large tech stocks and semiconductor funds may continue in the next few earnings seasons. 

In the future, market performance will probably depend more on key financial indicators than just revenue growth headlines. 

Investors will watch trends in free cash flow, capital spending plans, progress in making money from AI, how much cloud infrastructure is used, and how stable profit margins are. 

If companies can show that their big AI investments are starting to pay off, the market mood could quickly get better. 

Conversely, if spending continues accelerating without corresponding cash generation, the concerns surrounding data center cash flow fear may continue weighing on the sector. 

The current shift in the market shows that investors are more careful. AI is still a major trend this decade, but investors now want clear proof that big spending will lead to big returns. For now, the difference between the Magnificent Seven ETF’s 5 percent drops and the gains in semiconductor ETFs is a strong indication that even the best growth stories need to deliver steady cash flow.

Source: Magnificent 7 Trade Is Broken — Here’s Where Smart Investors Should Look Next 

Seattle, Washington — Monday, July 27, 2026 

Alphabet’s stock dropped by over $130 billion in one trading session last Thursday. The reason wasn’t a revenue miss; Google’s parent actually beat estimates on both revenue plus profit. Instead, the issue represented a figure hidden in the capital expenditure guidance: up to $205 billion set aside for artificial intelligence infrastructure in 2026, higher than the previous forecast of $180 billion to $190 billion. Free cash flow turned negative for the first time since Alphabet’s 2004 IPO. Investors made up their minds before the earnings call even ended. 

This sets the stage for Amazon, Meta, and Microsoft’s earnings week, which comes at a tense moment. Three of the four biggest hyperscale tech companies report results this week, and Wall Street has made it clear: investors want more than promises about AI spending. 

Hyperscaler Earnings Wednesday Thursday: What’s on the Calendar 

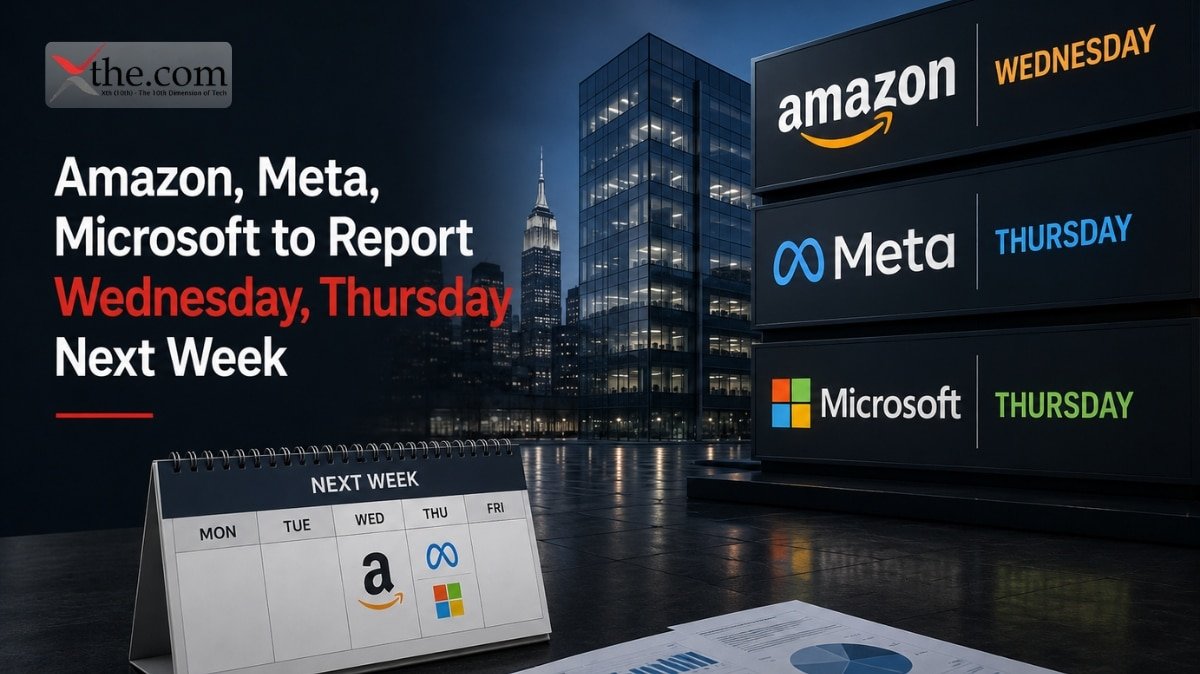
The hyperscaler earnings Wednesday-Thursday window has become the market’s central event for the back half of July. Microsoft and Facebook will report on Wednesday afternoon, followed by Amazon on Thursday. Apple and Qualcomm are also releasing their quarterly results this week, covering almost every part of the tech sector: cloud infrastructure, social media ads, e-commerce logistics, consumer hardware, and mobile chips. 

In short, Big Tech earnings kick high gear this week, and the timing is tough for companies hoping for a warm reception. Alphabet’s sell-off on Thursday pulled the Nasdaq Composite down over 2 percent in one session and cut more than 500 points from the Dow. Meta, Microsoft, and Amazon shares also fell that day, even though they hadn’t reported yet. The market reacted quickly, then looked for answers. 

Why Alphabet’s Report Became a Warning Shot 

Wolfe Research analysts predicted before Alphabet’s report that capital expenditure, not revenue or profit, would be the key number this earnings season. They were right. Alphabet’s cloud division grew 82 percent year over year, which would usually be big news. But instead, the emphasis shifted to a capex figure that could mean over $300 billion in spending for 2027, according to some estimates. That’s much higher than Wall Street expected. 

This reaction creates a real test for the three hyperscalers reporting this week. Big Tech earnings kick into high gear at a moment when investors have decided that spending discipline, not spending ambition, is the metric worth rewarding. 

Megacap AI Spending Scrutiny Reaches a Tipping Point 

The megacap AI spending scrutiny that greeted Alphabet’s results isn’t an isolated event. It shows a broader change in how investors view the AI buildout. Together, the four largest hyperscalers spent $129.8 billion on capital expenses in the first quarter, up 81 percent from last year.UBS expects total spending for the group to rise 76 percent this year, reaching about $673 billion. 

In the past, numbers that big were seen as a sign of confidence. Now, more investors see them as a risk to short-term cash flow and profit margins. Amazon, Microsoft, and Meta all face the same question that Alphabet struggled with: can they show that AI infrastructure spending is turning into revenue quickly enough, or will higher spending forecasts cause a sell-off like Alphabet’s? 

Microsoft may be the clearest test case, since its Azure cloud business is closely linked to AI demand and its partnership with OpenAI. Meta is under the microscope for its expanding data center buildout. Amazon’s AWS, still the top cloud provider by revenue, must show that its capital spending isn’t outpacing demand. 

Apple, Qualcomm Add a Different Kind of Pressure 

Apple and Qualcomm are also announcing earnings this week, alongside the hyperscalers, but face a different kind of scrutiny. Neither spends as much on AI infrastructure as Amazon, Meta, or Microsoft. Apple’s results will focus on iPhone demand and services growth, while Qualcomm’s will show trends in mobile chip demand and licensing revenue. Still, both will be partly judged through the same AI perspective that influenced Alphabet’s call, since AI features are now central to the industry. 

The Semiconductor Makers Rewarded Pattern 

One of the most notable trends this week is the semiconductor makers rewarded pattern that has taken hold even as hyperscaler stocks struggle. Chip and equipment suppliers like Taiwan Semiconductor Manufacturing, Micron, Applied Materials, and others have mostly seen their shares rise amid capital spending increases that hurt Alphabet. In July, TSMC raised its 2026 capex guidance to between $60 billion and $64 billion, and the market saw this as a positive sign, not a warning. 

This isn’t a contradiction, but a structural difference. Chipmakers and equipment vendors get immediate revenue from hyperscaler spending, no matter if that spending leads to AI revenue for Amazon, Meta, or Microsoft. The hyperscalers, on the other hand, take on the financial risk if the AI investment cycle takes longer to pay off. That’s why Micron’s high-bandwidth memory is already sold out for 2026, even though the buyers face investor doubts about their spending. 

Whether this trend continues after this week’s reports is a key question for markets. If Microsoft, Meta, and Amazon can raise their capital spending forecasts without causing a sell-off like Alphabet’s—perhaps by showing clearer proof of AI-fueled revenue growth—it would mean investors are willing to judge companies individually. But if the reaction is another sell-off, it would show that Wall Street has become more skeptical about AI investments, and that higher spending forecasts now carry real risks, no matter the business fundamentals. 

Amazon, Meta, and Microsoft report Wednesday Thursday, and their results will influence tech market outlook far beyond this earnings cycle. Every capital spending figure, cloud growth number, and executive comment about AI monetization will be compared to the standard set by Alphabet’s recent stock move. Companies that show both discipline and ambition may find investors more forgiving than expected. Those that don’t could see a strong quarter eclipsed by just one spending number.

Source: 4 Big Tech earnings reports, a Fed meeting, and $100 oil: It’s the busiest week of the quarter 

New York, New York | July 26, 2026 

A single decision by a large investment fund can move billions of dollars in market value within hours. That reality explains why investors carefully monitor the latest fund manager for top AI hardware stock selections. When an experienced portfolio manager points out companies likely to benefit from AI infrastructure spending, the market often sees it as an early sign of where technology budgets and long-term investments might go. 

Fresh analysis reported by TS2 Tech points to strong AI hardware innovation prospects, with a select group of semiconductors, server, networking, and manufacturing companies that are likely to benefit as spending on AI infrastructure grows. The report also explains why many analysts still see these businesses as some of the best AI stocks for technology sector investors to watch in the coming years. 

Fund manager top AI hardware stocks reflect growing institutional confidence. 

The latest leading fund manager analysis looks at companies that build the physical backbone of artificial intelligence, not just the software that often makes headlines. While generative AI platforms get a lot of attention, they rely on advanced processors, packaging, high-speed networking, memory, and servers that can handle huge amounts of data. 

This view matches what people search for with expressions such as “Fund manager names top AI hardware stocks.” It shows that big investors now prefer companies with lasting strengths rather than taking risks on new AI startups. 

Companies like Nvidia, Taiwan Semiconductor Manufacturing Co. (TSMC), Broadcom, Dell Technologies, Hewlett Packard Enterprise, SK Hynix, and several advanced memory manufacturers. Each occupies a distinct position within the AI supply chain, reducing dependence on any single revenue source while supporting continued AI hardware essential progress. 

Nvidia remains the benchmark for AI infrastructure. 

Nvidia continues to dominate discussions relating to AI hardware innovation prospects because its graphics processing units are the top choice for training and running advanced AI models. 

Demand for AI hardware now goes far beyond big cloud companies. Banks, healthcare groups, drug makers, car manufacturers, and government agencies are all investing heavily in AI clusters that use thousands of GPUs linked by very fast networks. 

Institutional investors see Nvidia’s whole ecosystem, not just its processors, as a major strength. Its CUDA software, networking technology from Mellanox, and ongoing improvements make it costly for enterprise customers to switch to other providers. 

Recent changes in Nvidia’s manufacturing partnerships have boosted investor faith. The new Nvidia-Amkor collaboration shows that advanced semiconductor packaging is becoming more important as chips get more complex. Better packaging improves performance, saves power, and increases manufacturing success, making these companies more appealing to big investors. 

Manufacturing partners gain greater strategic importance. 

The leading fund manager analysis also goes beyond chip designers to include companies enabling semiconductor production. 

Taiwan Semiconductor Manufacturing Co. is still essential because almost every advanced AI processor relies on its manufacturing skills. As chips get more advanced, having top foundry expertise is just as important as designing the processors themselves. 

The company has also caught more investor support after recent progress in advanced chip packaging. As AI accelerators use bigger memory and more complex connections, advanced packaging has gone from being an afterthought to a keyway for companies to stand out. 

This trend supports continued sector expansion for technology firms focused on semiconductor assembly, testing, and packaging. Investors progressively recognize that AI performance depends on an integrated hardware ecosystem rather than a single processor manufacturer. 

Enterprise infrastructure vendors continue gaining momentum. 

Institutional conviction also extends to enterprise hardware providers. 

Dell Technologies recently got higher price targets from analysts after seeing stronger demand for its AI servers. More organizations building private AI systems now need integrated server solutions designed for faster computing tasks. 

Hewlett Packard Enterprise has seen similar positive trends as more businesses invest in AI-ready infrastructure instead of only using public cloud services. Private setups give companies more control over sensitive data and help them meet industry regulations. 

These developments strengthen the case for the best AI stocks technology sector, particularly companies capable of supplying complete enterprise AI systems rather than individual hardware components. 

The recent price target increases for Dell and HPE complement broader institutional confidence reflected in the “AI hardware innovation major prospects” narrative. Rather than representing isolated analyst upgrades, they indicate expanding demand throughout the AI infrastructure value chain. 

Memory and networking continue to be indispensable. 

Artificial intelligence workloads require far more than powerful processors. 

Advanced memory products from companies like SK hynix and Micron are helping AI models grow much larger. High-bandwidth memory is now a key part of modern AI accelerators, cutting down on slowdowns during big computations. 

Networking companies like Broadcom are also seeing benefits as data centers need faster ways for thousands of processors to communicate. Even small drops in delay, measured in microseconds, can make training large language models much more efficient. 

These supporting technologies demonstrate why AI hardware essential progress depends on collaboration across multiple industries instead of a single market leader. 

Why institutional investors remain optimistic 

Professional fund managers usually look at businesses with a long-term view, instead of reacting to daily market ups and downs. 

Several structural trends continue supporting their confidence. 

First, even though AI gets a lot of attention, most companies are still in the early stages of using it. Many are just starting to roll out large-scale AI applications. 

Second, governments around the world are investing more in their own AI infrastructure, which is boosting demand for cutting-edge hardware beyond just business customers. 

Third, new advances in semiconductors are making systems that can process more complex AI models without using much more power. 

These factors jointly reinforce ongoing AI hardware innovation prospects, even as investors remain aware of valuation risks associated with some technology companies. 

Risks investors should monitor 

Even with strong growth expected, there is still uncertainty. 

Semiconductor manufacturing is still at risk from diplomatic problems, supply chain problems, export limits, and changes in business spending. Higher interest rates could also put pressure on tech stock values, even if revenues keep growing. 

Competition is heating up as both established chip makers and new AI chip developers bring out new designs for specialized tasks. 

Still, big investors seem to care more about long-term demand for infrastructure than short-term financial volatility. That perspective explains why the latest fund manager for top AI hardware stock selections emphasize companies with durable competitive advantages across semiconductor design, manufacturing, packaging, memory, networking, and enterprise computing. 

Overall, investment trends still point to steady spending on infrastructure as AI spreads into healthcare, finance, manufacturing, cybersecurity, research, and government. The latest fund manager analysis implies that investors looking for AI exposure may concentrate more on companies building the physical side of the industry, not just software. If enterprise AI adoption keeps growing, today’s leaders in semiconductors, packaging, servers, and networking could stay at the center of the next wave of growth, making top AI hardware stocks a key area for institutional and long-term investors.

Source: A top fund manager unpacks why he’s sticking with AI infrastructure stocks, and flags 2 lesser-known names he’s betting on