Washington, D.C. | Dateline: July 8, 2026 

Half of Americans do not own any stocks. That fact, highlighted by Moody’s chief economist Mark Zandi, explains why the Trump Accounts’ launch in 2026 carried more political significance than a typical savings program. On Monday, President Donald Trump rang the opening bells of both the New York Stock Exchange and the Nasdaq simultaneously from the Oval Office, a made-for-television flourish designed to mark the formal debut of Trump children’s stock accounts for every eligible newborn in the country. It was the first time a president had opened trading on both exchanges at once from inside the White House, and the choreography was deliberate. The Trump investment accounts White House ceremony was not simply a policy rollout. It was a statement that giving children even a small stake in the market could change how Americans view who benefits from a rising stock market. 

What Trump Accounts Actually Do 

Trump Accounts, officially called 530A accounts, work as a special retirement account for anyone under 18. Every U.S. citizen born between January 1, 2025, and December 31, 2028, automatically gets a one-time, tax-free $1,000 deposit from the Treasury. That money is invested by default in the State Street SPDR Portfolio S&P 500 ETF, which tracks the 500 largest publicly traded companies in the country. Treasury officials say more index fund options, including ones from Vanguard and iShares, will be added soon. 

Parents, grandparents, and employers can all add money to the account. Families can contribute up to $5,000 each year in after-tax dollars, and employers can add up to $2,500 per employee, tax-free. The Bank of New York Mellon manages the investments, and families can check their balances using a Trump Accounts app made with Robinhood. The money is usually locked until the child turns 18, when the account becomes a standard IRA. Early withdrawals before age 59½ are subject to penalties, except for buying a first home or paying qualified education expenses. 

Who Qualifies and How to Enroll: Trump Accounts launch 2026 children stock market access birth explained what parents need to know 

To enroll, families use IRS Form 4547, which can be submitted through the Trump Accounts app, during tax filing, or directly on the IRS’s Individual Online Account portal. Children born between 2016 and 2024 who missed the $1,000 deposit can still qualify for a $250 deposit if they live in a ZIP code where the median household income is $150,000 or less, which includes most ZIP codes in the U.S. Any legal guardian, parent, adult sibling, or grandparent can start the process if the child has a valid Social Security number. Interest in “Trump Accounts launch 2026 children stock market access birth explained what parents need to know” has surged this week, suggesting that public curiosity is outpacing official information. 

The Oval Office Spectacle: Trump Stock Wealth Children Policy Meets Wall Street Theater 

The bell-ringing itself supplied the news cycle’s most visual moment. Trump rings NYSE Nasdaq bell Oval Office footage showed the president flanked by Treasury Secretary Scott Bessent as trading commenced on both exchanges simultaneously, a logistical feat that required coordination between two rival market operators that almost never share a ceremonial stage. “With the ringing of the opening bell for the stock market, those accounts will now begin to grow right along with our booming economy,” Trump told the assembled press, adding that between family contributions and government seed funds, roughly $800 million in fresh capital would flow into the market for American children within the week alone. Coverage built around “Trump rings NYSE Nasdaq bell Oval Office Dell computers Trump investment accounts details” spread quickly across financial newsletters, pairing the ceremonial optics with the practical mechanics parents actually needed. 

Standing beside Trump was Michael Dell, founder of Dell Technologies, and his wife, Susan. Dell Michael Dell Trump Accounts involvement has become one of the program’s defining private-sector storylines. The couple pledged $6.25 billion in December, translating to roughly $250 million in seed money for up to 25 million children in lower-income ZIP codes who do not qualify for the government’s $1,000 deposit. Trump used the occasion to promote Dell, telling people to “go out and buy a Dell computer.” Dell’s stock rose more than 7 percent that day. Billionaire Ray Dalio and SpaceX president Gwynne Shotwell also made pledges, with Shotwell planning to donate SpaceX equity to accounts for more than 2 million children in lower-income areas. 

Over 50 companies, including Uber, Intel, IBM, Nvidia, Micron, and Charles Schwab, have agreed to match employee contributions for their children, according to Americans for Tax Reform. The Trump Accounts Wall Street launch has become a philanthropic bidding contest among the country’s largest employers and wealthiest individuals, a dynamic with no real precedent in prior federal savings initiatives, including state-level 529 plans and the long-discussed “baby bonds” proposals Democratic lawmakers floated over the past decade. 

The Democratization Question 

This is where the celebration meets reality. Just before the bell-ringing, Trump told reporters, “You know why I’m profiting? Because the stock market’s going up, everybody’s profiting.” But Federal Reserve data tells a different story. In early 2026, the richest 1 percent of American households owned about half of all corporate stocks and mutual funds, worth around $27.6 trillion. The bottom half of households owned just 1 percent, or about $590 billion. Zandi points out that joining the top 1 percent requires an annual income over $750,000, which most families will never reach. This illustrates the main issue in the Trump stock-wealth children policy debate: giving each newborn $1,000 is a common gesture, but the wealth system they enter is far from equal. 

Bessent points to a Gallup poll showing that 38 percent of American households have no stock investments, saying Trump Accounts aim to fix this. McKinsey estimates the program could help lower-wealth households build between $80 billion and $900 billion in assets over the next decade, but this depends on families continuing to contribute, not just the initial deposit. Connecticut’s state treasurer, Erick Russell, gives a clear example: a family that contributes the maximum $5,000 each year could save $150,000 by the time their child turns 30, while a low-income child who only gets the base deposit might have about $2,500. The universal starting amount helps close the gap at birth, but it does little to close it by adulthood. 

What Comes Next 

For parents deciding whether to open an account, the process is now clear, and the paperwork is available. The bigger question, which will take years to answer, is whether a $1,000 start really changes who has access to the stock market or just creates more small shareholders in a system still dominated by a few. Treasury officials expect more companies and philanthropists to join in the coming months, and the November midterm elections will probably shape the program’s future. What is certain is that these accounts have made childhood savings a key issue in the debate over who owns the American economy. 
Source: https://time.com/article/2026/07/06/trump-accounts-explained-children-investments-what-parents-should-know/ 

Lansing, Michigan — Dateline | July 7, 2026 

A viral speech made her national attention. Four years later, an outside-spending war made her an also-ran. On Sunday, from Traverse City, State Sen. Mallory McMorrow told supporters she was withdrawing, and with that, the Mallory McMorrow Senate campaign suspended became the headline reshaping one of the most consequential contests of the cycle. The announcement, arriving after ballots had already been sent to voters, instantly reset the terms of the Michigan Senate primary in 2026 and left Democrats staring down a binary choice a month before the final vote. 

McMorrow did not call her exit a defeat. “I may be suspending this campaign, but I am not leaving the fight,” she wrote, thanking a campaign she said was built with zero corporate PAC dollars. Even so, the practical effect was immediate: McMorrow campaign ends August primary speculation about whether Democrats would pick a moderate, leaving the choice between two candidates with very different views. 

A Field Cut in Half Overnight 

Until Sunday, three candidates led the Michigan Democratic Senate race 2026: McMorrow, Rep. Haley Stevens, and former state health official Abdul El-Sayed. The seat became available when Sen. Gary Peters decided not to run again, and Democrats have seen it as important for regaining a Senate majority. The Cook Political Report calls the race a toss-up, making every move, including McMorrow’s, national news. 

Her departure narrows the McMorrow Democratic field August primary to a straightforward two-person race. Stevens, a mainstream congresswoman, carries the institutional weight of the party: Senate Democratic Leader Chuck Schumer, former Sen. Debbie Stabenow, and Michigan Attorney General Dana Nessel — who endorsed Stevens within hours of McMorrow’s exit all sit in her corner. El-Sayed, an unsuccessful 2018 gubernatorial candidate, has built his campaign on the opposite foundation, drawing support from Sen. Bernie Sanders and Rep. Alexandria Ocasio-Cortez. 

Who Remains Among the Michigan Senate Candidates 2026 

With McMorrow gone, the list of serious Michigan Senate candidates 2026 effectively shrinks to Stevens and El-Sayed, both of whom now face pressure to absorb her supporters before the August 4 vote. El-Sayed moved fastest, posting a direct appeal within hours of the announcement. He praised McMorrow’s willingness to “fight back against a politics that rigs the system,” and invited her supporters to join his movement against corporate money in politics. Stevens responded by saying she looked forward to working with McMorrow “to build a stronger Michigan for everyone,” focusing on party unity as the election nears. 

The winner of the primary will face Republican Mike Rogers in the general election. Rogers narrowly lost to Sen. Elissa Slotkin in 2024 and is trying again for a seat Republicans believe they can win. The real contest is in November, making Michigan a key battleground for control of the Senate. 

Why the Progressive Democrat Michigan Senate Debate Matters Nationally 

McMorrow first entered the national conversation in 2022, when a floor speech defending LGBTQ families against a colleague’s attack went viral, turning a little-known state senator into a fundraising powerhouse and cable-news fixture. That profile made her exit notable in a way that a lower-tier candidate’s withdrawal would not have been. It also illustrates something larger playing out across this year’s primary calendar: the progressive Democrat Michigan Senate wing and the establishment wing are no longer negotiating quietly behind closed doors. They are running head-on into each other, in public, with outside money settling arguments that used to be settled by party insiders. 

Sources close to McMorrow said her decision was driven by an influx of outside spending, especially from groups like the American Israel Public Affairs Committee, which funded ads supporting Stevens late in the campaign. This spending put pressure on both McMorrow and El-Sayed, but only one could keep up financially. McMorrow could not. 

The Establishment-Versus-Progressive Undercurrent 

This is not an isolated Michigan story. Democratic primaries this cycle have repeatedly forced a choice between candidates aligned with Schumer-era institutional support and candidates gathering energy from the Sanders-Ocasio-Cortez wing of the party. Michigan simply put the fight under the brightest lights, given the state’s standing as a perennial central zone for both the 2026 midterms and the 2028 presidential map. A Democratic nominee who wins Michigan by a wide margin sends a very different signal to national strategists than one who limps across the finish line and either outcome will shape how the party approaches its next open Senate seat, wherever that turns out to be. 

El-Sayed, for his part, cast the moment in explicitly structural terms, accusing “party insiders” of trying to anoint a nominee rather than let voters decide. Whether that argument gains traction with McMorrow’s coalition, which skews toward suburban moderates and younger progressives alike, may determine whether Michigan Democrats nominate a candidate built for a general-election fight or one built to satisfy the party’s activist base. 

Mallory McMorrow Suspends Michigan Senate Campaign; August Primary Field Narrows; 2026 Explained 

For readers trying to make sense of the shift in one sitting, the short version is this: Mallory McMorrow suspends Michigan Senate campaign; August primary field narrows; 2026 explained is the story of a well-funded, high-profile candidate who could not match a late upswing of outside spending directed at a rival, and who chose to exit on her own terms rather than fight to the last vote. The longer version, laid out above, involves donor math, national factional politics, and a primary calendar that suddenly rewards clarity over packed fields. 

What Comes Next for Michigan Democrats 

The Aug. 4 primary is now a five-week sprint between two candidates with clearly defined bases and almost nothing in common in terms of message discipline, donor coalitions, or a theory of the case for beating Rogers. For anyone still asking about the Michigan Democratic Senate primary 2026, McMorrow drops out; who remains in race candidates, the answer now sits with just these two. Stevens will lean on her institutional backing and a case that she is simply the stronger general-election candidate. El-Sayed will lean on grassroots energy and a direct appeal to voters frustrated with establishment control of the process. 

McMorrow closed her own statement without ambiguity about where her loyalty will land once voters decide. She told supporters that whoever wins the primary will have her full support against Rogers in November, a line clearly designed to keep her donor and volunteer network engaged regardless of which faction claims the nomination. For a party that cannot afford to lose enthusiasm heading into a toss-up race, that endorsement-in-waiting may prove to be McMorrow’s most consequential contribution to the contest yet — bigger, in practical terms, than anything her campaign could have delivered had she stayed in the race through August.

Source: Mallory McMorrow suspends Senate campaign in Michigan 

Washington, D.C. | July 7, 2026 

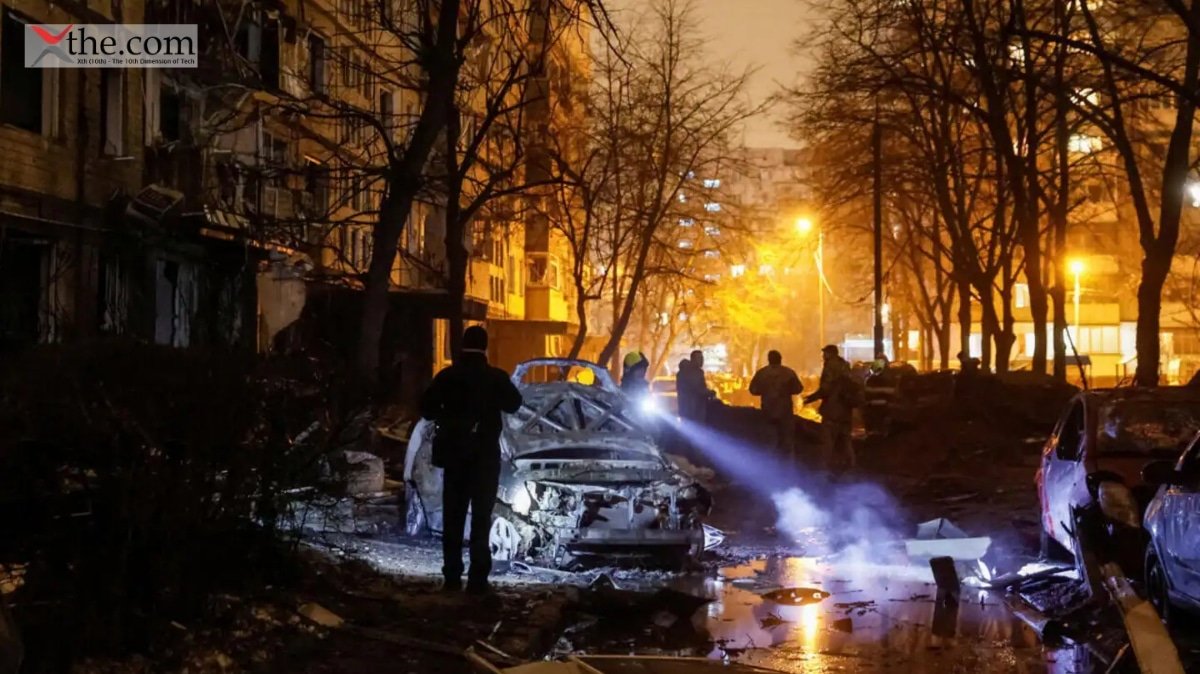
Before dawn on Monday, rescue teams pulled an entire family from the rubble of a collapsed apartment building in Kyiv’s Podilskyi district before dawn on Monday. By the time crews finished digging inside the wreckage, the death toll from the Russia Kyiv missile attack in July 2026 stood at 15 in the capital and six more in the surrounding region, with dozens wounded. The timing was not incidental. Hours before world leaders met in Turkey, Moscow sent a clear and violent message. 

A Strike Engineered for Maximum Political Weight 

The Kyiv attack on July 6, 2026, occurred in the early hours of July 6, 2026, and saw ballistic missiles and drones strike four districts of the city. Officials reported that Podilskyi district was hit hardest, with a residential building partially collapsing and trapping families under the debris. In Darnytskyi district, several apartment blocks were damaged, adding to the destruction from an earlier attack just days before. 

Kyiv Mayor Vitali Klitschko spoke of massive destruction across the city as rescuers evacuated residents, including children, from the upper floors of damaged buildings. Cars burned in the streets. Families spent hours in air raid shelters, unsure if their homes would survive the night. 

The scale of the bombardment was staggering by any measure. Ukraine’s air force reported that Russia 68 missiles and 351 drones at Kyiv were launched overnight, targeting mainly the capital. Every single ballistic missile fired hit its target. Not one was intercepted. That detail, more than any other, has changed the conversation among Western defense officials this week, because it exposes a gap that money alone has not yet closed. 

Why the Timing Was the Real Message 

Vladimir Putin did not choose Monday morning by accident. The Russia-NATO summit Kyiv strike landed less than 24 hours before President Donald Trump was set to leave for Ankara, where NATO leaders would discuss future support for Ukraine. President Volodymyr Zelensky saw it coming. The day before the attack, he posted on social media that the assault was “typical of Putin,” coming right after America’s Independence Day and just before the NATO summit. 

The strategy is clear. A major attack right before a summit sets the agenda, confronting delegates with images of destroyed homes and grieving families. It also challenges the alliance’s unity, as hesitation now costs civilian lives, not just words. Trump spoke with Zelensky by phone on Saturday and had a long call with Putin on Sunday, according to Russia’s foreign ministry, offering to help end the war. Within a day, Russia responded with 68 missiles. 

Zelensky’s Direct Appeal to the Alliance 

Standing in the ruins of Kyiv, Zelensky spoke directly. He said Ukrainian forces could handle drones and cruise missiles, but not Russian ballistic missiles, a gap he attributed squarely to a shortage of interceptors. That framing represents Zelensky’s NATO-strong decisions at the center of this week’s summit: he urged American and European partners to leave Ankara with real commitments, not just more statements. 

Zelensky’s frustration stems from months of near-nightly attacks. He argued that as long as Patriot interceptor missiles stay in allied stockpiles instead of being sent to Ukraine, Russia will keep targeting homes, believing the political cost is less than the military risk. The phrase seen in Western media this week, “Zelensky urges NATO strong decisions Ukraine air defense Patriot missiles after Kyiv attack 2026,” sums up what Ukrainian officials want: action, not just words. 

The Air Defense Gap That Won’t Close Itself 

The unpleasant truth for NATO planners is structural, not simply political. The Ukraine air defense shortage ballistic missiles problem stems from basic physics and finite production capacity. Drones and cruise missiles can be intercepted by a range of mobile systems, some of which are relatively inexpensive. Ballistic missiles are a different category of threat entirely, requiring sophisticated interceptors like the Patriot system, which are manufactured in limited numbers and are in high demand across multiple theaters, including the recent strain from conflict in the Middle East. 

Ukrainian Air Force spokesman Yurii Ihnat explained the matter clearly on national television. He said stopping ballistic missiles requires the right equipment, and Russia is taking advantage of a worldwide shortage of interceptor missiles. For Kyiv’s residents, this shortage is not theoretical. It means the difference between a missile hitting an empty field and one hitting an apartment building full of people. 

Residential Streets Bear the Brunt 

Tymur Tkachenko, head of Kyiv’s Military Administration, described the human reality behind the statistics. The Kyiv residential buildings destroyed in Monday’s strike, he said, were homes where people slept and lived their daily lives. Several multistory buildings in Darnytskyi district were damaged, with residents trapped under rubble for hours as emergency crews searched for survivors. 

Russia’s Defense Ministry gave a different explanation, saying the strikes targeted weapons factories, including places that make drones, armored vehicles, missiles, air defense repair sites, and energy infrastructure. These claims could not be independently confirmed and contrast with a well-documented pattern: Russian air attacks have often hit civilian neighborhoods during the war, which has killed over 16,000 Ukrainian civilians according to the United Nations. The headline “Russia kills 15 people massive Kyiv missile drone attack eve of NATO Ankara summit July 6 2026” sums up a familiar cycle: an attack, a denial, a rising death toll, and a summit forced to respond. 

A War That Refuses to Wait for Diplomacy 

The attack happened as both sides escalated their actions. Ukraine has stepped up strikes on Russian energy infrastructure, hitting oil refineries and ports deep inside Russia. Moscow’s Defense Ministry used these attacks to justify the bombardment of Kyiv. Now, both sides see infrastructure whether energy sites in Russia or apartment buildings in Ukraine as fair targets in a war that shows no sign of ending soon. 

For the delegates meeting in Ankara, it is now clear that Ukraine needs more air defense. Monday’s casualties made that obvious. The real issue is whether allied governments can act faster than Russia’s next attack, and whether “strong decisions,” as Zelensky put it, will lead to faster Patriot deliveries and more production, or just more statements with no action. For Kyiv’s residents, still picking through the rubble, words alone are not enough. 

Source: Deadly Russian strikes hammer Kyiv on eve of Trump trip to critical NATO summit 

New York, New York |  July 6, 2026 

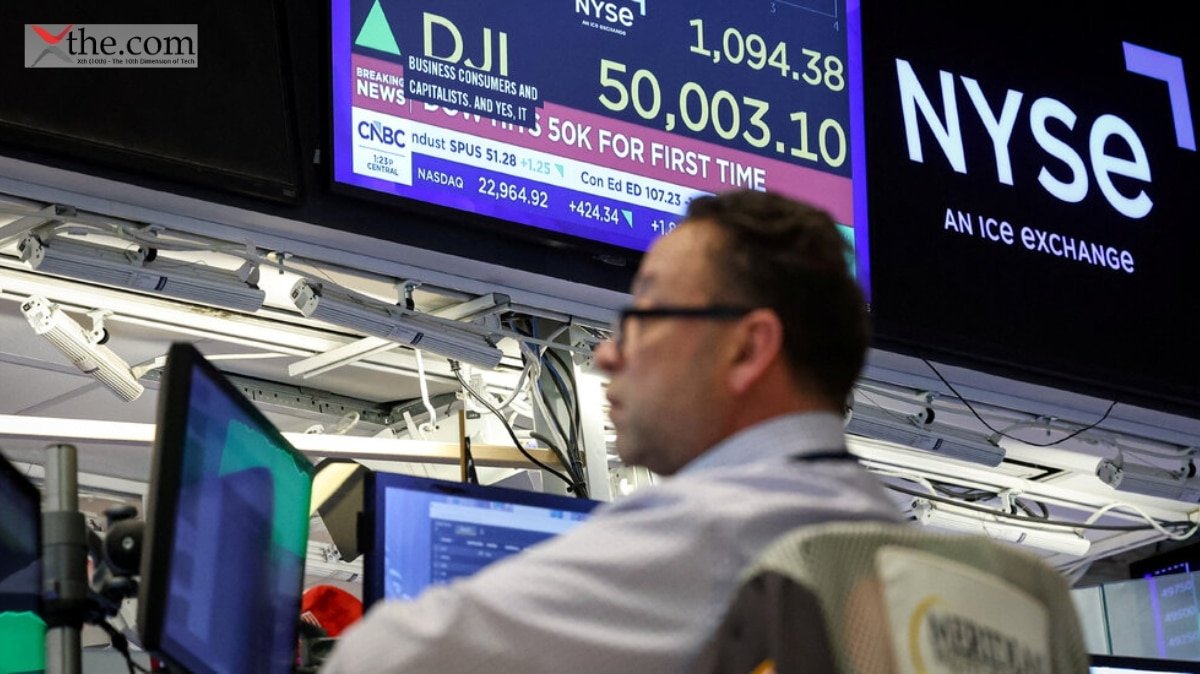
Fifty-three thousand and fifty-five points. That is where the Dow Jones Industrial Average settled at Monday’s closing bell, a number that did not exist until this week. The Dow Jones record 53000 July 2026 milestone arrived four trading sessions after the index first cleared 52,000  the fifth 1,000-point marker this year, compared with only three in all of 2025. Investors back from the Independence Day holiday found a market in a hurry, and semiconductor stocks were doing most of the pushing. 

A Record Close Built on Narrow Leadership 

The Dow Jones Industrial Average’s new record July 6 print reflected a gain of 155.84 points, or 0.29%, closing at 53,055.91 a modest advance by percentage terms that masked a sharper story underneath. Six of the so-called Magnificent Seven technology stocks advanced on the day, and chipmakers did the heavy lifting for the wider tape. Boeing, IBM, and Goldman Sachs led the thirty Dow components in percentage terms, while Amgen, Walt Disney, and Merck dragged on the index. Jake Dollarhide, chief executive officer of Longbow Asset Management, offered a blunt read on the session: this is a market leaving many stocks out even as the headline number climbs. 

The Dow hits record high tech rebound pattern has become common this summer. Since the index first passed 52,000, Apple has added the most points to the Dow, while Caterpillar has held it back the most. This split shows that in mid-2026, money is moving toward artificial intelligence infrastructure and semiconductor companies, and away from industrial and consumer firms that are still dealing with higher costs from tariffs. 

Tech Stocks Rebound Sharply on a Chip Supply Deal 

The catalyst for Monday’s tech stocks rebound on July 6 was not an earnings report but a regulatory filing. Broadcom and Apple disclosed an expanded technology partnership running through 2031, under which Broadcom will develop and supply custom ASIC silicon for multiple future generations of Apple hardware. Broadcom shares jumped roughly 3.8%, Apple gained more than 1%, and the Philadelphia Semiconductor Index climbed 2.6%. Western Digital surged nearly 7%, Advanced Micro Devices rose close to 6.6%, and Qualcomm added more than 6%, extending a recovery from last Thursday’s sharp chip pullback. The short version of Dow Jones hits record 53000 July 6 2026 tech stocks rebound sharply after chip selloff explained: a narrow group of AI-linked suppliers absorbed nearly all of last week’s losses in a single session, and the rest of the index came along for the ride. 

Premarket futures told a similar story before the opening bell. Nasdaq 100 futures were pointing toward strength that some early trading desk notes flagged as approaching a Nasdaq 1.5 percent July 6 move, though the index ultimately settled with a somewhat more restrained 1.12% advance, closing at 26,121.16 once the session played out. The S&P 500 added 0.72% to finish at 7,537.43, its own marker in a week that has already delivered back-to-back index records. 

S&P 500 Market July 7 Faces a Three-Event Convergence 

The S&P 500 market July 7 setup is unusually crowded for a single trading day. Three catalysts converge on Tuesday, each capable of moving capital on its own, together forming the real test of whether Monday’s rebound has staying power. 

First, SpaceX officially joins the Nasdaq-100 index, following the company’s record $85.7 billion initial public offering in June. Passive funds tracking the index must establish positions, a mechanical flow that has routinely provided a tailwind regardless of the day’s news. 

Second, Samsung Electronics will release its preliminary second-quarter results. Analysts expect operating profit to be around 86 trillion won, or about $56 billion, which is seventeen to eighteen times higher than last year. Without a one-time labor charge from May, some believe profit could have exceeded 100 trillion won for the first time. The surge is caused by strong demand for high-bandwidth memory and DRAM prices rising nearly 60% from the previous quarter. 

Third, SK Hynix is completing its institutional bookbuilding ahead of its Nasdaq American Depositary Receipt listing, which is expected to raise about $29 billion under the ticker SKHY. Stock market week July 7 2026 Dow record SpaceX Nasdaq-100 SK Hynix IPO, Samsung earnings’ to sum up how packed this week’s calendar is. This offering would be the second-largest stock listing ever, behind only SpaceX’s IPO, and larger than Saudi Aramco’s 2019 listing and Alibaba’s 2014 listing. 

AI Bull Market Continues, With a Caveat 

The AI bull market continues narrative has now survived two stress tests in a single week: a sharp selloff in chip stocks on Thursday and a holiday-shortened week that usually means less trading and more volatility. On Monday, Micron rose 0.9%, Nvidia gained 0.4% after its partner Hon Hai Precision Industry reported strong AI demand, and Intel added 1.5%. John Stoltzfus, chief investment strategist at Oppenheimer Asset Management, said in a Monday note that stocks could keep rising in the second half of the year if first-half fundamentals remain strong, but he also warned that volatility remains a risk investors need to watch. 

Not everyone is completely confident, though. Some strategists warn that with so much money in just a few big tech stocks and lower trading volumes in the summer, the market may be more fragile than the headline numbers show. 

The July 8 FOMC Minutes: The Next Real Catalyst 

On Wednesday, the Federal Reserve will release meeting minutes, the first major written record under new Fed Chair Kevin Warsh. The minutes should reveal how the committee is balancing the inflation shock from the earlier U.S.-Iran conflict with an underwhelming June jobs report of 57,000 new jobs, far below the 110,000 estimate. Adam Sarhan, CEO of 50 Park Investments, said the low payroll number eases pressure on the central bank. Steve Englander of Standard Chartered expects Warsh to keep the minutes less detailed about individual members’ opinions, in line with his preference for tighter communication. 

The stakes are high. Markets expect interest rates to stay steady this summer, but that view has not been tested against the Federal Reserve’s full discussion of inflation driven by higher oil prices. If the minutes show more disagreement than expected, Monday’s gains could quickly fade. 

What Comes Next 

The Dow’s move past 53,000 is important not just for the number itself, but for what it reveals about the market as we enter the second half of 2026. A few semiconductor and AI infrastructure stocks are driving up most of the gains, while many industrial and healthcare stocks are flat or down. On Tuesday’s events SpaceX joining the index, Samsung’s earnings, and SK Hynix’s bookbuilding will show if money keeps flowing into the same stocks or starts to shift. Wednesday’s Fed minutes will answer another big question: does the central bank see the Iran-related inflation as a short-term shock or a longer-term problem that needs caution beyond the summer? Either way, the outcome will affect more than one index.

Source: Dow Jones Notches New Record Close Above 53,000 as Tech Stocks Rebound Sharply to Start the New Trading Week 

Mountain View, California | July 6, 2026 

Four senior Gemini researchers left for a rival lab in just one week. That number is a key reason why Google decided to pull Gemini 3.5 Pro pulled from its planned June release, and it should concern any enterprise buyer who was counting on the model for the third quarter. At I/O in May, Sundar Pichai asked the audience to “give us until next month.” The audience groaned. Now, Google is explaining in careful corporate language why ‘next month’ turned into ‘next quarter.’ 

The Gemini 3.5 Pro delay is not a single failure. There are three engineering problems that compound on each other, and together they explain why a model built to be Google’s flagship reasoning model is still only available in a limited Vertex AI preview, while its less expensive sibling handles most of the production work. 

The Three Reasons Behind the Delay 

Both Business Insider and Tech-Insider report the same causes of the delay, which can be summed up simply: Google pulls Gemini 3.5 Pro for three reasons: token costs, coding performance, and enterprise concerns. In short, the model used more tokens than expected, its coding output was worse than a cheaper model in the same family, and its long-task reasoning did not meet the standard Google set in May. 

Token Efficiency Becomes a Boardroom Metric 

The first and most damaging problem is Google AI model token efficiency, or the lack of it. Early enterprise testers running extended agentic workloads on Vertex AI found that Gemini 3.5 Pro consumed tokens far faster than its published benchmark scores suggested. A model that answers a coding question correctly but takes three times as many tokens to get there is not actually cheaper to run, no matter what the leaderboard says. That distinction matters more in July 2026 than it did a year ago because Gemini 3.5 Pro token-burn enterprise costs are no longer buried in a monthly invoice that nobody reads. Finance teams now ask procurement to show their work. 

Microsoft sped up this change by publishing average token usage per task on its model release cards, turning Microsoft’s cost-to-complete benchmark into nearly an industry standard. Now, when a chief information officer compares models, they care less about leaderboard scores and more about which model completes tasks for the lowest total cost, including retries and tool calls. Gemini 3.5 Pro did not come out on top in these comparisons, and Google seems to have realized this before its customers did. 

Coding Performance Gap 

The second problem is more embarrassing, because Google built it into its own product line. Gemini 3.5 Flash beats Pro coding benchmarks today, doing so at roughly four times the speed and at a fraction of the cost. Flash was never supposed to outperform the flagship it was meant to complement. Developers who tested Pro in preview found coding and agentic scores that lagged behind Flash on multiple key benchmarks, a result that undercuts the entire logic of Google’s tiered model strategy. Paying a premium for a slower, pricier model only makes sense if that model is measurably better at the thing developers actually do with it, and coding is that thing for a growing share of enterprise workloads. 

The Third Reason and the Competitive Cost of Waiting 

The third and least discussed problem is long-task, multi-step reasoning. Google set an internal bar for Gemini 3.5 Pro at its May unveiling, and the model has not consistently cleared it on extended, multi-turn agentic tasks, the kind that involve planning, executing, checking, and correcting across dozens of steps rather than answering a single prompt. That gap explains why Google chose delay over a flawed launch. It also explains the real cost of the wait. Every week that passes without a Pro-tier release is a week in which Claude Sonnet 5 and GPT-5.6 Terra sign enterprise contracts that assume Google’s flagship model does not exist yet. Procurement cycles in large organizations run for months, not days, and once a company standardizes its agentic workflows on a competitor’s API, switching back involves real engineering cost. Why Google delayed the Gemini 3.5 Pro launch: token-efficiency coding flaw, enterprise buyer explained. It’s the question every rival sales team is answering for prospective customers this week, and they are answering it in their own favor. 

Enterprise Buyers Change the Rules 

None of this happens in a vacuum. The wider Google AI model delay 2026 story fits a pattern that has repeated across the industry this year: models announced with confidence, followed by quiet slippage once real-world testing reveals problems that internal benchmarks missed. Google has now missed two major delivery targets in one year, and this trend is changing how enterprise architects plan their projects. Teams using Vertex AI now see a July general-availability date as a bonus, not a guarantee, and this prudence will likely slow adoption when Pro is finally released. 

There is a real upside for Google if it can keep it. The 2-million-token context window and Deep Think reasoning mode are features that no other production model currently offers at this scale. For teams that need codebase-level reasoning or multi-session agents that can handle large amounts of context without losing track, this is a true advantage—not just a marketing claim. It is worth waiting for, as long as the wait is not too long and the token costs are fixed before launch. 

What Comes Next for Google 

Google says the delay is about quality, not a mistake, and there is some truth to that. Releasing a flagship model that is more expensive to run than expected would have been worse than waiting a few more weeks. But this explanation only works for so long. The fact that researchers left for Anthropic the same week the delay was announced is not something Google can easily explain away, and enterprise buyers signing contracts with competitors are not going to wait out of loyalty to a model they have not been able to use. 

Google still has the largest compute resources and the widest distribution network of any AI lab. Whether this advantage lasts after one more missed deadline depends less on Gemini 3.5 Pro’s benchmark scores than on whether, when released, it can demonstrate that intelligence and capability can go hand in hand.

Source: AI News Today July 6 2026: 15 Biggest Stories 

New York, NY, July 6, 2026 

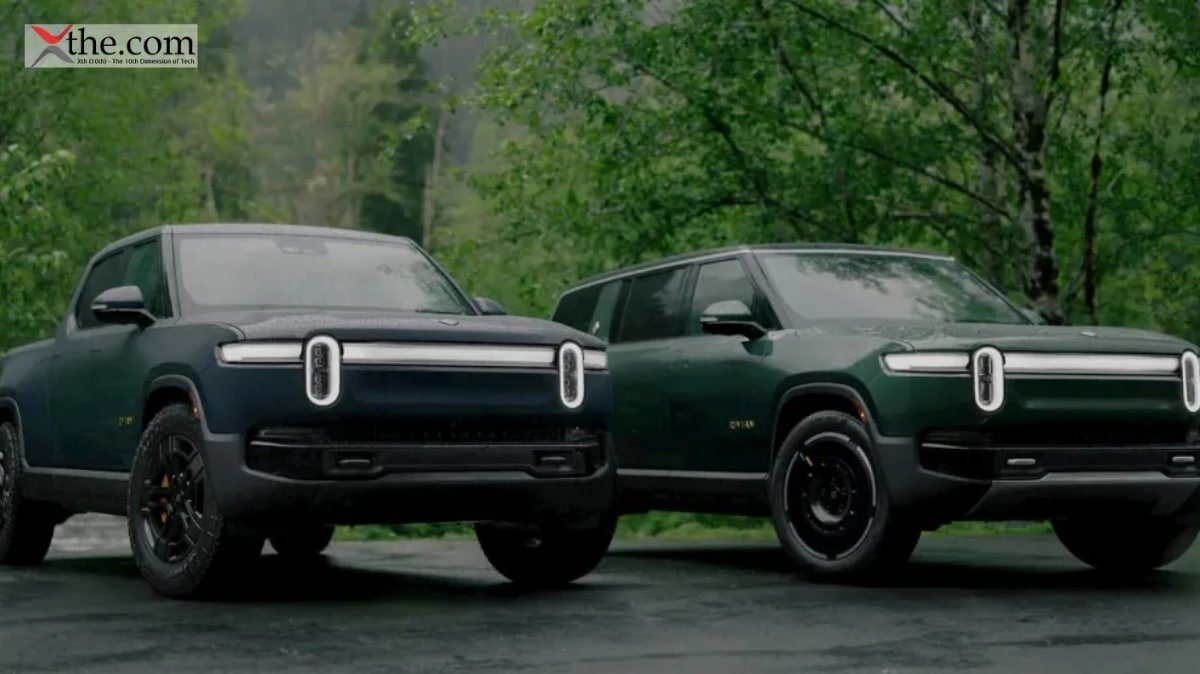
Tesla shares reached $416.50 at midday, rising sharply as the session turned a battered sector green across the board. Tesla TSLA rises 6 percent in July 2026, trading at $416.50 during Monday’s session, and this move lifted the rest of the electric-vehicle group. Rivian gained 7%. Lucid also climbed 7%. Nio added 5%. Autonomous-vehicle funds caught the same bid. Call it what it is: an EV sector rally July 7 in the making, even if the calendar on the tape still read July 6 when the first wave of buying began. 

The headline number is less important than the reason for it. Tesla delivered 480,126 vehicles in the second quarter of 2026, up 25% from a year ago, while energy deployments increased by 41% over the same period. Sell-side desks spent the morning revising estimates upward. That is the textbook definition of a Tesla delivery beat EV rally, the kind of print that reprices an entire sector on the assumption that if the largest player is finding demand, the smaller ones might too. 

Why Tesla’s Number Moved the Whole Board 

Tesla’s stock had been struggling for weeks. Even after Monday’s jump, shares are still down 8% for the year, so this looks more like a short-term bounce than a full turnaround. Two main factors drove the move: the delivery beat improved the fundamentals, and Tesla’s Miami expansion of its robotaxi service, following the Austin launch, added to the story. Rolling out Full Self-Driving Model Y vehicles in another city gave investors new information about monetization, though some doubts remain. Gary Black of The Future Fund expects a short-term rebound but still thinks the stock is fully valued at a 2026 price-to-earnings ratio above 200, which assumes robotaxi profits arrive sooner than Tesla has shown so far. 

Prediction markets reflected this uncertainty. Polymarket gave just a 13% chance of a California robotaxi launch by the end of the year, but short-term contracts showed a 98% chance that Tesla would close higher that day. On Monday, investors were focused on the delivery numbers and the Miami news, not the long-term robotaxi story. For that session, it was enough. 

Rivian and Lucid Ride the Coattails 

Here is where the Rivian RIVN 7 percent jump gets interesting: there was no new company-specific news on Monday. The stock rose to about $20, driven by Tesla’s strong results and a generally positive mood in the EV sector. Rivian shares are now roughly flat for the year, a big improvement from a month ago, when they were down over 20%. The company’s own news came on July 2, when it reported 12,194 second-quarter deliveries, beating its guidance of 9,000 to 11,000, and increased its full-year delivery target to 65,000 to 70,000 vehicles, up from 62,000 to 67,000. Software and services revenue grew 49% year over year to $473 million, helped by the Volkswagen partnership. A $1 billion equity investment from Volkswagen and a $4.5 billion Department of Energy loan for the Georgia plant have also eased Rivian’s capital concerns from 2025. 

Lucid’s situation is more complicated. Shares rose 7% to $6.51 on Monday, but the stock is still down about 40% for the year, and overall sentiment is low at 31. The company produced 4,774 vehicles and delivered 3,953 in the second quarter, missing Wall Street’s estimate of around 5,000 units. New CEO Silvio Napoli announced a leadership shake-up alongside the miss. That combination, a delivery shortfall paired with executive turnover, is not the profile of a company benefiting from anything other than sector-wide buying. Rivian, Lucid, and Nio gains, in other words, describe three very different underlying stories wearing the same green candle. 

Nio and the China Angle 

Nio finished the EV sector rally on July 7 with a 5% gain to $5.03, even though its shares are still down 8% for the year and there was no new company news this week. Nio has a strong prediction-sentiment score of 64, which is higher than Rivian’s or Lucid’s. Investors watching the Chinese EV market are also paying attention to BYD, which sold 557,090 fully electric vehicles in the second quarter, more than Tesla’s 480,126. This shows that Tesla’s delivery beat happened in a very competitive global market. 

The DRIV ETF Angle for Diversified Exposure 

For investors who want to benefit from the sector’s move without picking a single stock, the DRIV ETF for autonomous vehicles is one option. The Global X Autonomous & Electric Vehicles ETF holds 76 stocks, limits each to about 3%-4%, and covers the entire value chain, from automakers to chipmakers and battery suppliers. Alphabet, Bloom Energy, and Tesla are among its biggest holdings, and the fund has an expense ratio of 0.68%. This setup is useful on days like Monday, when gains across Tesla, Rivian, Lucid, and Nio were driven by a broad market trend rather than individual company news. Using a fund like DRIV helps reduce the risk of a single stock losing its gains if the sector-wide rally fades. 

Every part of this session traces back to one search query that will define trading through the summer: Tesla rises 6 percent, Rivian, Lucid jump 7 percent, NIO gains 5 percent. EV sector rally July 6, 2026 captures Monday’s tape precisely: four stocks moving together on one company’s fundamentals. The follow-through question is whether that pattern holds into Tesla Q2 earnings July 22, the date that will force the market to separate durable delivery momentum from a single good quarter. 

What Investors Should Watch Next 

The next two and a half weeks carry real weight. Rivian reports its second-quarter financial results on July 30, a date that will test whether the margin picture aligns with the delivery beat, given that the company burned through $1.08 billion in free cash flow in the first quarter alone. Tesla’s July 22 earnings call will address robotaxi economics, energy margins, and 2026 guidance directly, and the answers there will likely matter more to the stock than Monday’s delivery number already has. For anyone building a position around this EV sector rally, July 2026 Tesla Q2 delivery beat Miami robotaxi DRIV ETF investor guide, the discipline that matters most is size. Rivian, Lucid, and Nio moved Monday on sympathy, not substance, and sympathy trades tend to unwind as fast as they build. Tesla’s own valuation, at a P/E north of 200x, leaves little room for a soft earnings call to be forgiven. The rally is real enough to trade. It is not yet real enough to trust without a second data point.

Source: Tesla Rises 6% on Robotaxi and Delivery Momentum, Rivian and Lucid Jump 7%, Nio Gains 5% in EV Sector Rally 

New York, New York | July 6, 2026 

Three words from an Nvidia spokesperson erased a week of chip-sector jitters in a single trading session. “Our roadmap is intact,” the company told reporters Monday, and the market believed it. The Nasdaq 100 rally on July 6, 2026, delivered a Nasdaq 100 1.5 percent gain, snapping a two-session slide in semiconductor names and reviving the argument that the artificial-intelligence trade still has runway left. For an index that had spent the prior week absorbing supply-chain anxiety out of Asia, Monday’s session looked less like relief and more like conviction. 

What Triggered the Selloff Nvidia Had to Answer 

The problems began with a research note. Semi Analysis reported that Nvidia’s next-generation Kyber NVL144 server rack, which combines 144 of the company’s top chips into a single unit, was facing manufacturing delays that could push its release to 2028. The report pointed to a tough engineering issue: the printed circuit board midplane at the heart of the Kyber design was too difficult to produce reliably at scale, and cloud providers were concerned about the system’s complexity. 

The Nvidia server delay in Asia jolted the narrative and spread fast. Ibiden, a key Japanese PCB maker for Nvidia, dropped about 10 percent. Kingboard Laminates Holdings in Hong Kong fell 18 percent, Taiwan’s Elite Material Co. closed down nearly 10 percent, and Samsung Electro-Mechanics lost over 10 percent during the day. Shawn Oh, head of Korea cash equities at NH Investment & Securities in Seoul, said the report made Nvidia’s future plans less certain and gave competitors more opportunity. AMD shares rose for the same reason: any setback for Nvidia benefits rivals like AMD, which is already selling its own 72-chip server rack. 

Nvidia Roadmap Intact, According to the Company 

By the time U.S. markets opened, Nvidia had responded. A spokesperson’s brief reply, sent by email, became the phrase traders repeated all day: Nvidia roadmap intact. The company did not share detailed updates on the Kyber NVL144 or directly confirm or deny any delay. Instead, it confirmed that its current Rubin chip systems are still in full production and will start shipping this fall. Nvidia’s alternative NVL72x2 rack design was reportedly canceled, adding greater context to the story but not changing the main message. 

Healthy financial results made Nvidia’s response more convincing. The company’s revenue reached $215.9 billion in fiscal 2026, up from $26.9 billion in 2023 when the AI boom began. Wall Street expects revenue to grow to about $392.7 billion in 2027. In this context, a one-year delay for a new server rack seems like a manageable technical issue, not a major problem. Investors agreed: after some early swings, Nvidia shares finished the day higher. 

Chip Stocks Rebound Across the Board 

The chip stocks rebound extended well beyond Nvidia itself. The VanEck Semiconductor ETF advanced alongside the broader tech sector, and the session’s standout mover came from an unrelated corner of the supply chain. Broadcom Inc. shares jumped over 5 percent after the company announced it had extended its custom-chip partnership with Apple Inc. through 2031. Under this new deal, Broadcom will make application-specific integrated circuits, or ASICs, for “multiple generations of Apple products.” Broadcom has supplied Apple with radio-frequency chips for cellular, Wi-Fi, and Bluetooth, and this extension builds on a multibillion-dollar 2023 agreement for U.S.-made 5G parts. 

Investors also noted another key point: Apple is reportedly using Broadcom’s ASIC technology in its own AI server chips, called Baltra, to support cloud-based Apple Intelligence features. Apple makes up about 20 percent of Broadcom’s yearly revenue, and this five-year extension gives both companies more certainty at a time when component costs are unpredictable. Earlier this year, Apple had to raise prices on Macs and iPads because memory chip costs rose, underscoring that supply-chain stability is now just as important as chip performance. 

The Long-Tail Story: How the Session Actually Unfolded 

Reduced to a single statement, Monday’s action was this: the Nasdaq 100 climbs 1.5 percent, Nvidia confirms roadmap intact after server delay report July 6 2026, and the rally had two distinct legs. The first was defensive Nvidia neutralizing a credible threat to sentiment with a terse but effective statement. The second was offensive Broadcom demonstrating that the AI hardware ecosystem extends well past GPU makers into the connectivity and custom-silicon suppliers that make those systems function inside real devices. Put another way, why chip stocks rebounded on July 6, Nvidia roadmap server delay explained, AI bull market intact, comes down to investors distinguishing between a component-level manufacturing snag and a fundamental threat to AI infrastructure spending. They concluded it was the former. 

Magnificent Seven ETF Gains Reinforce the Broader Theme 

The session’s breadth was evident in fund flows. The Roundhill Magnificent Seven ETF, which tracks the cluster of mega-cap technology names that have driven a disproportionate share of market gains over the past several years, advanced in premarket trading Monday. Magnificent Seven ETF gains of roughly half a percent may look modest against Broadcom’s double-digit-adjacent pop, but the signal is what matters: institutional capital treated the Kyber report as noise rather than a reason to rotate out of large-cap tech exposure. 

That distinction sits at the center of the AI stocks bull market more room argument that has dominated trading desks for weeks. Skeptics have pointed to stretched valuations and the sheer scale of capital expenditure required to keep pace with AI demand. Bulls counter that revenue growth at companies like Nvidia has consistently outpaced even aggressive analyst projections, and that supply-chain hiccups, however headline-grabbing, are a normal feature of an industry scaling at this velocity rather than evidence that the cycle is ending. Monday’s price action sided with the bulls, at least for one session. 

Reading the Tape Beyond Chips 

In other news, Lockheed Martin agreed to buy Ultra Maritime, a naval systems company, for $3.45 billion to boost its undersea defense business. TeraWulf signed a 20-year lease linked to AI infrastructure needs. SK Hynix began the process of a $28 billion U.S. listing, underscoring how important memory chips have become in the AI story. While these events did not drive Monday’s main market move, they show that investors are looking for ways to invest in AI infrastructure beyond just the biggest tech names. 

What Comes Next for Chip Investors 

Nvidia’s response gives the company more time, but not complete certainty. The Kyber issue will come up again when Nvidia reports earnings or gives further details about its next-generation racks. If a real delay is confirmed, the same selloff that just ended could return. Competitors are moving ahead too: AMD is already shipping its 72-chip rack, and big customers like Google and Amazon are building their own chips to rely less on any one supplier. 

For now, the market has made its decision. A single day of gains does not answer whether AI spending can continue to support today’s high stock prices, but it does show that investors are still ready to buy when the issue is a manufacturing delay rather than a drop in demand. The next big test will come from Nvidia’s own financial results, not from another research report.

Source: Nasdaq Composite Climbs to a New Record High as Tech Stocks Rally Sharply After Late-June Chip Sell-Off 

San Jose, California | July 6, 2026 

Twenty percent of Broadcom’s $60 billion annual revenue is now secured for the next five years. This is the main takeaway from a one-page regulatory disclosure Broadcom filed with the Securities and Exchange Commission on Monday, and it explains why traders bid the stock up within minutes of the filing hitting the wire. The document confirms the Broadcom Apple partnership 2031, a multi-year extension of the two companies’ technical cooperation that had been due for renewal amid growing questions about Apple’s move toward making its own chips. 

The filing is only a few paragraphs. Its market impact does not. Shares of Broadcom jumped as AVGO stock rises 4 percent in premarket trading, a reaction that reflects less surprise than relief. Wall Street had devoted months speculating about how much of Broadcom’s Apple business might shrink as Apple developed its own chip design teams. Monday’s filing gave a clear answer, at least for the rest of the decade. 

What the AVGO Apple Chip Deal Actually Covers 

The core of the AVGO Apple chip deal is a set of new long-term supply agreements under which Broadcom will design and make custom silicon for several generations of Apple products. This is not merely a one-time chip contract. It covers about six iPhone release cycles, as well as new generations of iPad, Apple Watch, and Mac devices that use Broadcom components. 

Central to the arrangement is Broadcom custom ASIC Apple engineering: application-specific integrated circuits built to Apple’s exact specifications rather than off-the-shelf parts. ASICs sacrifice general-purpose flexibility for efficiency gains that matter enormously in battery-constrained devices. A radio chip built specifically for the iPhone’s antenna layout and power budget will outperform a generic equivalent on both signal quality and energy draw, and that difference compounds across hundreds of millions of units sold each year. 

The iPhone RF and Connectivity Backbone 

Analysts covering the filing were quick to note the scope of components included. The agreement encompasses Broadcom Apple iPhone RF chip 2031 production, meaning radio-frequency components that manage cellular signal processing well into the next decade. It also covers Broadcom wireless LAN Bluetooth Apple chips, the connectivity silicon responsible for Wi-Fi and Bluetooth performance among the entire device lineup, from AirPods pairing speed to CarPlay streaming reliability. 

While this may not be as exciting as news about artificial intelligence chips, it is essential. Even the best smartphone processor cannot make up for a weak antenna system—a phone that drops calls is still a problem. Broadcom has spent nearly twenty years perfecting this area for Apple, and Monday’s filing shows that Apple still values Broadcom’s expertise through at least 2031. 

Why Apple Still Needs an Outside Supplier 

Apple’s push to make its own chips has been a major story in consumer tech for the past six years. The company switched Macs to Intel processors, created its own A-series and M-series chips, and recently launched its own C1 cellular modem to reduce reliance on Qualcomm. Because of this, some investors thought Broadcom’s role would shrink over time rather than be extended through the end of the decade. 

The filing suggests otherwise, at least for a specific category of components. Wireless RF and connectivity engineering sits at a different point on the difficulty curve than processor design. Apple has shown it can design a competitive CPU. Replicating Broadcom’s decades of RF patents, manufacturing relationships, and calibration expertise for global carrier certification is a separate, and arguably harder, problem. That gap is what makes Broadcom’s custom semiconductor Apple production so durable as a business line, even as Apple continues to internalize other parts of its supply chain. 

There is also a future angle to consider. Some analysts noticed that the deal could include more advanced products related to Apple’s on-device and cloud AI plans. Broadcom already works with other large tech companies in this area. This detail is important because it shows Broadcom could become a partner for Apple’s next-generation connected chips, not merely a supplier of older RF components. 

The Investor Angle: Locked-In Revenue Visibility 

For shareholders, the main question is clear: how much more predictable is Broadcom’s revenue now? Apple has typically accounted for about one-fifth of Broadcom’s annual net revenue, which sometimes made analysts nervous about relying on a single customer. Monday’s announcement turns that risk into a guaranteed revenue stream for the next five years. 

In other words, people searching for “Broadcom extends Apple chip partnership to 2031 SEC filing AVGO stock rises 4 percent explained” want to know if Broadcom’s earnings are stable. Now, Broadcom can count on a significant part of its revenue through 2031, which is rare in the unstable semiconductor industry. This doesn’t guarantee what the stock will do next, but it does remove a major source of uncertainty that has affected it over the past year. 

The deal also arrives at a moment when Broadcom’s broader business mix is shifting. The company has been expanding its custom AI accelerator work with hyperscale customers, including Alphabet and Meta, a segment that is growing far faster than the legacy connectivity chip segment. Locking in the Apple relationship provides Broadcom with a stable cash-flow base to fund its AI expansion without diverting capital from its core operations. For investors trying to map out “Broadcom Apple custom ASIC deal 2031 iPhone RF wireless LAN Bluetooth chip supply investor impact,” the relevant takeaway is that the Apple business now functions less like a swing factor and more like a financial anchor supporting Broadcom’s higher-growth ambitions elsewhere. 

What This Means for the Next iPhone Cycles 

According to the filing, every iPhone released from now until 2031 will use Broadcom’s RF and connectivity technology. This is a clear and measurable statement, giving supply-chain analysts a solid reference point for tracking Apple’s component choices in future products. It also gives Broadcom’s engineers something rare in the chip industry: a clear customer plan for about five years, which supports ongoing investment in new RF technology. 

Of course, there is still some competitive risk. Apple’s plans to make its own modems could reduce Broadcom’s role in cellular chips, even with this broader agreement. For now, though, Monday’s filing answers the main question about the companies’ partnership. Broadcom enters the second half of the decade with its biggest customer relationship officially extended, and the market’s quick reaction was clear approval.

Source: Apple extends chip deal with Broadcom till 2031 

Seoul, South Korea | Dateline: July 7, 2026 

A shortage of memory chips has done what no marketing campaign could: it has made a Korean semiconductor supplier into a name Wall Street now says in the same breath as Nvidia. This week, the SK Hynix Nasdaq listing $29 billion offering moves from filing to reality, with the SK Hynix ADR debut on July 10 set to be the largest first-time U.S. share sale ever by a foreign company. This isn’t just a typical capital raise. Backed by 17.79 million new shares and 45.45 trillion won in expected proceeds, the listing is a bet that demand for artificial intelligence memory is just getting started. 

Why This HBM Memory AI Chip IPO Matters to Wall Street 

Calling this an HBM memory AI chip IPO doesn’t capture the full story. SK Hynix isn’t a startup looking for attention. It’s the established supplier behind the high-bandwidth memory used in Nvidia’s GPUs and Google’s data centers. Its shares have jumped over 280% this year, raising its market value above $1 trillion. Until now, global fund managers could only buy its Seoul-listed shares in won, but the Nasdaq listing changes that immediately. 

According to its updated filing with the U.S. Securities and Exchange Commission, each common share will convert into 10 American Depositary Receipts, which will trade under the ticker SKHY. The indicative price is about 242,500 won per underlying share, compared to Tuesday’s close of 2.555 million won. This gives American investors their first direct access to a company that supplies both chipmakers and the large tech firms building AI infrastructure. Analysts at several major banks say the order books are unusually full for a deal this big, indicating that demand for AI memory stocks exceeds the available supply. 

SK Hynix Largest Foreign US IPO in History 

Financial journalism often uses big words, but in this case, the SK Hynix title for the largest foreign US IPO is accurate. At its top range, the $29.65 billion raise beats Alibaba’s $21.8 billion New York debut in 2014 and Saudi Aramco’s $25.6 billion offering in 2019. Only SpaceX’s private valuation events and its reported $85.7 billion raise have been larger in recent years. Unlike those, SK Hynix’s shares are publicly listed, so regular investors can buy shares directly rather than wait for a secondary market. 

The size of this listing is important for more than just bragging rights. A deal this big usually prompts index providers to consider adding the stock within a few quarters, and passive funds tied to Nasdaq-100 membership could drive further buying even after the initial sale. For a stock that’s already tripled this year, that’s a big deal. 

SK Hynix vs Micron Valuation: A Gap Investors Want Closed 

Right now, no topic is bigger on trading desks than the SK Hynix vs. Micron valuation debate. SK Hynix trades at a forward price-to-earnings ratio of about 6.2, while Micron is at roughly 7, even though SK Hynix has a bigger share of the high-margin HBM market. The company’s leaders say this discount is why they’re listing in the U.S., hoping that a wider investor base will help the market value the company more fairly, instead of applying the usual discount to Korean stocks. 

The company’s own 2026 net income guidance stresses the stakes. SK Hynix is projected to generate 221 trillion won in net income this year, up 415% from 2025, while revenue is forecast to climb toward 355 trillion won. Micron, for context, is expected to see its own net profit jump sharply in its current fiscal year, meaning the two companies are now racing on nearly parallel tracks. For investors weighing “SK Hynix ADR vs Micron MU which AI memory stock is better investment July 2026,” the honest answer is that neither company wins outright; SK Hynix offers dominant HBM share and a valuation discount, while Micron offers longer U.S. trading history and diversified DRAM and NAND exposure. 

SK Hynix HBM 60 Percent Market Share Anchors the Bull Case 

Strip away the listing mechanics, and the underlying business case rests on one figure: SK Hynix’s HBM 60 percent market share, a position confirmed by Counterpoint Research and repeatedly reinforced by industry analysts tracking the AI memory supply chain. High-bandwidth memory has become the bottleneck component in AI server production, with 2026 capacity effectively sold out across the industry and shortages already forecast to extend into 2027. Samsung Electronics and SK Hynix together account for more than 40% of South Korea’s semiconductor exports, but it is SK Hynix’s early and aggressive specialization in HBM that has allowed it to command both the largest share and the best manufacturing margins in the category. 

SK Hynix’s dominance didn’t happen by chance. The company started working with Nvidia’s engineers to develop HBM specifications before its competitors did. This move seemed risky in 2023 when memory prices were low, but now it looks smart as demand has outpaced supply across the industry. 

SK Hynix Yongin Cluster Plant Anchors the Capital Plan 

The proceeds from this offering are allocated to specific projects, which makes this raise different from a typical equity sale. The SK Hynix Yongin Cluster plant will get about 31 trillion won, or $20.2 billion, to build its first fabrication line, with the larger campus expected to open in 2027. Another 19 trillion won will go to the P&T7 advanced packaging facility in Cheongju, and 12 trillion won is reserved for extreme ultraviolet lithography equipment needed for next-gen chips. The company is also building its first U.S. manufacturing site, a $4 billion packaging facility in Indiana, giving it a local presence as U.S. leaders push for more domestic chip production. 

For readers searching for the full picture, this is effectively the “SK Hynix launches $29 billion Nasdaq ADR listing July 2026 largest foreign US IPO explained” story in one sentence: a dominant HBM supplier is converting a historic valuation run into concrete, already-budgeted factory capacity, betting that AI memory demand will still be climbing when the Yongin fab opens its doors. 

What Comes Next for Investors 

The final price, share count, and trading date still depend on SEC review and the bookbuilding process, and SK Hynix has warned that the July 10 date could change. What remains the same is the bigger picture: the memory market, which used to swing between boom and bust, is now seen as part of a long-term AI buildout. Whether this view holds up during the next chip downturn is the question every SKHY buyer answers when they invest. For now, most of Wall Street seems ready to take that risk.

Source: SK Hynix seeks access to AI investors in $29 billion U.S. listing 

In light of the increased practicality of local AI workflows, picking the proper AI laptops are becoming prominent. Should you be planning on running models in Ollama, LM Studio, or even a laptop that serves as an offline ChatGPT-like service, your choice will depend on the memory, graphics processing capabilities, and sustained performance, and not on fancy terminology. In 2026, the best computer for a local LLM laptop solution will not be the most luxurious ultrabook, but the one that has sufficient VRAM and unified memory capacity. 
 

The problem with the classification is that all AI PCs are not equal to run local inference. Some of the Copilot computers may be designed for assistant functions on device, but running LLM tasks requires good GPU capabilities or huge unified memory spaces. That is why buyers looking for a true AI developer laptop or AI workstation laptop should evaluate hardware for LLM tasks first and branding second. 

 
What Matters Most 
When it comes to local LLMs, the most important elements include RAM, VRAM, and storage speeds. As the Copilot+ laptops and AI systems indicate, these laptops and systems come as devices that prioritize on-device abilities. However, local-LLMs note that running any practical model on the device requires lots of memory and good GPUs. In this way, it is better to get an RTX AI laptop with not less than 12-16 GB of VRAM instead of the light laptop with strong NPU but low graphics memory. 
 
It is necessary to mention Apple laptops as well because of the unified memory that is helpful in running bigger models. Therefore, many creators use the idea of getting the MacBook Pro-like laptop LM Studio or laptops for Ollama workflow due to high memory ceilings and silence. At the same time, in the case of the Windows laptop, the best combination is RTX laptop with 32-64 GB RAM and fast SSDs. 

Best Picks For 2026 

1.MacBook Pro with high unified memory: 
If you want the largest possible device and want something reliable for regular usage, a MacBook Pro with 36 GB, 64 GB, or more unified memory is among the best AI laptops for inference on your computer. This is because it is one of the best laptops in general, and the local-LLM aspect makes it even more suitable due to its high memory. For creators who want a quiet, portable laptop for LM Studio, this is often the smoothest experience. 
 
Such a device will suit well those who want a top-tier AI developer laptop with the capability to code, test and experiment on models without being disturbed by fan noise. It is also a good option for those who use macOS tools and need battery life in addition to their AI computing needs. The downside is price since some high memory devices are more expensive than RTX laptops. 
 
2.ASUS ProArt PX13 style Copilot+ Creator Laptop : 
Asus ProArt PX13 as a great Copilot+ creator device, making it an attractive Copilot+ PC for those looking for portability and AI functionalities in one product. Even though this laptop might not be the most powerful local-LLM beast available, it provides a balanced profile for those who need to have an AI PC capable of doing light local model work. This is the perfect mix for many users. 

For those whose main focus is flexibility for working with laptops for ChatGPT, writing, producing content, and having AI help right from their device, this type of computer is a good fit. This computer isn’t the best for large 70B-class models but will do well for everyday AI tasks. This makes it ideal for those who would like to have one laptop for all their work and experiments. 
 
3.RTX 4070/4080 gaming laptops  
In the context of the Windows OS, a high-end gaming laptop is almost always the best value category of RTX AI laptops available for local LLMs. As covered in the AI-oriented segment, the most powerful laptops are increasingly combining the power of creators and gaming with AI capabilities. Such laptops always have more powerful GPUs than lightweight productivity laptops, which goes a long way in helping local models. 

With an RTX laptop, you get a dedicated laptop for Ollama, giving you the necessary GPU power required by inference engines. This laptop makes sense as an AI workstation laptop for those who need CUDA compatibility and the ability to multitask. For a safe recommendation on Windows, this is usually where value starts improving. 
 

4. Ultra-premium RTX 50-series laptops 
It looks like the new breed of high-end RTX laptops is going to become the most promising Windows device for local AI development in 2026.The trend toward AI-capable laptops powered by Nvidia hardware and the importance of its agentic-AI approach can hardly be overstated. Such devices will be the best choice for people who want to have the most future-proof AI workstation laptop for programming and testing. 

These devices are particularly relevant for people who are looking for the best AI developer laptop and willing to spend a little extra on such a solution. Equipped with more VRAM, advanced cooling solutions, and more modern GPUs, they make some of the best Windows options for a local LLM laptop in 2026. 
 
5.Copilot+ ultraportables for light local AI 
Copilot+ laptops deserve special attention due to the integration of AI PC into Windows OS, which becomes evident from the Copilot+ laptops are one of the most accessible ways to get into the AI-powered for taking meeting notes, generating summaries, using assistants, and performing other productivity tasks. They are also appealing as an everyday laptop for ChatGPT-style workflows when cloud access is acceptable. They are also appealing as an everyday laptop for ChatGPT-style workflows when cloud access is acceptable. 

At the same time, they are probably not the right choice for executing models locally in case your primary concern is doing it in a powerful way. If you need to execute LLMs on a machine, Copilot+ laptops are likely going to be inferior to RTX-based machines with high VRAM and MacBook laptops with sufficient memory. 
 
AI laptops by use case 

Laptop type Best for Why it fits local LLMs Ideal keywords 
MacBook Pro with high unified memory Creators, developers, quiet work Large unified memory helps run bigger models smoothly AI laptops, laptop for LM Studio, laptop for Ollama 
RTX 4070/4080 gaming laptop Windows users, heavy inference Strong GPU and VRAM improve local model performance RTX AI laptop, AI developer laptop, AI workstation laptop 
Ultra-premium RTX 50-series laptop Power users, serious AI workflows Best long-term performance, cooling, and VRAM headroom AI workstation laptop, local LLM laptop 
Copilot+ ultraportable Office work, light AI tasks Good for on-device productivity, not heavy local models Copilot+ PC, AI PC, laptop for ChatGPT 
ASUS ProArt-style creator laptop Designers, hybrid creators Balanced AI features with portability Copilot+ PC, AI PC, AI laptops 

 
Buying factors for local LLMs 

Buying factor What to look for Why it matters Best fit 
RAM 32GB minimum, 64GB preferred Helps keep larger models and apps running together local LLM laptop, AI developer laptop 
VRAM 12GB to 16GB or more Critical for GPU-accelerated inference RTX AI laptop, AI workstation laptop 
Storage Fast NVMe SSD, 1TB or more Reduces loading delays for models and datasets laptop for Ollama, laptop for LM Studio 
Cooling Strong thermal design Prevents throttling during long AI sessions AI PC, AI laptops 
Battery life Good endurance for mobile use Important for creators and students on the move Copilot+ PC, laptop for ChatGPT 
Software support CUDA, macOS tooling, or NPU features Improves compatibility with AI apps AI developer laptop, AI PC 

Buying Guidance 
It is always best to select a computer that aligns with your workload. For light on-device assistance, you should settle for a Copilot+ PC or thin and light AI PC. However, if your goal is to use local models extensively, an RTX AI laptop and MacBook Pro class machines are recommended. 

For most users, 32GB RAM would be sufficient, but 64GB would be better for those who like experimenting or have several tools running at once. The best laptop for Ollama and laptop for LM Studio would require prioritizing memory over cooling and GPU class. Additionally, if your job requires coding, deployment, and testing, an AI developer laptop or AI workstation laptop would be a good choice. 
 
 
To conclude, The best AI laptops in 2026 are the ones that match real local-LLM needs instead of marketing buzz. For many users, that means choosing between a high-memory MacBook Pro, an RTX-powered Windows machine, or a balanced Copilot+ PC for lighter AI use. If you want the strongest local performance, focus on VRAM, unified memory, and thermals rather than NPU slogans. 


FAQS 

1. What are the best AI laptops for running local LLMs in 2026? 

The best AI laptops combine high memory (32–64GB), strong GPU or unified memory, and good cooling for smooth local LLM performance. 

2.Which AI laptops are ideal as a local LLM laptop for Ollama and LM Studio? 

High-memory MacBook Pros and RTX 4070/4080/50-series Windows laptops work best as a local LLM laptop for Ollama and LM Studio. 

3.Are Copilot+ PCs and AI PCs good for heavy local AI work? 

Copilot+ PCs and most AI PCs are great for productivity and light AI, but they’re usually not powerful enough as a dedicated local LLM laptop. 

4.What makes a laptop a good laptop for ChatGPT-style offline use? 

A good laptop for ChatGPT-style offline use needs fast RAM, solid storage, and an efficient CPU to keep token generation responsive. 

Source 
The best AI laptops in 2026, tested by experts | Tom’s Guide 
The Best Copilot+ Laptops We’ve Tested for 2026 | PCMag