Seattle, Washington.  

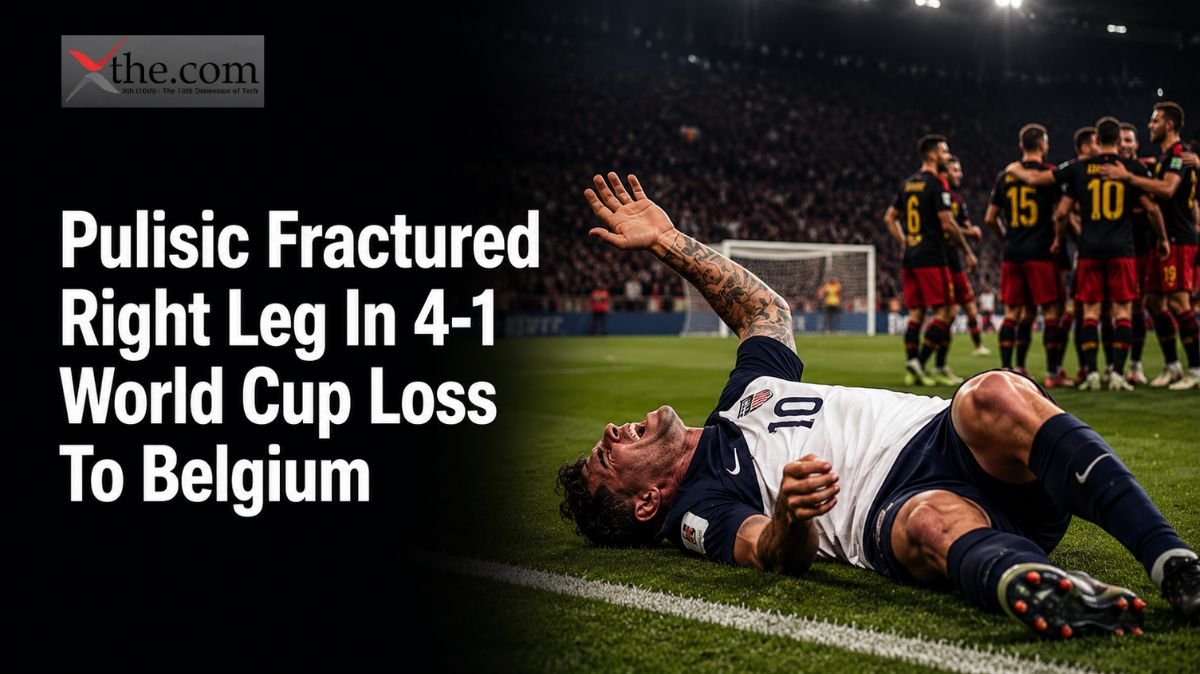
Thirty-three career goals, zero at the tournament that mattered most. That is the cruel arithmetic Christian Pulisic carries out of Seattle this week, and it is now a footnote to a far more serious story: Pulisic fractured leg in the USA 4-1 Belgium Round of 16 collapse, and the recovery clock is already running against AC Milan’s Serie A calendar. 

On Thursday, the U.S. Soccer Federation confirmed what television replays had already hinted at three days earlier. Pulisic’s microfracture tibia-fibula damage in his right leg occurred during the second half of Monday’s match. The injury is serious enough to end his tournament and will require weeks of structured rehab before he can return to full training. As the team tries to understand how such a talented and well-funded roster exited the knockout stage so decisively, this injury turns a football failure into a business and health issue. It has real consequences for a European club, a domestic broadcaster, and a national federation now preparing for its next cycle lacking its most famous player. 

What Happened in the 52nd Minute 

The play happened quickly. Pulisic moved toward the box and took a shot, but his leg hit Belgium captain Youri Tielemans as he kicked the ball. He stayed on his feet and kept playing but was clearly limping until U.S. head coach Mauricio Pochettino decided to take him out. Sebastian Berhalter came on in the 59th minute, and the match continued with the U.S. struggling both in defense and attack. 

By full time, the USA Belgium World Cup 2026 scoreline read 4-1, a result that ended the Americans’ run in the Round of 16 and triggered immediate scrutiny of team fitness management, tactical selection, and the physical strain of a compressed group-stage schedule. Pulisic had already entered the match fatigued from an earlier calf injury sustained in the opening group game against Paraguay, a detail that now reads less like bad luck and more like a pattern worth reviewing. 

The Diagnosis Behind the Headline 

Two days elapsed before the public understood the severity of what had happened on the pitch. An X-ray and MRI performed Tuesday confirmed that Pulisic had a microfracture of the tibia-fibula, alongside a bone bruise in his right leg. U.S. Soccer’s statement on Thursday made it clear: even if the team had advanced, the injury would have kept him out of any remaining matches. His tournament ended the moment his leg hit Tielemans’ shin. 

Microfractures do not usually get as much attention as torn ligaments, but doctors treat them just as carefully. If improperly managed, a tibia-fibula microfracture can turn into a full stress fracture with repeated play. This risk is why U.S. Soccer and AC Milan quickly agreed on a joint recovery plan, instead of relying on informal coordination between club and country, which has caused problems between federations and European clubs in the past. 

Why the AC Milan Timeline Matters 

This is where the story shifts from a soccer injury to a genuine business calendar problem. Pulisic injury AC Milan planning now centers on one hard date: Torino, August 23, the opening fixture of Milan’s Serie A season. Pulisic AC Milan recovery August protocols will determine whether the club’s most productive attacking option in recent seasons is fit to start, come off the bench, or watch from the sideline as his fourth season in Italy begins. 

Milan’s technical staff is guardedly optimistic that Pulisic can start training before the season opener. However, being able to train and being ready for a match are not the same. Clubs have learned the hard way that hurrying players back from bone injuries can lead to bigger problems. If a microfracture worsens during the season, it can mean more missed games than if the team had just waited an extra week during the preseason. 

For Milan, the financial risk is real but not overwhelming. Pulisic is still under contract, and the August opener is just one of the thirty-eight league matches. The bigger concern is maintaining momentum: a winger like Pulisic needs to be sharp, and if his return is spreading over September rather than building up during preseason, his impact could be reduced. 

A Program-Level Reckoning 

Zoom out from the individual injury and a harder question emerges for U.S. Soccer. The USMNT’s 2026 World Cup exit comes after years of investment in player development and sports science and hopes built around Pulisic. He came into the tournament as the team’s all-time leading scorer with 33 goals, so his scoreless run through five matches—ending with a serious leg injury instead of a highlight—was especially disappointing for fans who expected more. 

Now, federation officials must review familiar questions: Did the medical staff manage player fatigue well over five matches? Should Pulisic’s calf injury from the Paraguay game have led to more careful minutes later on? Did the team have enough other scorers to make up for Pulisic’s limited play? These questions are tough, and they will not be answered before the next World Cup cycle starts. 

What Recovery Actually Looks Like 

Recovering from this kind of bone injury usually happens in stages: first, a rest period to let the microfracture heal; then gradually adding weight-bearing exercises; followed by non-contact training; and finally full-contact and match practice. Fitting all of this into the six weeks before Milan’s Serie A opener is possible, but it will be a challenge. Pulisic will need to regain match fitness and heal his bone, not just pass a single medical test. 

The phrase now trending in sports coverage—“Christian Pulisic fractured right leg USA 4-1 Belgium World Cup Round of 16 Seattle July 2026”—captures a moment that will probably shape how this tournament is remembered in American soccer, no matter what happens next. Belgium, now ranked No. 3, will play Spain in the quarterfinals, drawing plenty of attention, while Pulisic starts the quieter, less visible process of recovery. 

No matter how this World Cup cycle is judged, the main story now shifts to a training room in Italy instead of a stadium in Seattle. The phrase “Pulisic microfracture tibia fibula recovery timeline AC Milan Serie A return August 2026” will likely be a top soccer search for the rest of the summer. How closely Pulisic’s return matches that timeline will reflect not only his own resilience but also the strength of American soccer’s medical system. Milan’s opener against Torino now means more than just three points.

Source: U.S. star Christian Pulisic suffered microfracture vs. Belgium 
New York, New York | July 8, 2026 

Oil jumped more than 5% before lunch. Gold futures pushed through $4,130. And somewhere on a trading desk in Midtown, a portfolio manager who had spent the morning defending his 60/40 allocation quietly started buying bullion. That is the story of Wednesday’s session, and it is worth understanding in detail, because the gold price $4130 July 2026 print is not a standalone data point. It is a signal about how fragile the peace in the Middle East has become, and about how little protection traditional portfolios now offer when that fragility turns into headlines. 

President Trump’s announcement at the NATO summit in Ankara that the ceasefire with Iran was “over” did more than unsettle diplomats. It triggered a gold breaks $4130 Iran ceasefire collapse move that traders had been preparing for since the first reports of attacks on Iranian tankers in the Strait of Hormuz. Within hours, futures for August delivery touched levels not seen in nearly a week, including a broader gold record July 8, 2026 session, where gold, oil, and volatility indexes all moved higher together a pattern that is rare on normal trading days. 

Gold Safe Haven Iran: Why the Metal Moved First 

Markets often react ahead of global disputes, and Wednesday was a clear example. As soon as news circulated that the United States had revoked Iran’s oil-sale waiver after attacks on shipping in the Strait of Hormuz, the gold safe-haven Iran trade kicked in almost automatically. Institutional traders who had reduced their gold holdings during the short, uneasy ceasefire returned to the metal, using it as a stabilizer amid instability, just as they have in the past. 

What made Wednesday unusual was not that gold rallied. Gold rallying on Middle East tension is close to a market cliché at this point. What made it notable was the gold rally and oil surge simultaneous pattern bullion and crude climbing together rather than trading as substitutes. In calmer markets, a spike in oil frequently pressures gold because it raises inflation expectations and, with them, the odds of higher interest rates, which increase the opportunity cost of holding a non-yielding asset. On Wednesday, that relationship briefly inverted. Both assets moved as if investors weren’t debating the mechanics of inflation at all. They were pricing outright conflict risk. 

Safe Haven Assets July 8: Reading the Signal Correctly 

Any trader with a decade on the desk will tell you that a single-asset rally is easy to dismiss as noise. A coordinated move across safe-haven assets July 8 gold, oil, and a firming dollar all advancing while equities wobbled is much harder to explain away. It suggests that professional capital, not retail momentum chasers, was doing the buying. Retail flows tend to concentrate in one trade at a time. Institutional risk managers, by contrast, hedge across several uncorrelated instruments simultaneously, which is exactly the pattern that showed up in Wednesday’s tape. 

That distinction matters for anyone trying to decide whether this move has staying power. Geopolitical spikes driven by speculative momentum tend to fade within days. Spikes built on genuine institutional repositioning tend to persist until the underlying risk resolves, one way or another. The “Gold breaks above $4130 July 8 2026 investors flee to safety Iran ceasefire collapse explained” story that circulated on trading desk chat channels Wednesday afternoon captured this second dynamic well: professional money was not chasing a headline. It was hedging a war that had, in the span of forty-eight hours, gone from de-escalating to reigniting. 

Morgan Stanley Gold Bullish 2026: The Institutional Case 

Wednesday’s price action did not occur in a vacuum. It landed atop an already constructive institutional stance toward the metal. Morgan Stanley has kept bullion near the top of its preferred commodity list for much of 2026, citing central bank accumulation, currency debasement concerns, and gold’s historical tendency to outperform during periods when real interest rates compress. The Morgan Stanley gold bullish 2026 thesis was built primarily on monetary policy and structural demand from central banks in China, India, and Turkey, rather than on any single geopolitical flashpoint. Wednesday’s Iran escalation layered a second, more immediate catalyst on top of that existing bullish case, giving portfolio managers who were already inclined toward gold a fresh reason to add to positions rather than trim them. 

The Portfolio Mathematics Nobody Refuses to Explain 

This is the tough reality for most retail investors with a standard 60/40 stock-bond portfolio. On Wednesday, stocks dropped, oil prices jumped, and bond yields rose as the chance of a rate hike for September climbed to 67%. Both stocks and bonds lost value at the same time. Stocks fell because higher energy costs hurt profits and increased the risk of recession. Bonds fell as rising oil prices rekindled inflation fears, making the Federal Reserve more likely to raise rates rather than cut them, as many had expected. When both stocks and bonds decline together, diversification stops working, and a portfolio designed for normal downturns suddenly becomes vulnerable on all sides. 

In situations like this, three types of investments usually hold up: gold, energy stocks, and short-term cash instruments. Gold gains from the flight to safety. Energy stocks rise as oil prices rise, even if the rest of the market falters. Short-term cash and Treasury bills help by not losing value while other, higher-risk assets are being repriced. These ideas are not new, but it is rare to need all three at once. Wednesday’s session made that need very clear. 

What This Means for Portfolio Protection 

The “Gold safe haven surge July 2026 oil spike simultaneously what it means for portfolio protection” question is the one every advisor fielded calls about this week. The honest answer is that a modest allocation to gold, in the 5% to 15% range depending on risk tolerance, serves less as a return driver and more as insurance during exactly the kind of dual-asset sell-off Wednesday produced. Investors who dismissed bullion as an artifact during the low-volatility years of the early 2020s are now recalculating, not because gold suddenly became a growth asset, but because the correlation assumptions underlying the traditional 60/40 model broke down in real time. 

None of this means the rally will last. Iran’s Revolutionary Guards have already threatened to retaliate against American targets in the Gulf, and the mood between Washington and Tehran has swung back and forth between tension and calm several times recently. Wednesday did not mark a permanent change in the markets, but it acted as a reminder of how quickly things can shift. The best-prepared investors for the next crisis will not be those who guessed gold’s direction, but those who already built portfolios that can handle a day when stocks, bonds, and stability all vanish at once. 

Source: https://finance.biggo.com/news/aee7fc6b-b255-4135-97cb-de2b4b648165

Houston, Texas | July 8, 2026 

On Wednesday, most sectors saw losses, but energy was the exception. The Dow dropped over 500 points, and cruise lines and airlines struggled, but energy stocks had the kind of day traders hope for. Energy stocks surge July 8, 2026, as President Trump announced the fragile ceasefire with Iran was “over.” Crude oil prices saw their biggest single-day jump since the conflict began. West Texas Intermediate reached $74.55 a barrel during the day, a price not seen since the earlier Iran conflict. The gains for ConocoPhillips Chevron gain that followed were immediate, broad, and unmistakably tied to the geopolitical news. 

This is not a subtle rotation. It is a full-throated flight into oil stocks, Iran exposure, and the numbers tell the story with unusual clarity: Energy stocks surge July 8, 2026, ConocoPhillips, Chevron, Marathon lead on Iran ceasefire collapse, and the size of the individual moves explains why. 

What Moved and Why 

Marathon Petroleum was the star. The refiner surged 5% in Wednesday’s session, the sharpest move among the majors and a signal that traders were pricing in wider crack spreads as much as higher crude. That Marathon Petroleum 5 percent gain on July 8 shows a specific mechanic worth understanding: refiners profit from the spread between crude input costs and refined product prices, and a sudden supply shock tends to widen that spread before it narrows. 

ConocoPhillips rose 2%, consistent with its role as a pure exploration and production company. Unlike bigger, integrated companies, ConocoPhillips does not have a refining business to cushion price swings, so its profits closely follow crude prices. Chevron gained about 1%. While smaller, this is still notable for a company whose large operations in both production and refining usually make its stock less volatile in a single day. 

The XLE ETF Iran oil gain captured the sector-wide lift in a single number: the Energy Select Sector SPDR Fund rose about 3% in afternoon trading, beating every other S&P 500 sector by a large margin. While the overall market dropped, XLE stood out as the clear winner. 

Refiners and Majors Both Caught the Bid 

The rally was not confined to the two headline names. Valero and ExxonMobil’s July 8 trading told the same story from different angles. ExxonMobil, the largest of the integrated majors, rose as crude climbed, benefiting from its blended exposure to both production and refining. Valero, a pure-play refiner, moved on the same crack-spread logic that lifted Marathon Petroleum. Together, the two names illustrate how the rally spanned the entire energy value chain rather than concentrating on a single business model. 

The reason for the rally was clear. President Trump’s announcement followed new U.S. strikes on Iran, which were in response to attacks on commercial ships in the Strait of Hormuz. Iran reportedly hit back at U.S. positions, quickly ending weeks of calm in the markets. Analysts said this brought back the geopolitical risk premium that had diminished during the ceasefire. Even though traffic through the Strait had started again, it never returned to normal levels. The U.S. Treasury’s move to end Iran’s export waiver also reduced expectations of ample global oil supply. 

The Investor Playbook 

For investors wondering which oil energy stocks to buy as Iran ceasefire collapses (July 8, 2026 investor playbook),the answer falls into three main groups. These differences are more important than just knowing that oil prices are up. 

Integrated majors like Chevron and ExxonMobil give investors the most balanced exposure. Their refining businesses help offset oil price swings, making them a good option for those who want energy stocks without taking big risks on oil’s direction. Pure exploration and production companies, such as ConocoPhillips, react more strongly to changes in oil prices. When oil goes up, these stocks usually rise faster than the majors, but they also fall harder when oil drops. Refiners like Marathon Petroleum and Valero are a different kind of investment. Their profits depend on the gap between crude costs and refined product prices, not just the price of oil itself. That’s why Marathon’s 5% jump was bigger than the rise in crude prices on Wednesday. 

LNG exporters round out the picture. Reduced Iranian supply competition and a tighter global gas market have made U.S. liquefied natural gas terminals an increasingly attractive hedge against the same geostrategic instability driving the oil trade. Investors building a position around this energy sector rally-ceasefire-collapse dynamic would do well to treat these four categories as distinct instruments rather than as a single undifferentiated “energy” bet. 

Who Loses When Oil Spikes 

The other side of Wednesday’s rally was just as telling. Airlines were hit hardest because jet fuel is a major expense, and their profits shrink quickly when oil prices rise. Consumer goods companies also felt the impact through higher shipping costs, and retailers with big delivery networks faced the same problem. Home Depot and McDonald’s both saw their shares fall as investors expected slimmer profits amid weaker consumer spending. 

There’s another group that could be affected: technology companies that rely on cheap, plentiful power for their AI data centers. Over the past two years, most AI infrastructure has been built on the idea that energy would stay affordable. If oil and energy prices stay high, these companies will have to rethink those assumptions. Data center operators who are committed to long-term expansion can’t easily pass on higher electricity costs as refiners do with crude, so this challenge could last longer. 

What Comes Next 

The Wednesday session was not so much about a single day’s trading as about a reset in how markets price Middle East risk. Weeks of assumed de-escalation had compressed the geopolitical premium out of crude prices, and Wednesday’s move showed how quickly that premium can be rebuilt when facts on the ground change. Whether Marathon Petroleum, ConocoPhillips, and Chevron hold their gains will depend less on Wednesday’s headlines than on what happens in the Strait of Hormuz over the coming days, and on whether Tuesday’s strikes prove to be an isolated retaliation or the opening move in a longer escalation. Investors positioning around energy stocks surge July 8 2026 conditions should treat this as a live, fast-moving situation rather than a settled trade, with the spread between refiners and pure producers likely to remain the more interesting story than the direction of crude itself.

Source: https://finance.yahoo.com/energy/articles/conocophillips-cop-among-10-most-130739936.html

Redmond, Washington July 9, 2026 

One in five Xbox employees is losing their job this fiscal year. That single statistic tells you more about the state of console gaming than any earnings call transcript could. On Monday, Microsoft confirmed the Microsoft Xbox spinoff gaming studios plan, cutting 4,800 positions company-wide while pushing four established development houses out of its corporate umbrella entirely. The Microsoft gaming AI restructure 2026 is not a routine belt-tightening exercise. It is a structural admission that the console business, as Microsoft built it through nearly a decade of acquisitions, no longer fits the economics the company wants to run. 

The numbers motivating this decision are clear. Xbox Chief Executive Asha Sharma told staff in a memo that the division loses 64 cents for every dollar it spends, and that its profit margins are three to ten times lower than those of similar businesses. This is not a small issue. Sharma’s memo made it clear that small changes would not be enough to fix the problem. 

The Four Studios Leaving the Nest 

The Xbox four studios spun off are Compulsion Games, Double Fine Productions, Ninja Theory, and Undead Labs. Compulsion Games and Double Fine will become independent companies, while Ninja Theory and Undead Labs will move to new outside management. Each studio has its own creative style, and Microsoft united them all during its wave of acquisitions, which culminated in the $69 billion purchase of Activision Blizzard. 

Double Fine, led by Tim Schafer, is known for games like Psychonauts and Brutal Legend, which are admired for their stories but not for huge sales. Compulsion Games, based in Montreal and known for We Happy Few and South of Midnight, is similar: creative and mid-budget, but hard to justify at a company now spending $190 billion a year on AI and data centers. Ninja Theory, which made Hellblade: Senua’s Sacrifice, and Undead Labs, creator of State of Decay, complete the group. None of these studios generate the billion-dollar annual revenue of franchises like Halo, Call of Duty, or Minecraft, which is why they were chosen for the spinoff. 

Why These Studios, Specifically 

The internal logic is not subtle. Microsoft is narrowing its first-party lineup to the highest-value intellectual property it controls and shedding the mid-tier studios whose games, however well reviewed, do not move the revenue needle at the scale a trillion-dollar company now demands. The Xbox gaming division restructure 2026 effectively draws a line between franchises that anchor Game Pass subscriber growth and the smaller, artistically distinct projects that made Xbox’s acquisition-era reputation but never scaled into system sellers. 

The Fifth Studio and the Broader Numbers 

Beyond the four confirmed spinoffs, Microsoft disclosed it is examining strategic options for an additional studio, a detail that has stoked speculation the company is not finished trimming its gaming portfolio. Combined with the layoffs, this has produced headlines referencing the Microsoft 4800 jobs Xbox fifth layoff figures, though it is worth noting that the fifth studio in question is still under review rather than confirmed for departure. Of the 4,800 total job cuts, roughly 1,600 take effect immediately within Xbox, with another 1,250 expected before the end of the fiscal year, bringing the division’s total reduction to about 3,200 positions, or roughly 20 percent of its headcount, over fiscal 2027. 

Amy Coleman, Microsoft’s chief people officer, framed the cuts in company-wide terms rather than singling out gaming. The Microsoft Amy Coleman layoff memo told employees that “our business is changing because the world around it is changing,” adding that the pace at which technology is built and deployed is transforming faster than at any point in her tenure at the company. Coleman was careful to note that jobs are not being directly replaced by artificial intelligence, even as she acknowledged the technology is changing how work gets done across the organization. 

AI’s Role in the New Studio Economics 

Microsoft has not published a detailed technical roadmap explaining exactly how Xbox gaming AI production tools will let smaller, independent studios operate without the corporate overhead they carried under Redmond. But the strategic direction is consistent with what Microsoft has said publicly about AI’s role in software development broadly: shrinking the headcount required to ship a given amount of production-quality work. For a studio like Double Fine, now operating outside Microsoft’s balance sheet, the question is whether AI-assisted tooling for asset generation, code review, and quality testing can substitute for the larger teams that traditional AAA and mid-budget development once required. 

That question sits at the center of the Xbox gaming studios spinoff, Microsoft AI cost structure, gaming industry impact, 2026 debate now circulating among developers and analysts. If AI tooling genuinely allows a twenty-person team to produce what once required eighty people, independence from Microsoft’s overhead becomes financially viable rather than a slow wind-down. If it doesn’t, these newly independent studios face the same funding and distribution pressures that have driven waves of layoffs across the games industry since the pandemic-era hiring boom unwound. 

What It Means for Studio Employees 

For the roughly 350 employees directly affected by the studio departures, the immediate future is unclear. Staff who move with Compulsion Games and Double Fine into independence, or to new owners at Ninja Theory and Undead Labs, will lose Microsoft’s benefits because they will no longer be Microsoft employees. Projects already in progress are expected to continue, but the studios will need to find new partners or handle publishing, marketing, and platform support on their own. 

An Industry-Wide Signal 

The Microsoft Xbox spins off four gaming studios alongside 4800 job cuts. AI restructuring 2026 details are being read closely by rival publishers, many of whom face the same margin pressure Sharma described in her memo. Microsoft’s stock has fallen nearly 23 percent through the first half of 2026, its worst first-half performance since 2022, as investors evaluate whether the company’s massive AI infrastructure spending will pay off before it erodes cash flow from mature businesses like gaming and Windows licensing. Xbox’s overhaul, following a 9,000-person layoff a year earlier and a 15,000-job reduction across 2025, suggests Microsoft views gaming less as a growth engine and more as a portfolio to be optimized for margin. 

The bigger issue goes beyond Microsoft’s headquarters. If AI tools can really help smaller teams make successful games, mid-sized studios might not need a big company’s support to survive or they might not survive at all. Either way, the trend of publishers buying up smaller, niche studios just to fill out subscription services seems to be ending. What comes next will shape both the future of game development jobs and Microsoft’s plans for AI. 

Source: https://businesschief.com/news/microsoft-and-xbox-cut-4-800-roles-amid-ai-integration-push

San Diego, California — July 9, 2026 

A San Diego biotech that closed Monday trading at $42.03 a share woke up worth nearly twice that. Crinetics stock doubles Vertex buyout premium after Vertex Pharmaceuticals agreed to pay $85 per share in cash, and the market reacted the way markets do when a 100 percent premium lands without warning: it stopped pricing in caution and started pricing in certainty. The CRNX 98 percent gain overnight ranks among the sharpest single-day biotech moves of 2026, and it did not stem from a trial readout or an FDA decision. It happened because Vertex Pharmaceuticals decided Crinetics was worth more inside its portfolio than outside it. 

The Vertex Pharmaceuticals-Crinetics deal, announced Monday and expected to close in the third quarter, values Crinetics at about $10 billion in total equity, or around $8.8 billion after accounting for the cash on its balance sheet. This is the largest acquisition in Vertex’s history, surpassing anything the Boston-based company has done in its thirty years of focusing on cystic fibrosis. Vertex’s previous biggest deal was the $4.4 billion purchase of Alpine Immune Sciences in 2024, which now seems small by comparison. For a company that rarely makes such large moves, the amount spent is as significant as the per-share price. Both companies’ boards approved the deal unanimously, and analysts remarked that the quick approval suggests Vertex had been considering Crinetics for some time before the announcement. 

Why Vertex Paid Double 

Wall Street does not offer 100 percent premiums for sentimental reasons. The Vertex VRTX $10 billion Crinetics acquisition buys two things Vertex did not have: a commercial rare-disease product already generating revenue, and a late-stage pipeline asset with the potential to become a blockbuster. Crinetics’ main drug, Palsonify, is an oral pill approved by the FDA last September to treat acromegaly, a disorder caused by too much growth hormone that affects about 20,000 diagnosed patients in the U.S.While this is a small group by industry standards, it is a profitable one, since rare-disease drugs without real generic competition can keep their pricing power for years. 

The Crinetics Pipeline Beyond Palsonify 

The Crinetics acromegaly rare-disease pipeline goes beyond a single approved drug. Vertex is also acquiring atumelnant, a Phase 3 candidate for congenital adrenal hyperplasia, a genetic disorder affecting the adrenal glands. Early data suggests it could also help patients with Cushing syndrome. On Monday’s call, Vertex executives openly expressed their excitement, saying the atumelnant results are close to the best possible outcome for this type of treatment. Together, Vertex expects Palsonify and atumelnant could bring in over $5 billion in annual revenue at their peak. This potential, more than the purchase price alone, explains why Vertex was willing to pay double for a company that spent most of 2026 trading below its starting price. 

The Cystic Fibrosis Clock Is Ticking 

Every large acquisition has a defensive logic sitting underneath the offensive one, and Vertex’s is not subtle. Vertex cystic fibrosis diversification has been the company’s strategic preoccupation for several years, because Trikafta and its related cystic fibrosis therapies still account for the overwhelming majority of Vertex’s revenue. First-quarter cystic fibrosis sales rose 7 percent year over year to roughly $1.78 billion, proof the franchise is still healthy. But healthy is not the same as permanent. Patent protection does not last forever, and a company that generates the bulk of its income from one disease category eventually has to answer the question investors have been asking for years: what happens after cystic fibrosis stops carrying the stock. 

Crinetics helps answer that concern. Its intellectual property lasts into the 2040s, giving Vertex a second, extended growth driver rather than just a short-term fix. Vertex plans to fund the deal with its own cash and $4.5 billion in bridge financing from Bank of America and Morgan Stanley. This approach lets Vertex keep extra resources available even after making its biggest purchase ever. With about $13 billion in cash and marketable securities at the end of the first quarter, and full-year revenue guidance close to $13 billion, Vertex can take on this debt without putting its finances at risk. 

A Biotech M&A Wave That Rewards Patience 

The Crinetics deal is not happening in isolation. It is the latest data point in a biotech M&A wave in 2026 that industry trackers now estimate could reach $140 billion to $160 billion in total deal value this year, with some predicting even more. The trend is clear: big pharmaceutical companies with record cash reserves and upcoming patent expirations are looking for mid-sized biotechs with proven, revenue-generating products instead of untested platforms. Interest rates are still too high for venture capital to be cheap, and much of the available money is going into artificial intelligence rather than clinical-stage biology. As a result, many well-run, commercially successful biotech companies are trading at prices that do not fully reflect the value of their pipelines. This is exactly the kind of environment that leads to buyouts like this one. 

Who Could Be Next 

If the reasoning behind the Vertex-Crinetics deal holds, the next likely targets will have similar traits: a single approved or nearly approved rare-disease product, a founder-led management team, and a market value small enough for a large, cash-rich company to buy without facing major antitrust issues. Analysts have mentioned companies like Ultragenyx Pharmaceutical, Travere Therapeutics, and Rocket Pharmaceuticals as fitting this profile, each with commercial or late-stage rare-disease programs and a market cap well below what a big pharma could pay in cash. The wider biotech index has risen about 32 percent during the same period that Crinetics shares were falling before Monday, a gap that often draws the attention of corporate development teams looking for overlooked companies. None of these are confirmed targets, but searching for “Crinetics CRNX stock doubles overnight Vertex Pharmaceuticals $10 billion acquisition offer 2026”has become a stand-in for a bigger investor question: which mid-cap biotech will be next? 

What the Deal Signals Going Forward 

For biotech investors looking to understand the story behind “Vertex Pharmaceuticals buys Crinetics $10 billion rare disease acromegaly biotech M&A explained,” the lesson goes beyond just one company’s lucky day. Big pharmaceutical companies have money to spend, patent expirations are approaching, and rare-disease biotechs with commercial products are now seen as good deals instead of risky bets. Crinetics shareholders received their premium overnight. Other companies trading below the real value of their pipelines should be ready for acquisition offers soon. 

Source: https://finance.yahoo.com/markets/stocks/articles/why-crinetics-stock-doubled-vertex-030901005.html 

New York, New York | July 9, 2026 

Nvidia shares are hovering near their lowest point of the year, and the stock that once led every rally is now taking the brunt of market criticism. This contradiction is at the center of the latest Jim Cramer Nvidia stock July 2026commentary, delivered this week on CNBC’s “Squawk on the Street.” Cramer’s blunt verdict cuts against the prevailing mood on trading desks: Cramer said everything revolves Nvidia, he told viewers, even as the chipmaker limps through one of its worst stretches of the year. The remark landed as Nvidia shares dropped about 2% for the day, leaving the stock only slightly up for 2026 and trading at just under 19 times forward earnings, its lowest valuation since January. 

It is an odd moment for the company that built the AI trade. Nvidia has become, in Cramer’s words, the stock “everyone hates,” yet he insists the selling has run well ahead of the fundamentals. The Nvidia stock-lagging-2026 narrative has taken hold across trading floors for a specific reason: Nvidia’s own customers keep publicly complaining about what they pay for its chips while quietly building their own silicon. 

Why the Chip Giant Still Sets the Terms 

Cramer’s point is often overlooked in the daily rush of market news. Nvidia’s biggest customers, including Google, Amazon, and Tesla, have all complained about prices, but they still rely on Nvidia’s technology for their data centers. Alphabet and Amazon say their own chips can compete with Nvidia’s, but Cramer is openly skeptical of these claims. Broadcom, led by CEO Hock Tan, is seen as a real competitor that could take some market share. Still, according to Cramer, none of these moves have pushed Nvidia out of its central role in building AI infrastructure. Reuters also reported that China’s DeepSeek is now working on its own AI chips, which adds to the negative outlook. But Cramer keeps saying that doubting Nvidia’s importance is not the same as proving it’s no longer important. 

Some of the recent pressure on Nvidia stems from a SemiAnalysis report claiming manufacturing delays for Nvidia’s next-generation Kyber server system. The report suggests the launch could be pushed from 2027 to 2028. Nvidia directly denied this, saying its roadmap “remains intact.” Cramer saw this denial as a strong reason to buy the stock on the dip and told investors so on social media. He also offered another explanation for Nvidia’s weak performance: the stock might be a “source of funds,” meaning investors are selling it to raise cash for other opportunities, like the newly public SpaceX before it joins the Nasdaq 100. 

The Trade Has Rotated, Not Disappeared 

What makes this moment distinct is where the money has actually gone. On a recent Cramer Mad Money Nvidia AI infrastructure segment, the host laid out a framework that reframes the entire AI trade rather than simply defending one stock. Wall Street, he argued, is now rewarding the companies that supply the picks and shovels of artificial intelligence while punishing the hyperscalers footing the bill for that infrastructure. That is the essence of Wall Street rewarding AI suppliers not customers: Micron, Marvell, AMD, SanDisk, and Intel have posted some of the sector’s strongest gains this year, even as the so-called Magnificent Seven have shed roughly $2.3 trillion in combined market value over a single month. Micron’s gross margin has expanded from 39% to nearly 85% year over year as memory prices have, in Cramer’s phrase, gone through the roof. SanDisk has rallied more than eightfold year to date amid surging data center demand. Cramer named Intel his current favorite stock, citing CEO Lip-Bu Tan’s turnaround and disclosing that his Charitable Trust initiated a position in June, adding to it twice since. 

Nvidia still aligns with Cramer’s idea of a supplier that benefits from selling products in short supply and high demand. He argues that Nvidia’s weak performance this year is more about competition concerns than any real problems with its core business, and the numbers support his view. 

What the Next Product Cycle Actually Costs 

The strongest proof that Nvidia is still at the center of AI spending is found in its bill of materials, not its stock price. According to Morgan Stanley, the Nvidia VR200 NVL72 rack $7.8 million estimate for the Vera Rubin platform is estimated to cost $7.8 million, almost double the $4 million that hyperscalers paid for the previous GB300 generation. This increase isn’t mainly due to GPUs, though their prices have also risen Nvidia is expected to charge about $55,000 per Rubin GPU and around $5,000 per Vera CPU when sold in bulk to large buyers. 

Memory is where the real inflation shows up. Morgan Stanley estimates memory content per rack has surged to around $2 million, pushing memory’s share of the total bill of materials to roughly 25%, up from just 5% to 10% in the prior generation. That single data point explains why Micron and SanDisk have outperformed Nvidia this year: as the GPU’s share of total system cost falls from roughly 63% to 51%, memory suppliers gain a larger slice of every dollar hyperscalers spend building out AI capacity. First shipments of the new rack are scheduled for the third quarter of 2026, with volume production ramping in the fourth quarter, meaning the cost structure Cramer is describing will begin showing up in hyperscaler capital budgets within months, not years. 

Cramer’s Other Conviction Call: Power, Not Just Chips 

Cramer’s view goes beyond just semiconductors. On a recent Mad Money lightning round, a caller asked about GE Vernova, and Cramer did not hesitate. The Nvidia GE Vernova Cramer buy connection reflects his wider thesis that AI infrastructure spending flows well beyond chipmakers into the power and electrification companies that keep data centers running. Cramer said his Charitable Trust has “a very big position” in GE Vernova and repeated his buy rating, even though the stock is trading near record highs above $1,100.In the first quarter of 2026, GE Vernova reported $9.3 billion in revenue, up 16% from last year, with orders rising 71% to $18.3 billion and a backlog of $163 billion. The company’s management has since raised its full-year outlook, citing growing demand from both hyperscalers and utilities for reliable power. 

Taken together, Cramer’s commentary this week amounts to a Jim Cramer “everything revolves around Nvidia despite lagging stock” July 9 2026 analysis that reaches well beyond a single ticker. His more general claim is that Cramer Nvidia still central AI trade Wall Street rewarding suppliers not customers 2026 describes an entire market structure, one in which value has migrated toward the companies selling scarce components memory, networking silicon, and power generation rather than the household names spending hundreds of billions to build AI data centers. 

The Road Ahead 

None of this settles the short-term uncertainty around Nvidia’s stock. The company’s next earnings report will be the real test of whether manufacturing issues are impacting data center revenue and if the Kyber delay claims are more than just one report. What’s clearer is that demand for AI infrastructure stays strong. Hyperscalers are not slowing down their AI projects; they’re just shifting their spending more toward memory, power, and networking than they did last year. For investors comparing Cramer’s confidence to Nvidia’s lagging stock chart, the most important sign may be in the bill of materials, not the stock price: every rack still needs a GPU, and every data center still needs reliable power. 

Source: https://www.cnbc.com/2026/07/07/cramer-everything-still-revolves-around-nvidia-even-as-stock-lags.html?&qsearchterm=Cramer%20Says%20Everything%20Still%20Revolves%20Around%20Nvidia%20Despite%20Lagging%20Stock 

Beijing, China | July 9, 2026 

Twenty-nine million fake queries. Twenty-five thousand fraudulent accounts. One angry American AI lab. These numbers are now at the heart of a corporate split that few in the industry saw coming a year ago. Alibaba bans Anthropic AI products from all internal systems, ending a relationship that once made the Chinese e-commerce giant one of Anthropic’s biggest customers in Asia-Pacific. Internal notices and reports from outlets like the South China Morning Post and Reuters confirm the move, which is the most dramatic escalation so far in the deepening Alibaba Anthropic distillation row. 

The Alibaba Claude ban employees are presently navigating covers far more than just one coding tool. Employees have been told to remove all Anthropic products, including the Sonnet, Opus, and Fable models, and switch to Qoder, Alibaba’s own AI coding platform. Until recently, Claude Code was widely used across Alibaba’s engineering teams, so this change is both sudden and expensive. 

The Distillation Accusation That Started It 

Alibaba’s decision was triggered by a security researcher’s post on Reddit on June 30. The researcher found that versions of Claude Code released since April 2 could check a user’s time zone and proxy settings against a hidden list of Chinese domains and AI labs. If there was a match, the software would quietly add identifying markers to data sent back to Anthropic. Alibaba called this a back-door risk and, after what it described as a thorough internal review, added Claude Code to its list of high-risk software. 

Anthropic tells a different story. Thariq Shihipar, an engineer on the Claude Code team, wrote on X that the feature was “an experiment we launched in March that was meant to prevent account abuse from unauthorized resellers and protect against distillation.” He said stronger protections were already in place and that the problematic code was set to be removed. In fact, a pull request to delete it was merged on July 1, just one day after the Reddit post appeared. 

That explanation has not eased the dispute, which actually started weeks before the code was found. On June 10, Anthropic sent a letter to the U.S. Senate Banking Committee, accusing people linked to Alibaba’s Qwen AI lab of carrying out the largest known distillation attack on Claude so far. The letter said these operators used about 25,000 fake accounts to make nearly 28.8 million requests to Anthropic’s models between April 22 and June 5. In this case, distillation means training a weaker in-house model on the outputs of a stronger one, allowing companies to replicate years of research without making the same investment. Anthropic told lawmakers that this practice targeted Claude’s advanced reasoning, coding skills, and capacity to handle long tasks—key features that set leading AI labs apart. 

Why the Numbers Matter 

Anthropic has publicly stated that distillation attacks turn huge investments in American research and development into benefits for foreign competitors. The company has urged Washington to tighten semiconductor export rules and punish AI developers who run distillation campaigns. This is not the first time Anthropic has made such claims. In February, it accused three other Chinese labs—DeepSeek, MiniMax, and Moonshot AI—of making over 16 million requests to Claude using about 24,000 fake accounts to improve their own models. The Alibaba case stands out for its size, its direct connection to a Qwen-linked group, and the fact that Alibaba was a paying customer at the time. 

Alibaba Claude Distillation Attack Response 

Alibaba’s Alibaba Claude distillation attack response has so far been narrow and procedural rather than a full-throated public rebuttal. The company has not released a detailed statement on the distillation claims, and sources say Alibaba denies any wrongdoing but has not provided further details. Publicly, Alibaba says the ban is about the alleged back-door code, not the distillation issue, which allows the company to present its decision as a security measure instead of retaliation. However, many industry watchers are skeptical, especially since the ban came only three weeks after Anthropic’s Senate letter was made public. 

The Alibaba Qwen Anthropic Conflict Widens 

The Alibaba Qwen Anthropic conflict now touches nearly every layer of the two companies’ relationship. Alibaba’s shares fell following the initial distillation accusation in June, reflecting how seriously investors are treating the reputational risk. Engineers who once relied on Claude Code for agentic programming tasks are being pushed toward Qoder, a platform still working to match the polish of its American counterpart. Whether that transition damages near-term productivity is an open question, but Alibaba appears to have judged the compliance and legal exposure of continued Claude use as the greater risk. 

A Broader US-China AI Corporate War 2026 

This dispute is part of a bigger trend. Anthropic has the strictest access policy in the industry for China, blocking Chinese-owned companies from using its models even if they operate through foreign subsidiaries. This rule has already caused problems elsewhere. For example, Ant Group reportedly granted employees access to Claude through its Singapore branch, while ByteDance, which owns TikTok, does not officially offer access to Claude but reimburses engineers who use personal VPN subscriptions. According to the Financial Times, Anthropic is now working to close these loopholes, which will likely cause more tension before it leads to full compliance. 

Seen together, these episodes describe something larger than a single corporate feud: a US-China AI corporate war 2026playing out through terms-of-service enforcement, Senate testimony, and internal software bans rather than tariffs or sanctions alone. Anthropic has argued in its own research that curbing distillation, paired with tighter chip export controls, could extend America’s frontier AI lead by twelve to twenty-four months. Chinese firms, for their part, have leaned harder into domestic alternatives Qwen, DeepSeek, Moonshot, and Zhipu among them partly out of necessity and partly as a hedge against exactly this kind of access rupture. 

What Comes Next for Anthropic’s International Business 

The key issue for Anthropic now is how much of its Asia-Pacific business is at risk due to this ban, and whether other Chinese tech companies will follow Alibaba’s example. Alibaba employees Claude being banned from daily workflows is one thing; a wider industry pattern of Chinese firms formally blacklisting American frontier models is another, carrying implications for Anthropic’s growth outside the United States. Analysts tracking the situation will be watching for independent evidence of the alleged Claude Code back door, similar actions by companies like Tencent or Baidu, and whether Anthropic’s Senate letter leads to new laws on distillation. 

For now, the headline captures the moment precisely: “Alibaba bans all Anthropic Claude AI products employees after 29 million fake query distillation row.” Whether that framing holds up as more facts emerge, or whether it eventually reads as the opening chapter of a longer “Alibaba Claude ban internal employees Anthropic distillation accusation US China AI corporate conflict,” will depend less on this week’s headlines than on what Washington and Beijing decide to do about an AI rivalry that has moved decisively from the lab into the boardroom. 

Source: https://www.cnbc.com/2026/07/08/china-anthropic-ai-claude-code-backdoor-security-threat.html?recirc=taboolainternal 

San Francisco, California | July 9, 2026 

Overnight coding runs now come with a cost. Developers who let an autonomous agent work through the night on Claude Fable 5 woke up this week to a credit balance drained by triple digits, and the culprit wasn’t a bug. It was the calendar. Anthropic Fable 5 billing credits July 8 is now in effect, and every Pro, Max, Team, and Enterprise subscriber must pay for the flagship model by the token. 

The Claude Fable 5 pricing change closes out a turbulent month for the model, which launched on June 9, went offline for 19 days due to a federal export-control order, and returned on July 1 with limited subscription access. That access ended this week. Now, Fable 5 uses a separate, funded credit balance instead of the usage included in monthly plans. 

What Actually Changed on July 8 

Before this week, Fable 5 usage counted toward the usual weekly limits in Pro or Max subscriptions, but only up to half of that allowance. This temporary measure was Anthropic’s way of handling the model’s downtime and limited relaunch. It was always meant to be short-term. Anthropic confirmed that the free 50 percent usage ended on July 7, and the metered system went into effect at midnight Pacific time. 

The mechanics are straightforward, if unwelcome for heavy users. Fable 5 $10 per million input tokens is the confirmed API rate, and output runs even steeper. Fable 5 $50 million output tokens more precisely, fifty dollars per million output tokens — makes Fable 5 exactly double the price of Claude Opus 4.8, which remains bundled into subscriptions at $5 and $25 per million tokens, respectively. Sonnet 5, Anthropic’s newer default model for Free and Pro tiers, undercuts both at an introductory $2 input and $10 output rate through the end of August. 

The Plan-by-Plan Breakdown 

Claude Pro subscribers who pay $17 a month get Opus 4.8 and Sonnet 5 within their usual limits. To use Fable 5, they now need to enable Claude Pro Max Fable 5 credit billing in the web app’s account settings. This step is not available in the mobile apps yet. Claude Max, at $100 a month, uses the same credit system; the higher price only increases the limits for included models, not for Fable 5 tokens. Enterprise seat plans are different: Fable 5 was never included in flat-seat pricing, and premium Enterprise tiers that had the temporary 50 percent window lost it on July 7, like everyone else. 

For teams looking for all the details, the main internal search this week is: “Anthropic Claude Fable 5 pay per credit billing starts July 8 2026 full pricing breakdown explained.” This phrase sums up what finance teams need: not just the main rates, but also how the new pricing works with plan tiers, caching, and batch discounts. 

The Real Cost of an Agentic Session 

Agentic workflows feel the price increase most. In these cases, the model reads code, writes patches, tests them, and repeats the process without a human in the loop. A Claude agentic session $100 cost is no longer hypothetical. One developer said an autonomous QA loop used up a $100 daily credit in about nine minutes. The math is tough: processing two million output tokens costs $100 in credits before counting any input tokens, and long programming sessions often go beyond that in a single night. 

There are three ways to reduce costs. Prompt caching reduces the number of repeated inputs, such as system prompts, tool definitions, and stable file context, to about $1 per million tokens. This is a ninety percent discount, which is important for long coding sessions that reuse the same setup. The Batch API halves both rates for work that can wait, making Fable 5 as affordable as Opus 4.8. Finally, model routing—using Fable 5 only for complex, long tasks and sending routine work to Opus 4.8 or Sonnet 5—is becoming the key to keeping AI budgets predictable. 

Anyone building a full billing guide for this change is really looking for: “Claude Fable 5 $10 per million input $50 output credits Pro Max Team Enterprise billing guide.” In practice, the advice is simple: cache as much as possible, batch tasks that can wait, and route work based on task complexity instead of routine. 

Enterprise Reaction: Sustainable or Not 

The enterprise response has split along predictable lines. Finance teams that were already budgeting for API-rate access see the change as a formality; nothing about their cost model shifts, since direct API pricing was never bundled in the first place. Engineering teams that had grown used to unlimited Fable 5 inside a flat subscription are the ones absorbing the shock, and several have openly questioned whether a model priced at double Opus 4.8’s rate can justify itself for anything short of the hardest coding problems in a given sprint. 

The competitive backdrop sharpens that question. OpenAI’s GPT-5.6 Sol prices in at roughly five dollars per million input tokens and thirty per million outputs  cheaper on both ends than Fable 5, and dramatically cheaper on output specifically, where Fable 5’s fifty-dollar rate towers over the field. For teams running high-output workloads like long-form code generation or multi-step agent chains, that gap compounds fast. Fable 5 still holds an edge in raw capability for the longest, most complex agentic tasks, and its million-token context window remains unmatched by most competitors at this price tier. Whether that edge is worth twice the money is now a line-item decision rather than an assumption, and the answer will differ by workload, not by company size. 

What is clear is that Anthropic has stopped treating Fable 5 as a subscription perk and started treating it as a premium product with its own economics. The company has signaled that a return to bundled access is possible once compute capacity allows, but attached no date to that promise. Until then, the model’s future in everyday development workflows depends less on what it can do and more on what teams are willing to budget for. 

Source: https://www.buildfastwithai.com/blogs/ai-news-today-july-8-2026 

Washington, D.C. | July 9, 2026 

In short, the new US passport features Trump photo only available in person Washington Passport Agency 2026rollout has redrawn the limits of what a federal travel document can look like. 

Thirty thousand is the total number of these passports printed so far, and this limited run has disrupted two centuries of federal design tradition in just one week. The Trump passport 2026 photo rollout, which started Monday at a single government office in Washington, is the first time a sitting president’s image has appeared in a standard U.S. travel document. For a document that relies on uniformity and recognition, this is a major change, not merely a minor detail. 

What Changed, and Why It Matters 

The State Department started issuing the new US passport Trump image on Monday as part of the America250 initiative for the 250th anniversary of American independence. This document is only available through the Trump passport Washington, DC, agency, and applicants must make an appointment, as walk-ins are not allowed for this limited edition. Unlike earlier redesigns that featured eagles, landmarks, or historic engravings, this version shows a portrait of the president next to a reproduction of the Declaration of Independence, with his signature in gold ink below the image. 

Patrick Bixby, a humanities professor at Arizona State University who studies the cultural history of passports, called the move “entirely novel.” He pointed out that even authoritarian governments usually place leaders’ images on currency, not on travel documents intended for international use. Passports act as a kind of handshake between countries, using a shared visual language that officials abroad can quickly recognize without having to understand the politics behind it. 

The Washington Passport Agency Trump Rollout, Explained 

The mechanics of this Washington Passport Agency Trump rollout are unusually limited. Applicants cannot obtain commemorative design at regional offices in cities such as Chicago, Houston, or Los Angeles. They must show up in person in Washington, and the office usually gives same-week appointments only to travelers with urgent departure dates. This has frustrated supporters who want the passport as a keepsake, not just for travel. For example, one applicant drove from Alabama just for the passport but left empty-handed after failing to get an appointment before his return trip. This shows both the high demand and the challenges built into the program. 

Travelers who want to avoid the image have an informal option: if they request the extra-page passport, they will get the standard design, since the commemorative edition is only available in the 28-page book. This is important because early reports suggested there was confusion about whether the president’s photo was optional. Some applicants, like a woman from Richmond, Virginia who needed an emergency appointment, said they were not given a choice and later described the portrait’s expression as unsettling. 

This US passport Trump face feature raises a genuinely unsettled legal question: does the executive branch have the authority to change a core identity document to include a sitting official’s image? Passport design has usually been up to the State Department, and no law specifically bans putting a president’s image on it. However, just because it is allowed does not mean there is a precedent, and since this has never happened before, courts would be dealing with new ground if a challenge comes up. Legal scholars watching the rollout say the real comparison may not be legal, but institutional. The same discretion used to add landmarks, or wildlife is now being applied to add a face associated with a political brand. 

The Trump passport design change is part of a larger trend the administration has followed since taking office. Now, the National Park Service annual pass shows the president’s image, a commemorative coin approved by the Commission of Fine Arts features his likeness, and large banners with his portrait have appeared on federal buildings in Washington. Each of these changes could appear minor on its own, but together they show a clear effort to personalize institutions that have usually represented collective authority instead of individual leaders. 

Practical Consequences for American Travelers 

The main question for passport holders is whether this change affects how a U.S. passport is treated at foreign borders. For now, the answer is no. The commemorative edition has the same machine-readable data page, biometric chip, and legal status as any regular passport. Border agents in other countries focus on the data page and chip, not the cover or inside images, so travelers with the Trump passport 2026 photo edition should not expect different treatment at immigration in places like Frankfurt or Singapore. 

That said, symbolism carries its own diplomatic weight. Travel industry groups have voiced concern that a new passport available in person only and tied so visibly to one political figure could complicate perceptions abroad, notably in regions where the current administration’s foreign policy, including its posture toward Iran and the resulting spike in oil prices, has already strained goodwill. A passport is meant to represent a nation to the world. When it instead represents an individual, even symbolically, it invites questions the traveler did not sign up to answer. 

Reaction From Washington and the Travel Sector 

Congressional Democrats have spoken out. Senator Chris Van Hollen from Maryland said the design choice shows vanity, not patriotism, and Senator Kirsten Gillibrand from New York has proposed a law to limit a president’s ability to put personal branding on government property. On the other hand, Republican supporters have welcomed the commemorative passport as a collector’s item for the 250th anniversary, calling it a source of pride instead of controversy. 

For readers still asking why Trump image on US passport new design change only Washington DC by appointment explained has become one of the week’s most-searched phrases, the short version is this: a limited-run commemorative document, a single office, a president keen to be seen, and a public divided on what that means for a document meant to represent everyone equally. 

It is still unclear whether the design will be offered outside the Washington office. State Department officials have said the commemorative passport will stay an exception for now, and standard passports will remain unchanged at all other centers across the country. However, since the president’s image has appeared on so many federal items this year, from park passes to currency to naval ships, it would not be surprising if the design spreads further. 

By the end of the year, thirty thousand people will have this document in their pockets. It will probably say more about a presidency determined to have a lasting mark than about travel procedures themselves. 

Source: https://www.npr.org/2026/07/08/g-s1-132497/passports-trump-image 

New York, New York | July 9, 2026 

Three words from a NATO podium in Ankara ended weeks of calm in the markets. “I think it’s over,” President Trump told reporters Wednesday, referring to the ceasefire with Iran. By the end of the trading day, Wall Street had absorbed the message in full. The oil price surge Iran war July 9 episode wiped out a session’s worth of gains across almost every asset class, and traders who had been expecting de-escalation had to quickly change their plans. 

The damage was immediate and broad. The Dow drops 595 points Iran headline captured the mood on the New York Stock Exchange, where the index lost 1.1% as energy costs spiked and travel-sensitive names buckled. Crude benchmarks did the heavy lifting. Brent crude $ 78-a-barrel July 2026 pricing became the day’s central data point, with international futures rising 5.7% to $78.37 a barrel after Trump confirmed the earlier truce had ended. 

What Triggered the Selloff 

The cause was clear. On Tuesday, three commercial vessels were struck near the Strait of Hormuz. Soon after, Washington revoked a sanctions waiver on Iranian oil exports. U.S. Central Command had already carried out retaliatory strikes against Iranian targets before Trump spoke in Turkey. So, markets were reacting more to confirmation that fighting was starting again than to any surprise. 

That distinction matters for how investors are positioning now. A single provocation might have been dismissed as noise. A declared end to the ceasefire, paired with military action already underway, forces portfolio managers to price in a longer disruption. WTI crude $73 per barrel trading reflected that recalibration, with the domestic benchmark popping 4.8% to $73.84 as refiners and fuel buyers moved quickly to hedge against further supply shocks moving through the Strait, the corridor that carries roughly a fifth of the world’s seaborne crude. 

Airlines Absorb the First Blow 

No sector felt Wednesday’s move more directly than aviation. Jet fuel is one of the highest variable costs an airline carries, and every incremental dollar in crude erodes margins that carriers had only recently begun to stabilize. Airline stocks fell; fuel costs Iran was the story across the board: American Airlines fell nearly 4%, the biggest drop among major U.S. carriers. United Airlines lost 2.5%, and Delta, Southwest, and JetBlue each fell about 2%. 

Anyone who followed the sector earlier this year will recognize this pattern, when fuel costs doubled, and airlines had to cut back on their plans. This time, though, airlines have mostly stopped using fuel-hedging programs that once protected them from price swings. That leaves their finances more exposed to sudden changes. Delta has said that every one-cent increase in jet fuel costs the airline about $40 million a year, which helps explain why investors react so quickly when oil prices rise. 

Broader Market Reaction 

The selloff was not confined to airlines and energy-adjacent names. S&P 500 falls Iran ceasefire collapse trading told a similar story, with the index sliding as investors rotated out of consumer-discretionary and travel-linked positions and into conventional safe havens. Cruise operators paralleled the airline selloff, with fuel-intensive carriers like Carnival and Norwegian Cruise Line among the session’s weaker performers. Energy producers moved in the opposite direction, naturally, as higher crude prices lift the earnings outlook for domestic drillers even as they squeeze nearly every other corner of the economy. 

Gold, which people often buy during times of political tension, saw increased interest as traders weighed the risk of a longer conflict. The dollar didn’t move much, reflecting uncertainty about whether higher energy costs will prompt the Federal Reserve to keep rates steady or whether slower growth will become a bigger worry than inflation. Treasury yields, which had been falling on hopes for lasting peace, rose again as inflation expectations changed overnight. 

The IMF’s Inflation Warning 

Wednesday’s escalation collided directly with a sobering release from the International Monetary Fund. The IMF oil forecast 32 percent rise 2026, published the same week, now expects crude prices to average almost 32% higher this year than in 2025, and global consumer prices to rise 4.7%, up from 4.1% last year. This would mean that the progress most major economies have made against inflation since 2023 could stall. 

What worries policymakers about the IMF’s forecast is the assumption behind it. The IMF still expects the Strait of Hormuz to reopen later this month, even though U.S. strikes on Iran have resumed and the ceasefire has ended. Geoff Yu, a senior market strategist at BNY, said the chance of energy flows returning to normal soon is getting smaller. If he’s right, the IMF’s high forecast might actually be too low. 

A Framework for What Investors Should Watch 

For anyone trying to understand a day like this, the search phrase “oil prices surge 5 percent Dow falls 595 points Iran ceasefire over stock market impact July 9 2026” sums up what happened, but not how to respond. Four key factors will be important to watch in the coming days. 

First, shipping data from the Strait of Hormuz will be more important than any single statement from leaders. Satellite tracking of tanker traffic gives a clearer picture of supply risks than official comments. Second, airline earnings—Delta reports next week—will show how much of the fuel price increase airlines can pass on to customers without hurting demand. Third, what the Federal Reserve says over the next few weeks will help clarify whether it sees this as a short-term shock or a real threat to its inflation goals. Fourth, and maybe most important, the search term “Brent crude $78 WTI $73 Iran war restart stock market decline airline stocks fuel costs” will keep changing. Where these two oil benchmarks end up by the end of the month will show whether Wednesday was just a brief scare or the start of a longer period of high energy prices. 

Markets have bounced back from shocks in this conflict before, often within days. What set Wednesday apart was that the shock came not from a surprise attack, but from the U.S. president openly ending a diplomatic agreement that had kept things calm for three weeks. This deliberate policy change, rather than a sudden event, is why traders are being more cautious than the single-day drop might suggest. The next few trading sessions—not just Wednesday’s close—will show whether the end of the ceasefire is just a short-term setback or a sign of bigger, lasting risks for all assets linked to Middle East energy.

Source: https://www.nbcnews.com/business/business-news/oil-prices-surge-stocks-tumble-trump-iran-ceasefire-over-hormuz-rcna353446