Miami, Florida | July 7, 2026 

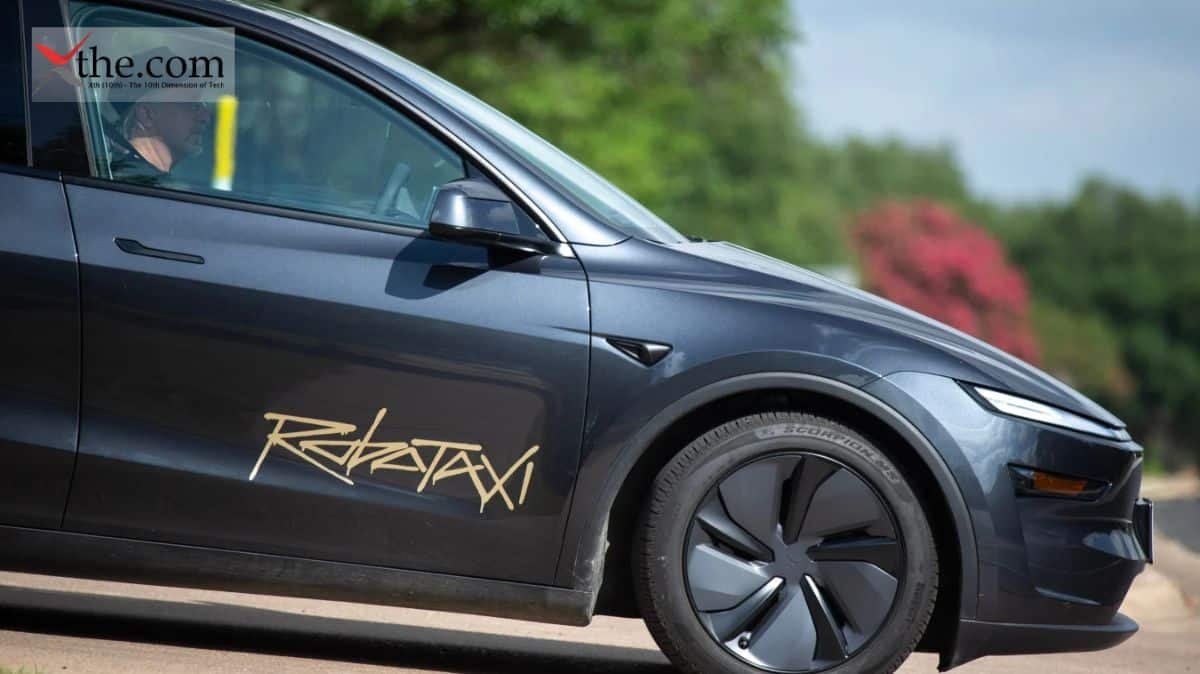
A Model Y pulls up to the curb near Miami International Airport. There’s no driver and no safety monitor simply a passenger, a phone app, and eight cameras guiding the car. What used to happen only on Austin’s side streets is now part of daily life in South Florida. This is Tesla’s biggest test yet for its self-driving technology. 

Tesla’s robotaxi Miami launch went live on July 3, when the company’s official robotaxi account posted a terse announcement on X: “Robotaxi now available in Miami.” Behind that simple line sits a tactical pivot years in the making. Florida is now the third state, after Texas and California, to get Tesla’s autonomous ride-hailing network. It’s also the first place outside Tesla’s original test areas to offer fully unsupervised rides right from the start. 

Why Miami Matters for Tesla Autonomous Miami Strategy 

Tesla autonomous Miami operations did not begin quietly. Ashok Elluswamy, Tesla’s Vice President of AI Software, confirmed just hours after launch that there are no human safety monitors in these rides. That’s a big difference from the Austin rollout in June 2025, in which every car had a front-seat monitor ready to step in. Miami skips that step altogether. 

The timing was intentional. On July 2, Tesla reported delivering 480,126 vehicles in the second quarter, beating Wall Street’s expectations and raising investor excitement. TSLA shares rose 6% following the delivery report and robotaxi news. Still, CEO Elon Musk has often said that real revenue from the robotaxi business won’t show up before 2027. Investors hoping for quick profits may be ahead of the actual timeline. 

Tesla Miami Airport Robotaxi Coverage Explains the Route Selection 

Tesla Miami Airport robotaxi footprint was not chosen at random. The geofenced service zone covers about 10 to 14 square miles in western and central Miami-Dade County, focusing on busy, airport-connected roads. This includes parts of State Road 826, the Palmetto Expressway, and U.S. 41, as well as roads leading directly to Miami International Airport. For Tesla, starting near the airport makes sense because it attracts business travelers, regular rideshare users, and tourists who already use app-based rides. 

For anyone searching “Tesla robotaxi launches Miami without safety monitor July 2026 what riders investors need to know,” the practical answer breaks into two tracks. Riders need the dedicated Robotaxi app, currently gated behind a waitlist that opened first to iPhone users, with Android support still catching up. Investors, meanwhile, are watching a company attempt to convert a car-manufacturing balance sheet into a software-and-services one, a shift that remains unproven at scale. 

Doral, Coral Gables, and the Geography Behind the Rollout 

Anyone researching “Tesla robotaxi Miami launch zone Doral Coral Gables Airport coverage area details July 2026” will find a service area that deliberately excludes downtown Miami and Miami Beach at launch. Instead, coverage concentrates on West Miami, Doral, and Coral Gables, dense but manageable suburban grids rather than the tourist-heavy waterfront corridors where pedestrian density and erratic traffic patterns pose harder edge cases for camera-based perception systems. Tesla appears to be sequencing its expansion the way any operator managing early-stage risk would: start where the roads are wide, the traffic is predictable, and the failure modes are cheaper. 

Tesla Model Y Driverless Miami Fleet, For Now 

Every vehicle currently on the road is a Tesla Model Y driverless Miami unit, the same platform used in Austin, Dallas, Houston, and the Bay Area. The purpose-built robotaxi Tesla unveiled in 2024, a two-seat vehicle with no steering wheel or pedals, is still a future addition rather than a current reality. Cybercab production 2026 targets have already been tested on public roads in Austin, but volume manufacturing has not yet reached a point where the vehicle can be deployed commercially. Until that changes, Miami’s entire fleet runs on repurposed consumer vehicles retrofitted with Tesla’s Full Self-Driving software, a stopgap that works but was never the endgame. 

Tesla Robotaxi Vs Waymo Miami: A Lopsided Scoreboard 

Any honest assessment of Tesla robotaxi vs Waymo Miami has to acknowledge the size gap. Alphabet’s Waymo has operated fully self-driving rides in Miami since earlier this year and has already built a coverage area roughly four times larger than Tesla’s initial footprint. Waymo also relies on lidar, a sensor technology that generates usable three-dimensional data even in heavy rain or glare, conditions that define a South Florida summer. Tesla’s camera-only approach carries no such redundancy, a distinction that matters given ongoing scrutiny from federal regulators. 

In March 2026, the National Highway Traffic Safety Administration took its investigation of Tesla’s Full Self-Driving system to the next level, moving to an engineering analysis, which precedes a possible recall. Regulators found that the camera-only system doesn’t always detect or warn about dangers when visibility is poor, such as in glare or heavy rain. Miami’s regular afternoon storms and bright sun will quickly test these concerns in real-life conditions. 

What the TSLA Robotaxi Expansion Signals for the Broader Strategy 

The TSLA robotaxi expansion into Florida follows a pattern that’s accelerated since January, when unsupervised vehicles joined the Austin fleet. Dallas and Houston came next in April, and Miami followed in July. The company plans to expand to Orlando, Tampa, Phoenix, and Las Vegas, but has become less specific about timing, saying only that preparations are underway. Elon Musk says any big ramp-up depends on a new version of the Full Self-Driving software, version 15, which doesn’t have a set release date yet. Texas disclosure filings show Tesla operating 42 robotaxis statewide, compared with 577 registered for Waymo, a fleet more than thirteen times larger. Scaling from dozens of vehicles to thousands is a manufacturing and regulatory challenge that dwarfs anything Tesla has solved with the Model Y line alone. 

The Road Ahead 

Miami won’t end the debate over whether camera-only systems can match lidar in tough weather, but it will provide real-world data to help answer it. Each wet afternoon commute is a live test for regulators, competitors, and shareholders. Tesla is betting that growing its fleet and improving its technology will help it catch up to Waymo. Whether that happens before 2027 the earliest year Musk expects real robotaxi revenue will decide if Miami is seen as the place where Tesla’s strategy succeeded or where its limits became clear.

Source: Why Did Tesla Stock Jump Today? 
New York, New York 
Dateline | July 7, 2026 

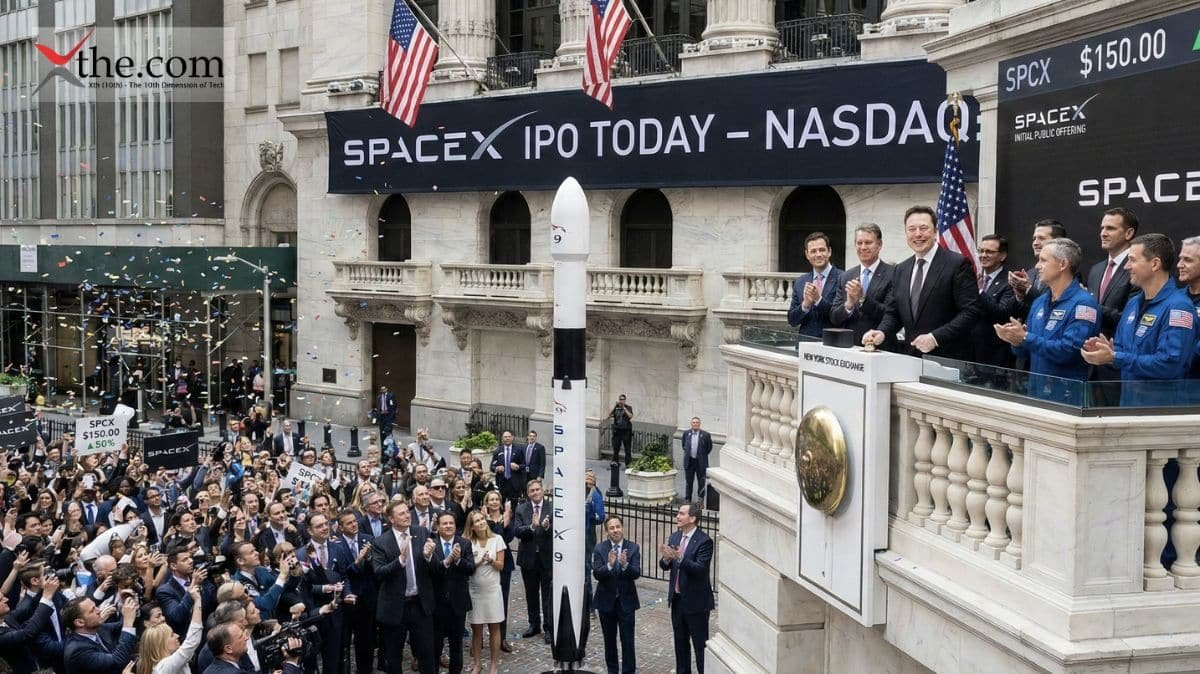
Before most traders had finished their coffee this morning, index funds managing hundreds of billions of dollars were already forced to own a rocket company. That is the blunt reality of SpaceX Nasdaq-100 July 7: the single largest passive-ownership event the exchange has staged in years, and one that millions of retirement savers never actually voted for. SpaceX’s index inclusion took effect before the opening bell, and the mechanics behind it reveal just how much contemporary markets run on rules rather than judgment calls. 

The Mechanics of SPCX QQQ Passive Buying 

Space Exploration Systems, trading under the ticker SPCX, priced its initial public offering at $135 per share on June 12, raising roughly $75 billion in what is the largest IPO in market history. Fifteen trading days later, under Nasdaq’s newly adopted fast-track eligibility rule, the company qualified for index membership without the usual waiting period of a full quarter or year. That rule change is central to understanding SpaceX Nasdaq fast-track history: it compresses a process that once took months into three weeks. 

The result is SPCX QQQ passive buying on a scale rarely seen outside of mega-cap mergers. The Invesco QQQ Trust and its sibling fund QQQM, which together track roughly $570 billion in assets benchmarked to the Nasdaq-100, had to acquire an estimated $4.3 billion in SPCX shares by the close of trading on July 6 simply to keep aligned with the index’s new composition. Add Russell index $3 billion reweighting from funds tracking the wider Russell benchmarks, and the combined mechanical demand approaches $7.3 billion money that had no discretion in the matter. Every dollar of SpaceX $4.3 billion passive buying tied to QQQ came from selling proportional slices of Apple, Nvidia, Microsoft, Amazon, Alphabet, Meta, and Broadcom, the incumbent heavyweights that ceded a sliver of their weighting to make room for the newcomer. 

SpaceX officially joins the Nasdaq-100 on July 7, 2026. $7 billion forced passive buying what QQQ investors own now. 

Ordinary 401(k) holders did not have to make any choices here. If their retirement account includes a Nasdaq-100 index fund, it now owns shares in a company worth over $1.7 trillion. SpaceX reported an accounting loss of about $4.3 billion in the first quarter of 2026, while revenue was close to $4.7 billion. This mix of big losses and strong revenue growth is common for a company growing three businesses at once: Starlink, which accounted for most of the 2025 revenue; launch operations with Falcon 9 and Starship; and an AI division added after merging with Elon Musk’s AI company in February 2026. Starlink now has over 10 million subscribers, about twice as many as at the IPO. 

Why the Float Makes This Rebalancing Unusual 

What makes SpaceX’s index inclusion different is how few shares are available to trade. Only about 3% to 5% of all SpaceX shares are publicly traded; the rest are held by insiders, early investors, and others who cannot sell yet. Because of this, SpaceX has only a small weighting in the Nasdaq-100, even though its market value is similar to Amazon’s. The index uses the number of shares eligible for trading, rather than the total value, to determine weightings. This limited supply, combined with high demand from index funds, has led to significant volatility. After the IPO, shares hit a high of $225.64, then dropped to the $150–$160 range before joining the index. 

History’s Verdict on Index Inclusion Day 

Excitement about joining a major index usually does not translate into lasting gains, and historical data suggest investors should be cautious. Looking at about three dozen Nasdaq-100 additions since 2022, including companies like Enphase Energy and Constellation Energy, the average stock fell by about 1.13% on its first day in the index and dropped another 3.41% over the next five days. Palantir and Strategy, two high-profile additions, both peaked before or around their inclusion dates. This shows that most buying occurs before the stock is added to the index, leaving little momentum once the required purchases are made. 

SPCX Nasdaq-100 inclusion day one what history says happens next week month investor analysis 

This history is important for anyone wondering if index inclusion day is a good time to buy. Usually, it is not. Index funds are required to buy shares before the inclusion date, so most of the demand has already happened by the time individual investors hear the news. 

The Lock-Up Expiry Clock Starts Ticking 

The next inflection point sits roughly a month out. SPCX lock-up expiry in August begins with the company’s first quarterly earnings report, expected around August 6, when approximately 20% of insider and pre-IPO shares become eligible for sale. A secondary trigger could release another 10% if the stock trades at least 30% above its $135 IPO price for five sessions within any ten-day window, with additional phased releases continuing through December. Until that date, the free float remains effectively frozen, which means the current wave of index-driven buying is occurring against a supply base that will not expand significantly for weeks. Once lock-ups lift, the equation changes: a stock that traded on scarcity for its first two months as a public company will suddenly face a meaningfully larger pool of shares for sale, testing the durability of its post-IPO valuation. 

What Comes Next for the Fast-Track Rule 

The new rule that allowed SpaceX to join the Nasdaq-100 so quickly was not made just for this company. The next likely examples are Anthropic and OpenAI, which may go public in 2026 or 2027. If they do, the same pattern will recur: a wave of forced index buying soon after the IPO, a small initial index weighting due to limited shares, and a lock-up schedule that investors must watch closely. For now, SpaceX is the first big test of how Wall Street handles the public listing of huge private companies, and how quickly passive investing shapes who gets included.

Source: SpaceX Joins the Nasdaq-100 on July 7. Here Is What This Means for QQQ and QQQM Investors. 

Cape Canaveral, Florida, July 3, 2026 

A spacecraft about the size of a refrigerator is now on a mission to catch up with a satellite that has been in space for 22 years. What happens next will determine if one of astronomy’s most productive tools burns up over the ocean or continues searching for exploding stars for another ten years. The NASA Swift telescope rescue 2026 effort began this week when a Pegasus XL rocket, released from a modified aircraft over the Marshall Islands, put the Katalyst Space LINK spacecraft into orbit. Its goal is the Neil Gehrels Swift Observatory, a telescope that has been tracking gamma-ray bursts since 2004 and is now struggling to stay in orbit. 

Swift was not expected to need help this early. NASA thought the observatory would stay in orbit until the early 2030s. But in 2024, a stronger-than-usual solar maximum heated and expanded Earth’s upper atmosphere, increasing drag on everything in low orbit. This caused the Swift observatory’s altitude to decay, compressing a problem NASA thought it had years to solve into one that now needs fixing in just a few months. 

Why Swift Matters Enough to Save 

Swift is not a general-purpose observatory. It was made to catch rare space events as they happen. Gamma-ray bursts, which are the brightest explosions since the Big Bang, last only seconds or minutes and disappear before most telescopes can even turn to look at them. Swift can spot a burst, find its location, and point its instruments in about a minute, sending data to ground-based telescopes before the afterglow fades. Thanks to this speed, the NASA Swift X-ray telescope has become essential for astronomers studying phenomena such as colliding neutron stars and the deaths of massive stars. 

There is no backup for Swift. NASA has made it clear that there is no budget to build a replacement, and no other mission matches Swift’s quick response and ability to observe in ultraviolet, X-ray, and gamma-ray light. If Swift were lost, it would not just end a program—it would leave a gap in our ability to observe brief astronomical events that no other instrument can currently fill. 

The Physics of a Falling Telescope 

Swift has dropped to about 370 kilometers above Earth, and without help, it was expected to fall into the atmosphere and burn up before the year ends. In February, NASA shut down Swift’s science instruments and turned the spacecraft to reduce drag by nearly thirty percent, while still keeping its photovoltaic panels working. This move was bought some time but did not fix the main problem. If Swift drops below about 300 kilometers, the drag will be so strong that a rescue spacecraft might not be able to dock or lift it. The chance to save Swift is real, but it is running out. 

Inside the Katalyst Space Rescue Mission 

NASA awarded the contract for this Katalyst Space rescue mission in September 2025. The company, based in Flagstaff, Arizona, had about nine months to design, build, test, and launch a spacecraft capable of finding, grabbing, and moving a satellite that was never meant to be serviced. This is a tight schedule for any space mission, especially for something that has never been tried at this scale. 

LINK weighs about 880 pounds, stands roughly five feet tall, and carries three xenon-fueled ion engines, solar panels generating four kilowatts of power, sixteen orientation-control thrusters, and three robotic arms built specifically for proximity operations. Over the next month, LINK will close the distance to Swift using autonomous rendezvous systems, then use its robotic arms to grip a flange on Swift originally intended only to secure the telescope during ground transport. Electric thrusters will then fire gradually over ten to twelve weeks, easing Swift up to an altitude near 370 miles; an operation NASA hopes extends the observatory’s working life by roughly another decade. If the sequence holds, Swift could resume scientific observations by September, a timeline that has made this space telescope reboot mission 2026one of the most closely watched programs in NASA’s astrophysics portfolio this year. 

Katalyst Space CEO Ghonhee Lee has openly talked about what is at stake. The bigger risk was doing nothing and watching Swift break apart during reentry, with no hope of saving it. This explains why NASA, which is usually very careful, agreed to move quickly with a company that had never handled such a complex mission before. 

A Policy Shift With Investment Implications 

This mission is important for more than just one telescope. It comes after NASA canceled its own satellite-servicing project, OSAM-1, in 2024 because of high costs. By giving the job to a private company, NASA is clearly moving toward using commercial partners. Katalyst is also using the Swift mission to work through technical challenges before launching a new servicing spacecraft, NEXUS, planned for 2027. 

For investors watching the commercial space industry, the idea is simple even if the technology is not. Right now, satellite operators view orbital degradation, fuel depletion, or component failure as the end of a satellite’s life. They write off satellites worth hundreds of millions of dollars and replace them at similar cost. If in-space servicing becomes common, operators could pay much less to keep satellites working for years longer. Analysts think this market could be worth tens of billions of dollars over the next decade as more satellites are launched and become more expensive to replace. The Swift mission is a real-world test of whether this business idea works outside of presentations. 

What Comes Next 

If the rendezvous and capture work, Swift will not merely survive but also return to normal operations, focusing again upon the brief, high-energy events that made it so valuable. If the mission fails, NASA will lose a telescope with 20 years of unique data, and the commercial servicing industry will lose its most important example to date. Coverage has already shown how this story will be told, no matter the outcome. As one industry summary said, “NASA launches rescue mission save Swift space telescope fiery reentry Katalyst Space 2026” sums up a story that mixes advanced science with a big bet on new commercial space capability. Engineers and analysts alike are treating the coming weeks as a real-time answer to the question “Katalyst Space LINK spacecraft boost NASA Swift observatory altitude July 2026 explained,” since the steps of rendezvous, capture, and reboost will either validate or complicate every future pitch for orbital servicing. 

No matter what happens in the next three months, people in the industry will not judge this mission only by whether Swift survives. They will be judging whether NASA space telescopes save operations of this kind from becoming rare rather than normal. That is the difference between a one-time engineering achievement and starting a whole new business in space.

Source: NASA launches mission to save space telescope from fiery death 

Hawthorne, California | July 6, 2026 

Three of America’s biggest wireless carriers built their empires on cell towers, but none of them own a rocket company. That asymmetry is now the central question looming over the U.S. telecom industry, after Bloomberg reported that SpaceX has held executive-level talks with Charter Communications about a SpaceX Charter mobile deal that would bring satellite-powered service directly to consumers. If the SPCX CHTR partnership happens, it would be the first time SpaceX has a confirmed ground-based partner for a standalone wireless product. The news also comes just one day before SpaceX’s shares officially join the Nasdaq-100. 

The industry has spent two years preparing for Elon Musk to enter the wireless business in his own way, so the timing of this news is striking. SPCX stock rose 2.33% on Monday as investors considered what it could mean, adding to a rally that has already made the stock one of the most closely watched new entries to the index in years. 

What the SpaceX Charter Mobile Deal Actually Involves 

According to Bloomberg’s sourcing, the discussions center on a SpaceX Charter Communications Starlink Mobile arrangement where Charter would route some of SpaceX’s mobile phone traffic through its own ground-based internet network. This idea isn’t new for Charter. The company already does something similar with its Spectrum Mobile brand, which serves over 12 million wireless customers by combining wholesale network access from T-Mobile and Verizon with Charter’s nationwide Wi-Fi. Adding Starlink to this setup would let SpaceX offload traffic in crowded cities, where satellite capacity is limited, while keeping its satellites focused on rural and remote areas where it already provides strong coverage. 

Neither company has confirmed that a deal is close, and Charter declined to comment when asked by reporters. Still, the fact that these talks have reached the executive level suggests they are more serious than routine vendor conversations. This is precisely the kind of SpaceX Charter Communications talks Starlink consumer mobile phone service US launch explained scenario analysts have discussed since SpaceX first launched direct-to-cell texting with T-Mobile. 

From Add-On to Standalone Product 

Today, Starlink Mobile exists only as a $10-per-month add-on bolted onto a T-Mobile plan, mostly useful for texting and basic connectivity in cellular dead zones. A SpaceX Starlink consumer phone plan built with Charter would be something categorically different: a standalone service sold directly to households, not a supplemental feature buried in someone else’s bill. SpaceX President Gwynne Shotwell has been unusually direct about the ambition here, telling CNBC that Starlink Mobile could eventually dwarf the company’s home broadband business in subscriber count, on the logic that nearly everyone needs a phone plan while broadband competition remains fragmented and regional. 

Achieving that requires more than clever traffic routing. It requires spectrum, infrastructure, and regulatory standing — and SpaceX has quietly assembled all three over the past year. 

The FCC Angle Nobody Should Ignore 

SpaceX is no longer only a satellite operator asking other carriers for help. Following recent wireless spectrum auctions and the purchase of mobile spectrum rights from EchoStar, the company now owns AWS-3 band spectrum. This gives SpaceX the regulatory base to launch a service without relying completely on a partner’s licensed airwaves. It also changes how Charter, T-Mobile, Verizon, and AT&T approach negotiations. SpaceX is now a licensed spectrum holder that can realistically choose to operate on its own, so any partnership with Charter is now a real business decision, not just a favor. 

This regulatory change is easy to miss amid all the attention on stock prices, but it could be more important than the Charter talks about themselves. Owning spectrum is like owning the land under your house, not just renting the house. 

Why Legacy Carriers Should Be Worried 

The SpaceX T-Mobile AT&T Verizon threat is no longer hypothetical. TD Cowen analysts have repeatedly warned clients that a SpaceX-branded wireless product represents a permanent overhang on all three major carriers, regardless of how quickly — or slowly — it scales. The logic is simple. Wireless is a saturated, low-growth market where carriers compete mostly on price and network dependability. A new entrant backed by a satellite constellation covering nearly the entire planet, with no legacy copper infrastructure to maintain, and a direct line to tens of millions of existing Starlink broadband subscribers, does not need to win outright. It only needs to peel off enough price-sensitive or rural customers to compress margins across the industry. 

Charter is in a unique position here. It already resells Verizon’s network through Spectrum Mobile, so a closer partnership with SpaceX would help Charter reduce its reliance on Verizon while positioning itself as the top ground-based partner for the company most likely to transform the wireless industry. This is a smart move for Charter, but it puts Verizon in a tough spot. 

Reading the Market Reaction 

Monday’s move makes SPCX stock a case study in how Starlink direct-consumer mobile US speculation now trades on its own catalyst, independent of confirmed deal details. The 2.33% gain also came as investors looked ahead to Wednesday’s Nasdaq-100 inclusion, when index funds are expected to buy billions of dollars in shares no matter what the news is. It’s hard to tell how much of Monday’s rise is real expectations for a Charter deal and how much is just index-related buying, so investors should see these as two separates but overlapping reasons, not just one story. 

Still, the direction of travel is consistent. Every incremental data point — spectrum acquisitions, executive-level partnership talks, Shotwell’s public comments about mobile’s addressable market — points toward SpaceX treating wireless as a genuine growth vector rather than a niche add-on. For anyone parsing a SpaceX satellite phone plan Charter deal, what it means for T-Mobile, AT&T, and Verizon investors, the takeaway is that this is now a SPCX stock catalyst with staying power, not a one-day headline. 

What Comes Next 

No financial terms, timeline, or exclusivity details have been shared, and both companies can still walk away from the talks. But the direction is clear. SpaceX now has the spectrum, the subscriber base, and possibly the ground-based partner it has needed since Starlink Mobile first launched as a small T-Mobile add-on. If the Charter talks lead to a formal deal in the next few months, the U.S. wireless industry will have a fourth major competitor for the first time in over a decade—one that owns its own satellites and, increasingly, its own spectrum. Legacy carriers have had two years to get ready for this. Soon, we’ll see if that was enough.

Source: Elon Musk’s SpaceX Set To Join Nasdaq-100 

Mountain View, California | July 4, 2026 

A single number hidden on page fourteen of a corporate sustainability report rarely moves markets. This one should. Google electricity use is 37 percent higher than a year ago, which is not a small mistake or a seasonal change. It is the clearest signal yet that the artificial intelligence buildout has outrun the pace of the electrical grid itself. The disclosure, tucked inside the company’s newly released Google environmental report 2026, marks the steepest single-year jump in Google’s history and arrives just as investors, regulators, and utility planners are rethinking what it really costs to run AI. 

The headline figure is not an isolated curiosity. It sits inside a broader model of Google AI power consumption 2026 that touches emissions, water, and capital markets all at once, and it lands in the same week that Amazon published its own sustainability accounting. Together, the two documents offer the first real side-by-side look at what the race to build frontier AI infrastructure is actually extracting from the planet. 

The Numbers Behind the Surge 

Google’s data centers are, by most engineering measures, more efficient than they were five years ago. Cooling systems have improved. Chip utilization has climbed. And yet none of that efficiency improvement was enough to offset the sheer scale of new AI infrastructure coming online. Electricity demand jumped 37 percent year over year  up from a 27 percent increase the previous year, and roughly three and a half times the load the company was drawing back in 2019. That trajectory is the core of what industry analysts are now calling the Google AI drives record 37 percent electricity surge 2026 environmental report explained story: a company concurrently investing billions in clean power while watching its own hardware appetite grow faster than that clean power can be delivered. 

Greenhouse gas emissions told a similarly uncomfortable story. The Google greenhouse gas 18 percent rise recorded in the report is the largest annual increase the company has ever disclosed, and it was driven less by the electricity powering its servers than by the manufacturing process behind the chips themselves. Semiconductor fabrication, much of it concentrated on carbon-intensive grids in Taiwan, Japan, Vietnam, and India, is now a bigger swing factor in Google’s carbon math than most of its own data center operations. 

Water told a third version of the same narrative. Operational water consumption climbed to 10.9 billion gallons, a jump of roughly 34 percent, almost entirely tied to the cooling demands of high-density server clusters running machine learning workloads around the clock. The Google water use 10.9 billion gallons figure is not an abstraction for the communities near Google’s data center campuses in Iowa, Oklahoma, and Nevada, where local water tables and utility planning boards are already contending with industrial-scale demand that did not exist a decade ago. 

A Data Center Footprint the Size of a Country 

Perhaps the most vivid figure in the entire filing is the raw scale of the infrastructure itself. Google’s 42 million megawatt-hour data center consumption in 2025 is not a number most readers can intuitively grasp, so it helps to put it beside something familiar: it is roughly comparable to the entire annual electricity consumption of a country like New Zealand or Denmark. One company’s server farms, in other words, now draw as much power as the households, factories, and offices of a mid-sized industrialized nation. 

That comparison is at the center of what a growing cohort of energy analysts are framing as the Google AI data center electricity 42 million megawatt hours climate impact investor analysis the recognition that AI infrastructure has quietly become one of the largest new sources of electricity demand in the developed world, arriving faster than utilities can plan transmission upgrades or generation capacity to match it. 

The Investor Angle 

For investors, this report is less about the environment and more about where money will go next. Utility stocks near major data center hubs are already rising due to expected long-term demand. Nuclear energy companies, once seen as slow-moving, are getting new interest as large tech firms sign long-term deals for steady, carbon-free power. Developers of clean energy infrastructure also stand to gain, since Google announced it signed deals for over 12 gigawatts of new clean power in one year. According to Google, that is enough to power a country the size of Greece when fully running. 

This is the business side of the bigger conversation about AI and climate. Every extra gigawatt of AI computing means real orders for turbine makers, grid suppliers, and power producers. Wall Street now sees electricity access, not chip supply, as the main limit on how fast an AI company can grow. If a company cannot get enough power, it cannot build more data centers, no matter how many advanced chips it has. 

Amazon’s similar report supports this trend. The company reported a 16 percent rise in emissions for 2025 and added more data center capacity than any other company last year, including over 1.2 gigawatts in the fourth quarter alone. Now, two of the world’s biggest cloud companies are saying the same thing in different numbers: AI infrastructure growth is now the main force behind rising corporate energy demand. 

Regulatory Risk on the Horizon 

There is another important part of this story that investors should not overlook. The Federal Trade Commission is already looking closely at how AI companies promote the accuracy and safety of their models. It would not be surprising if environmental regulators soon start asking tougher questions about the energy and water use behind these systems. State utility commissions, especially where data centers are putting pressure on local grids, are becoming more willing to establish new standards, impose charges, or require more disclosures from large power users. When a company reports its biggest-ever increases in electricity use and emissions in the same year, it is, whether it means to or not, creating the basis for future regulations. 

Google’s report openly admits this problem, saying its infrastructure is growing faster than the electrical grid is becoming cleaner. This is a surprisingly honest statement from a company that has spent years presenting itself as an authority in sustainability in Silicon Valley. 

What Comes Next 

The race to build AI infrastructure is not slowing down, and demand for electricity, water, and raw materials continues to grow. What is changing is the level of scrutiny. Investors now see energy access as a key asset, not merely a routine cost. Regulators are starting to ask tough questions about environmental impact, just as they have about algorithms. Companies building the next wave of AI are finding that their biggest challenge may not be getting enough chips, but getting enough power from the grid.

Source: Google AI Electricity Up 37%: Renewable Certificates Cannot Cover the Supply Chain Carbon 

San Francisco, California | July 5, 2026 

Forty-two point six billion dollars. That is about what a 5% stake in OpenAI would be worth today, and it is also the amount Sam Altman is reportedly asking Washington to accept as a gift. It is an unusual move for a company that has not gone public. But Altman does not do modest asks, and the same appetite for scale is now defining the biggest question looming over the AI industry: OpenAI IPO valuation: $1 trillion, or nothing at all. 

That is not hyperbole. According to the Motley Fool analysis published July 5, Altman has told advisers that any listing priced below the trillion-dollar mark is a Sam Altman IPO nonstarter. The comment reframes an entire IPO calendar built around one man’s refusal to negotiate, and it forces a comparison that most retail investors have not had to make before: OpenAI vs SpaceX IPO positioning, and which of the two AI-adjacent giants actually earns a spot in a long-term portfolio. 

Why $1 Trillion Is the Number Altman Won’t Move Off 

OpenAI’s most recent private valuation stands at $852 billion, set in March when the company closed a $122 billion funding round co-led by SoftBank, Amazon, and Nvidia. Getting from there to Altman’s floor requires public-market investors to pay a premium of roughly 17% above that private mark on day one of trading. That is the essence of the OpenAI $852 billion valuation IPO premium problem: it is not a small gap to close, and it assumes a level of investor conviction that few technology listings have commanded at this scale. 

According to the New York Times, advisers gave Altman two options: accept a lower valuation and go public before the end of 2026, or insist on the $1 trillion mark and wait until next year. Altman chose to wait. This decision has already modified the OpenAI IPO timeline 2027, pushing what was once a late-quarter 2026 target into a window some bankers now see as more likely in spring 2027. Prediction markets on Kalshi currently give a 59% chance of an official IPO announcement by March 2027, rising to 73% by June. 

The math behind Sam Altman investor demand is not arbitrary. Reaching $1 trillion would place OpenAI in the same public-market bracket as Nvidia, Microsoft, Apple, and Alphabet the only companies that have sustained that valuation threshold once listed. Altman wants OpenAI’s public debut to announce membership in that club on day one, not to work its way toward it over several quarters. Skeptics, including Bridgewater Associates co-chief investment officer Greg Jensen, have argued the implied 35x revenue multiple prices in a monopoly outcome that has not yet materialized. OpenAI is still burning an estimated $27 billion a year, a detail that tends to get lost in headline valuation figures. 

The SpaceX Precedent Cuts Both Ways 

Elon Musk’s SpaceX went public on the Nasdaq on June 12, and at first, the debut seemed to support Altman’s goals. Shares started at about $150 and briefly reached $225, giving SpaceX a market value of around $1.77 trillion—more than twice Altman’s target for OpenAI. But the gains did not last. By late June, SpaceX shares had dropped back to about $153, losing roughly 32% from their peak in less than two weeks. 

This volatility is now a key issue for anyone comparing OpenAI vs. SpaceX investor choice. SpaceX offers something OpenAI does not: a stock symbol and immediate trading. However, its share price has already swung sharply, and its business includes a profitable Starlink unit alongside a loss-making xAI division, which made up 76% of its capital spending in early 2026. This mix makes it hard to judge SpaceX’s true value. OpenAI, on the other hand, is not available to retail investors yet. The company filed a draft registration with the SEC on May 22 and made it public on June 9, but CFO Sarah Friar says there is no set timeline for going public. 

Indirect Exposure and the Government Wildcard 

Investors who do not want to wait can already get indirect exposure to OpenAI through SoftBank, which has invested about $65 billion and owns around 13% of the company. This investment is also volatile: SoftBank’s stock dropped over 12% in Tokyo in a single day after news of the 2027 IPO delay, wiping out about $38 billion in value. SoftBank also has a $40 billion bridge loan linked to its OpenAI investment, due in March 2027, which is close to the expected IPO window. 

There is also a proposal that could complicate matters. OpenAI has reportedly offered the U.S. government a 5% equity stake, worth about $42.6 billion at today’s valuation, as part of a plan where other major AI companies would also give similar stakes through a public wealth fund. If this happens, Washington would become OpenAI’s second-largest outside investor after SoftBank, adding political and regulatory challenges that most IPOs do not face. Such a deal would likely require congressional approval, and it is unclear whether other companies like Anthropic, Google, or Meta would agree to similar terms. 

Anthropic Changes the Comparison Entirely 

Menlo Ventures shows that private AI investments can pay off. The firm invested about $500 million in Anthropic across several funding rounds, and that stake is now worth nearly $14 billion as Anthropic’s valuation has risen above $900 billion. This is important because Anthropic, not OpenAI, is now the most likely AI company to go public soon. Anthropic filed a confidential S-1 on June 1, and its October 2026 IPO target is still on track, even as OpenAI’s timeline has slipped. 

Anyone looking up “Sam Altman says OpenAI IPO below $1 trillion valuation is a nonstarter July 2026 explained “should see the SpaceX example as a lesson, not a final answer. SpaceX shows that companies can debut at over a trillion dollars, but they can also lose a third of their value in just two weeks. For those comparing “OpenAI IPO versus SpaceX which is better investment Sam Altman $1 trillion demand July 2026,” the truth is that neither is a straightforward choice right now: SpaceX is public but volatile, while OpenAI is still private, delayed, and involved in a government stake deal with no precedent. 

What happens next may not be decided by OpenAI’s boardroom. If Anthropic goes public in October at or above its $965 billion private valuation, it will create a benchmark that OpenAI’s bankers must match or justify in 2027. If Anthropic’s IPO falls short, Altman’s $1 trillion minimum will become harder to defend. Either way, the number Altman insists on is now the standard by which the whole AI IPO market will be measured.

Source: Sam Altman Called Any OpenAI IPO Valuation Below $1 Trillion a “Nonstarter.” Should Investors Prefer OpenAI or SpaceX? 

Kent, Washington | July 5, 2026 

Twenty-five years. That is how long Jeff Bezos ran Blue Origin as a one-man bank, writing checks from his own Amazon fortune while never once inviting a stranger to the table. That era ended this month. Jeff Bezos’s Blue Origin funding has always meant one thing: Bezos’s own capital, deployed on his own timeline, answerable to no board and no outside shareholder. Now, following a rocket explosion that has disturbed the company’s engineering teams and its balance sheet alike, Bezos is doing something he has never done before. He is opening Blue Origin’s cap table to Blue Origin investors in 2026, a decision that marks the most consequential structural shift in the company’s history. 

The reason for this change is clear. On May 28, a New Glenn rocket exploded during a test at Cape Canaveral, destroying a rocket worth between $100 million and $150 million and damaging a launch facility that cost about $1 billion to build. Engineers still do not know what caused the accident. The timing was especially bad: just eight days earlier, Bezos told CNBC that Blue Origin finally had “enough visibility into our future and our financial success” to bring outsiders in. Instead of capping a triumphant stretch, the Blue Origin explosion fundraise now looks like damage control dressed up as strategy. 

Why Bezos Is Finally Opening the Door 

Blue Origin is reportedly burning close to $5 billion a year, a figure analysts expect to climb as reconstruction and re-testing costs pile up. For a private company with a single financial backer, that is an unsustainable trajectory even for a founder with Bezos’s resources. A Blue Origin capital raise does not necessarily signal desperation, but it does signal limits. No single fortune, however large, scales indefinitely against the cost structure of a modern launch and lunar-lander business trying to compete on multiple fronts at once. 

The search for Jeff Bezos‘ space company capital was reportedly under discussion well before the explosion. Blue Origin CEO Dave Limp told employees at an all-hands meeting earlier this year that external fundraising might become necessary if the company followed through on plans to sharply increase its launch cadence. Those framing matters. This was not originally conceived as a rescue raise. It was conceived as a growth raise, meant to fund an ambitious ramp-up in-flight frequency across New Glenn, New Shepard, and the company’s lunar lander program. The explosion simply accelerated the timeline and shifted the narrative from “expansion capital” to “recovery capital” almost overnight. 

What a Blue Origin Round Will Likely Look Like 

People hoping for a retail on-ramp should adjust expectations. Any near-term Blue Origin capital raise will almost certainly be limited to large institutional investors such as sovereign wealth funds, private equity firms, and key strategic partners who can commit for the long term. Regular investors probably will not get direct access soon, though they might be able to invest indirectly through funds or special-purpose vehicles, similar to how it worked with SpaceX before it went public. Some private-market sources have suggested Blue Origin could be valued around $100 billion in its first external round, but no lead investor has been named, and no official offering has been announced. 

The Shadow of SpaceX 

No conversation about Blue Origin’s financing options happens in a vacuum, and the Blue Origin vs SpaceX rivalry has rarely felt this lopsided. On June 12, Space Exploration Innovators completed the largest initial public offering in history, raising approximately $85.7 billion after underwriters exercised their overallotment option. Shares priced at $135 and closed near $161 on day one, pushing the company’s market capitalization past $2 trillion. SpaceX is now set to join the Nasdaq-100 before markets open on July 7, one of the fastest index inclusions on record under rules Nasdaq relaxed earlier this year, an action anticipated to trigger billions in mechanical buying from passive funds that track the benchmark. 

The difference between the two companies is clear. SpaceX is now a public company worth over a trillion dollars and has more than $85 billion in cash. Blue Origin, on the other hand, is still private, losing money, and has relied on Jeff Bezos alone until now. Blue Origin has not filed for an IPO, and its leaders have avoided implying that current talks are leading to one. Still, investors will likely compare Blue Origin’s situation to SpaceX’s path, which included large private funding rounds before going public. 

What Prospective Investors Should Actually Evaluate 

Anyone weighing exposure to a future Blue Origin round needs to look past the headline and toward the hardware and contracts underneath it. The Blue Origin New Glenn rocket remains the centerpiece of the company’s commercial ambitions, a heavy-lift vehicle designed to compete directly with SpaceX’s Falcon and Starship lines for both government and commercial payloads. Its successful flights to date had been building credibility before the May explosion; the setback delayed that momentum but did not necessarily erase it, particularly since the U.S. Space Force has confirmed Blue Origin remains eligible to compete for national-security launch contracts because the failure occurred during a ground test rather than a certification flight. 

In addition to its rockets, Blue Origin has a NASA lunar lander contract through the Artemis initiative. This government partnership gives the company a steady source of income and a competitive advantage that a purely commercial launch business would not have. Blue Origin also operates in the satellite and defense markets, where dependability and government trust are just as important as rocket power. Investors should consider the impact of the explosion alongside these strengths: a proven rocket, a major NASA contract, and a founder who is still willing to support the company financially while bringing in outside help. 

A New Financial Phase for the Space Race 

The era of billionaires funding the space race on their own is coming to an end. For the past twenty-five years, the biggest investments came from people like Bezos at Blue Origin and Musk at SpaceX. Now, SpaceX has entered the public markets on a scale never seen before in aerospace. Blue Origin is starting to move in the same direction, though more cautiously, partly due to recent events. Whether Blue Origin raises money from institutions to help New Glenn recover or eventually goes public, like SpaceX, it is clear that even the wealthiest founders now need outside support. 

For those looking for more information: The main questions people are searching for this week are “Jeff Bezos Blue Origin seeks outside investors first time 25 year history July 2026 explained” and “Blue Origin capital raise after rocket explosion what investors need to know July 2026.” Both topics are covered above. The decision to raise money began before the explosion but was accelerated by it, and any new funding will come from institutions rather than the public markets.

Source: Jeff Bezos Is Seeking Outside Investors for Blue Origin for the First Time in the Company’s 25-Year History 

Washington, DC | July 5, 2026 

Before sunset on the nation’s 250th birthday weekend, forty-four people on the National Mall needed medical attention. This number sums up much of what the celebration was like: a long-anticipated event nearly eclipsed by extreme heat and a president who kept politics front and center. The Trump July 4, 2026, speech was promoted as a unifying tribute to the country’s founding, but it turned out to be more like a campaign speech, set against record fireworks, crowd evacuations, and a canceled parade that drew as much attention as the president’s remarks. 

A Milestone Wrapped in Political Rhetoric 

The America 250th anniversary speech season actually began a day early, on July 3, when the president went to South Dakota for the Trump Mount Rushmore Independence Day address. Standing below the carved faces of four former presidents, he began by praising American exceptionalism and called the founders men of “action” and “destiny.” Then his tone changed. He warned about a “resurgence of the communist menace,” comparing it to the threats of Pearl Harbor and September 11, and criticized the recent success of democratic socialist candidates in the Democratic Party. 

That shift set the mood for the main event in Washington the next night. At the “Salute to America” celebration on the National Mall, the president again used patriotic symbols, like an antique flag said to have covered Abraham Lincoln’s coffin, to make a more extensive political point. He repeated his call for Congress to end the filibuster and pass his stalled election reform, the SAVE America Act, portraying it as essential to Republican survival in the coming midterms. It was, in the words of one wire report, a Trump semi quincentennial speech political enough to break with decades of precedent set by predecessors such as Gerald Ford and Ronald Reagan, who used the holiday to promote unity rather than partisanship. 

From South Dakota to the National Mall 

The difference between the two locations was important. Mount Rushmore is a powerful symbol of presidential legacy, and giving a major speech there, as he did in 2020, let the president draw comparisons to that legacy. In Washington, the situation was different: the audience faced dangerous heat, an attempt was made to set a Guinness World Record with about 850,000 fireworks, and people across the country watched to see how far the president would push the limits of a usually ceremonial holiday speech. 

Heat Wave Rewrites the Script 

No retelling of the weekend is complete without the weather, because the July 4, 2026, extreme heat National Mall conditions genuinely altered the shape of the celebration. The National Weather Service issued an extreme heat warning for Washington, D.C., with a heat index between 110 and 115 degrees Fahrenheit. Organizers made the unusual call to scrap Washington’s traditional Independence Day parade entirely, citing safety concerns for marchers, spectators, and staff. The decision showed a more general pattern: Independence Day parade canceled heat notices went out in Philadelphia, Leesburg and Fairfax, Virginia, and several Maryland communities because officials decided the high heat made outdoor events too risky. 

The Great American State Fair, a sixteen-day event on the National Mall for the anniversary, had to close temporarily after many people needed treatment for heat-related illnesses, and several were hospitalized. Evening thunderstorms made things worse, and organizers evacuated thousands from the mall hours before the president spoke. He ended up giving his speech after 11 p.m., delaying the record-setting fireworks until late into the night. It was an unusual mix of weather challenges and political drama, not often seen on a holiday usually known for barbecues and small-town parades. 

A Nation Divided Reacts 

People reacted to the America 250 celebration in 2026 much as they have in the past, but the divide was even more acute this time. Supporters at Mount Rushmore and the National Mall said the president’s speech defended American identity at a time they see as uncertain, and some pointed to recent wins by socialist candidates as a reason for stronger rhetoric. Critics, on the other hand, saw the event as a ceremony meant for reflection, not political fights, and felt it was turned into a platform for midterm campaigning and criticism of opponents. 

Democratic officials responded with their own events. The mayor of New York City gave a speech saying that the country is still striving to live up to its founding ideals. Maryland’s governor spoke in Annapolis, delivering a clear contrast to the president’s tone. A former Democratic president released a statement warning about national division and threats to democracy, timed to coincide with the day’s events. Many regular attendees, however, said they felt more tired than angry and planned to focus on their local communities and personal resilience instead of national politics. 

What the Semiquincentennial Means Now 

Wire services summed up the event with a phrase: Trump July 4, 2026 political speech America 250th anniversary Mount Rushmore semiquincentennial, which shows both the locations and the mood of the moment, from South Dakota to the heart of Washington, D.C. Another phrase, July 4, 2026 Independence Day parade canceled extreme heat 115 degrees National Mall Washington DC, highlights how rare it was for weather, not security or budget issues, to cancel one of the country’s main civic traditions. 

Overall, the weekend showed how divided American identity has become as the country turns 250. Earlier plans for the semiquincentennial imagined a unifying celebration across all fifty states. Instead, the anniversary came during a time of intense partisanship, with different ideas of patriotism on display from Mount Rushmore to Annapolis to New York Harbor. Whether the rest of the 250th anniversary events become more unifying or continue to show these divisions will say a lot about America’s future.

Source: Trump touts America’s “golden age,” attacks communism in delayed July 4th speech 

Washington, D.C. | July 6, 2026 

The United States has contributed about $999 billion to NATO’s common defense since the current accounting period began, according to a chart President Trump shared on Truth Social last week. In comparison, the United Kingdom spent $90.5 billion, and France spent $66.5 billion. Trump argues that this disequilibrium is not just unfair, but unsustainable. 

In a Thursday night post that has dominated pre-summit coverage, Trump declared it Trump NATO ridiculous remarks-worthy that Washington should keep underwriting European defense “along this one-sided path when the relationship is not reciprocal.” He also wrote, “They were not there for us!!!” This outburst comes just six days before allied leaders meet in Ankara as they prepare the ground for what could be the most contentious Trump-NATO Turkey summit in the alliance’s 77-year history. 

The Remarks That Revived the Rift 

Trump’s frustration is not new, but the timing and detail are. Instead of making a general complaint about allies not paying enough, the president shared a country-by-country breakdown, comparing America’s nearly trillion-dollar contribution to Italy’s $48.8 billion and Poland’s $44.3 billion. This highlights a long-standing issue: independent estimates say the U.S. has covered about 70 percent of NATO’s military spending for much of the alliance’s history, even as European economies have grown stronger and more able to support their own defense. 

The US NATO one-sided Trump framing did not emerge from a vacuum. It followed a June 24 Oval Office meeting with NATO Secretary General Mark Rutte, where they discussed burden-sharing. According to people familiar with the meeting, Trump is increasingly impatient with allies he sees as slow to meet their commitments. U.S. Ambassador to NATO Matt Whitaker has publicly acknowledged Trump’s frustration, pointing to Spain’s defense spending and Turkey’s continued use of Russian-made S-300 missile defense systems as ongoing sources of tension in an alliance meant to be united. 

Inside the “One-Sided” Math 

To understand why Trump keeps raising this issue, it helps to look at the numbers. NATO’s own data shows that European allies and Canada increased their combined defense spending by nearly 20 percent in 2025, raising their share of GDP to about 2.3 percent. This is a big improvement from 1.4 percent in 2014, when only three countries met the spending guideline. Still, the actual dollar gap between U.S. and European contributions is huge, and it is this gap, not the percentage increases, that drives Trump’s complaints. 

This is the crux of the US-NATO relationship 2026 debate: Is burden-sharing improving quickly enough, or is the imbalance so deep that no summit agreement can fix it? Trump’s blunt answer is that his patience has run out. 

Trump calls US NATO relationship ridiculous ahead of Turkey summit July 2026 explained. 

In short, last year’s Hague summit set a goal for allies to spend 5 percent of their GDP on defense and security by 2035, allocating 3.5 percent to core defense and 1.5 percent to areas such as cyber defense and critical infrastructure. Trump called this pledge a historic win, but now says the transition is too slow and that the uneven spending gap should not continue for another decade while the U.S. pays the largest share. 

What the Turkey Summit Is Set to Produce 

The NATO summit in Turkey in July 2026, gathering scheduled for July 7–8 in Ankara, was originally billed as a checkpoint on the implementation of the 5 percent pledge. National roadmaps outlining how each member intends to hit that target were due by mid-2026, and diplomats expected the summit to focus on procurement coordination and industrial capacity rather than fresh confrontation. 

Trump’s outburst on Truth Social has changed the summit’s agenda. A former NATO official predicted the meeting will now focus on “how angry President Trump chooses to feel” about what he sees as a lack of European support during the recent U.S. military campaign against Iran. The president is determined to get concessions from allies he believes did not provide enough help when the U.S. needed it most. 

Spending Targets and the 5% Wartime Footing 

The Trump NATO spending demands at the center of this summit go beyond just meeting the 5 percent target on paper. Administration officials want faster timelines, more purchases of American-made equipment, and clearer commitments on troop readiness. Defense Secretary Pete Hegseth has already started this process by announcing a review, expected to last up to six months, of U.S. force posture and bases across Europe. Hegseth says the goal is to make sure “NATO is moving fast and irreversibly toward Europe leading, stepping up to take primary responsibility for the defense of Europe.” Whether this review will lead to troop withdrawals is still unclear, and several European capitals are watching closely. 

Broader NATO alliance spending 2026 dynamics also appear over the summit. Poland, the Baltic states, and Greece are already spending more than 4 percent of their GDP on defense, a commitment driven by their closeness to Russia. Spain, on the other hand, negotiated an exemption from the 5 percent goal and plans to keep its defense spending near 2.1 percent. This exception has clearly annoyed the White House and is a frequent topic in Trump’s criticism of the alliance. 

Europe’s Response 

European officials have mostly avoided direct confrontation, instead highlighting the spending increases already in progress. Germany has suspended its constitutional debt limit to fund a major defense expansion, and the United Kingdom has confirmed it will aim for the 5 percent target. Still, there is real concern in European capitals about an unpredictable American president who has suggested reducing U.S. support for NATO. Turkish President Recep Tayyip Erdoğan, as host, is expected to present himself as a key link between Washington and Brussels. 

Why the Timing Matters 

The recent U.S.-Iran conflict is the context for these tensions. It showed the strength of the American military but also reduced public support for more foreign involvement. After showing what the U.S. can do on its own, the White House seems less willing to accept a NATO setup that asks for commitment lacking equal investment. This mix of proven strength and growing fatigue makes Trump’s demands at the Turkey summit more forceful than similar complaints during his first term. 

Trump’s NATO remarks and the Turkey summit on alliance spending commitments: US-Europe 2026 dynamics will likely be judged less by what is announced in Ankara and more by what happens afterward. The key questions are whether the roadmaps become real contracts and whether the Pentagon’s review of U.S. forces in Europe leads to actual troop reductions. 

Markets Watch the Spending Signal 

Defense contractors are not waiting for the Defense Department; they are already factoring in the summit’s possible outcomes. Lockheed Martin, RTX, and Northrop Grumman, the three largest U.S. defense companies, have a combined order backlog of over half a trillion dollars, much of it from NATO contracts linked to the 5 percent spending goal. Analysts say that when Trump pushes harder on burden-sharing, these stocks often react, since faster spending means more orders for missiles, munitions, and air-defense systems. Wall Street’s view of the Ankara summit will depend on the details: quicker procurement could boost these companies, while signs of disagreement between the U.S. and Europe could cause short-term swings in defense stocks. The underlying arithmetic Trump keeps citing will not resolve itself in a single communiqué. Europe has committed to spend more, and is, by the numbers, doing so. But closing a gap built over eight decades of asymmetric investment takes years, not a two-day summit. What the Turkey gathering will determine is whether that gap narrows on cooperative terms, or under continued pressure from a Washington that has made clear its patience for the old arrangement has run out. 

Source: Trump says U.S. maintaining current support levels for NATO would be “ridiculous” 

Washington, D.C. | July 6, 2026 

Fifteen million people is not a crowd. It is a message. That is roughly how many mourners Iranian officials expect to pass through Tehran’s streets before the week is out, and by Sunday the Iran Khamenei funeral 2026 had already produced the kind of images Tehran’s theocracy wanted the world to see: red banners, chests beaten in time, and a chant that required no translation. The Iran supreme leader killed US airstrike that opened the war on February 28 has become the occasion for the largest state funeral in the Islamic Republic’s history, and the Iran funeral chants of revenge rising from the Grand Mosalla complex are landing at the most inopportune moment for a ceasefire that was already showing cracks. 

For investors, policymakers, and executives watching Middle East risks, the funeral is not simply a backdrop to diplomacy. It is the main event, unfolding publicly before millions of people and thousands of foreign dignitaries. 

A Second Day of Mourning, and a Warning to Washington 

Ayatollah Khamenei’s death in February 2026 ended thirty-six years of his control over Iran’s clerical, military, and nuclear systems. But it did not settle the debate about what happens next. On Sunday, crowds assembled again at the Grand Mosalla prayer complex for a second day of ceremonies, chanting “Death to America” and “revenge, revenge” as the coffins of Khamenei and four family members killed with him stayed on display under glass. 

A eulogist told the crowd directly that people were there not just to mourn, but to demand payback. An 18-year-old student told reporters that Iranians should rise up and avenge their leader’s death. A 29-year-old grocery store clerk said he came to call for revenge and named President Trump as a target. These are not isolated opinions. Iranian officials designed the funeral to highlight this feeling, starting the six-day event on July 4, the 250th anniversary of the United States’ independence. Analysts see this as an intentional act of political theater, not a coincidence. 

Who Was Khamenei, and Why His Death Reshapes the Region 

To understand what is at stake, it helps to know who Khamenei was. He became supreme leader in 1989 after the death of revolutionary founder Ruhollah Khomeini, having already served as Iran’s president. Over thirty-six years, he shaped the Islamic Republic’s ideology and institutions: an anti-Western foreign policy supported by proxy militias in Lebanon, Iraq, Syria, and Yemen; a nuclear program that moved between talks and opposition; and a security state centered on the Islamic Revolutionary Guard Corps. 

He was killed in a coordinated strike that intelligence officials say used CIA location data shared with Israeli forces, hitting a Tehran compound where Khamenei was meeting his top military commanders. The US-Israeli strikes Iran carried out that Saturday morning killed not only Khamenei but Iran’s defense minister, the top IRGC commander, and the armed forces chief of staff in one blow, removing Iran’s senior military leadership in a single morning. More than 200 people died in the wider wave of strikes that day, according to Iran’s Red Crescent. Iranian state media also reported that dozens of children were killed when a strike hit a school in southern Iran, a claim U.S. Central Command said it was reviewing. 

The Succession Question Nobody Can Fully Answer 

Mojtaba Khamenei, the late leader’s son, was named his successor in March. He has not appeared in public since then. Many believe this is because he fears he could be Israel’s next target, not because of questions about his authority. His absence from his father’s funeral, while three of his brothers appeared to pray over the coffins, has provoked speculation about his health, his whereabouts, and how much control he really has. 

This uncertainty is important for Iran’s leadership succession in 2026 and for Tehran’s future dealings with Washington. A supreme leader who cannot appear in public cannot easily show strength at home. This may be why hardliners in Iran’s security establishment have used the funeral, instead of the new leader, to show resolve. Whether Mojtaba leads cautiously or tries to prove himself through confrontation will affect everything from nuclear talks to the risks around the Strait of Hormuz for years ahead. 

Ceasefire Diplomacy, Paused for a Funeral 

The timing is especially difficult for negotiators. For weeks, American and Iranian delegations have held indirect, technical talks in Doha, with Qatari and Pakistani officials mediating. They are working from a 14-point memorandum of understanding signed by Washington and Tehran on June 17. This agreement extended the fragile Iran-US war ceasefireby 60 days and covers reopening the Strait of Hormuz, releasing billions in frozen Iranian assets, and outlining a permanent deal on Iran’s nuclear program. 

Qatari and Pakistani mediators said this week that there has been “positive progress” on issues related to the memorandum. However, they also made it clear that the next round of talks will not happen until the funeral processions are over. Vice President JD Vance said the discussions in Doha were “going well,” but he did not rule out a return to full military action if the truce fails. This mix of reserved optimism and open threats has defined the ceasefire since its shaky start in April, when both sides first agreed to a two-week pause after months of missile attacks, a naval blockade, and several near-breakdowns. 

Domestic political pressure in Iran is the variable factor that mediators in Doha cannot control. After six days of organizing millions of people to chant for revenge, the regime will struggle to present any compromise on sanctions, uranium enrichment, or the Strait—as anything but surrender. Analysts observing the funeral say the government is using the mourning period to project a tough stance, even as its negotiators quietly continue talks with Washington. 

What the Oil Market Is Telling Us 

Markets have responded clearly to this risk. Brent crude, which went above $120 a barrel during the worst of the spring naval blockade, has since dropped sharply as hopes grew that the Strait of Hormuz, which carries about a fifth of the world’s oil and LNG, would reopen. In the days before the funeral, Brent traded in the low to mid-$70s, with WTI futures also falling from their wartime highs above $100. 

That decline shows the market betting the ceasefire will hold. It does not reflect certainty. Analysts covering the Iran supreme leader’s death, US war ceasefire negotiations on oil market stocks in the July 2026 period, have flagged that current prices may be overshooting to the downside, assuming a smoother and faster normalization of Gulf shipping than the security situation on the ground actually supports. Citi and Goldman Sachs both trimmed their third- and fourth-quarter Brent forecasts in recent weeks, but both banks also noted that any disruption tied to succession instability, funeral-driven unrest, or a breakdown in Doha talks could quickly reverse those gains. A single provocative incident near the Strait  an Iranian gunboat harassment, a stray missile, a hardliner faction acting without central authorization could send crude spiking again within a trading session. 

The Week Ahead 

Khamenei’s body will travel from Tehran to Qom, then to Najaf and Karbala in Iraq, before returning to Iran for burial in Mashhad on July 9. Each halt is another opportunity for mass mobilization, another set of images broadcast globally, and another test of whether grief curdles into pressure that Iran’s negotiators cannot resist. The Iran Ayatollah Khamenei funeral second day chants revenge killed US Israeli airstrike February 2026 story is, at its core, a story about whether a nation can mourn its way into war or negotiate its way past it and right now, both paths remain open. 

For executives with exposure to the Middle East and investors in energy markets, what happens on the streets of Tehran, Qom, and Mashhad in the coming days matters more than what is said in Doha. Diplomacy can survive a funeral, but it is much harder to survive when fifteen million people are calling for blood.

Source: U.S.-Iran Latest: 12-hour funeral procession through streets of Tehran for slain supreme leader underway