

Meta Q3 Earnings Tonight Are the First Hard Test of the AI Spend Story
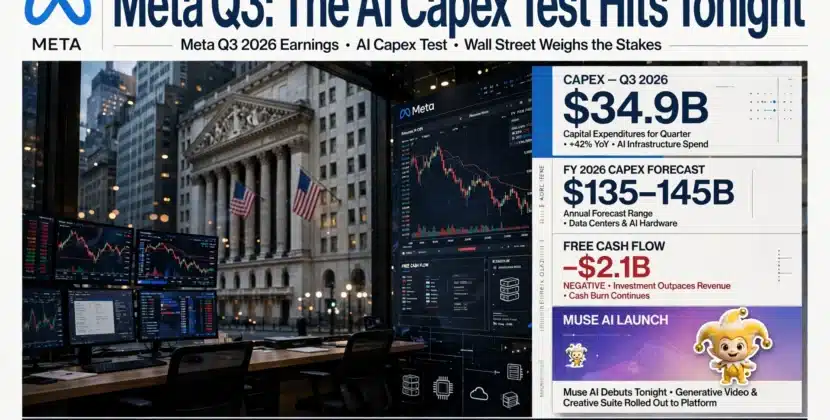
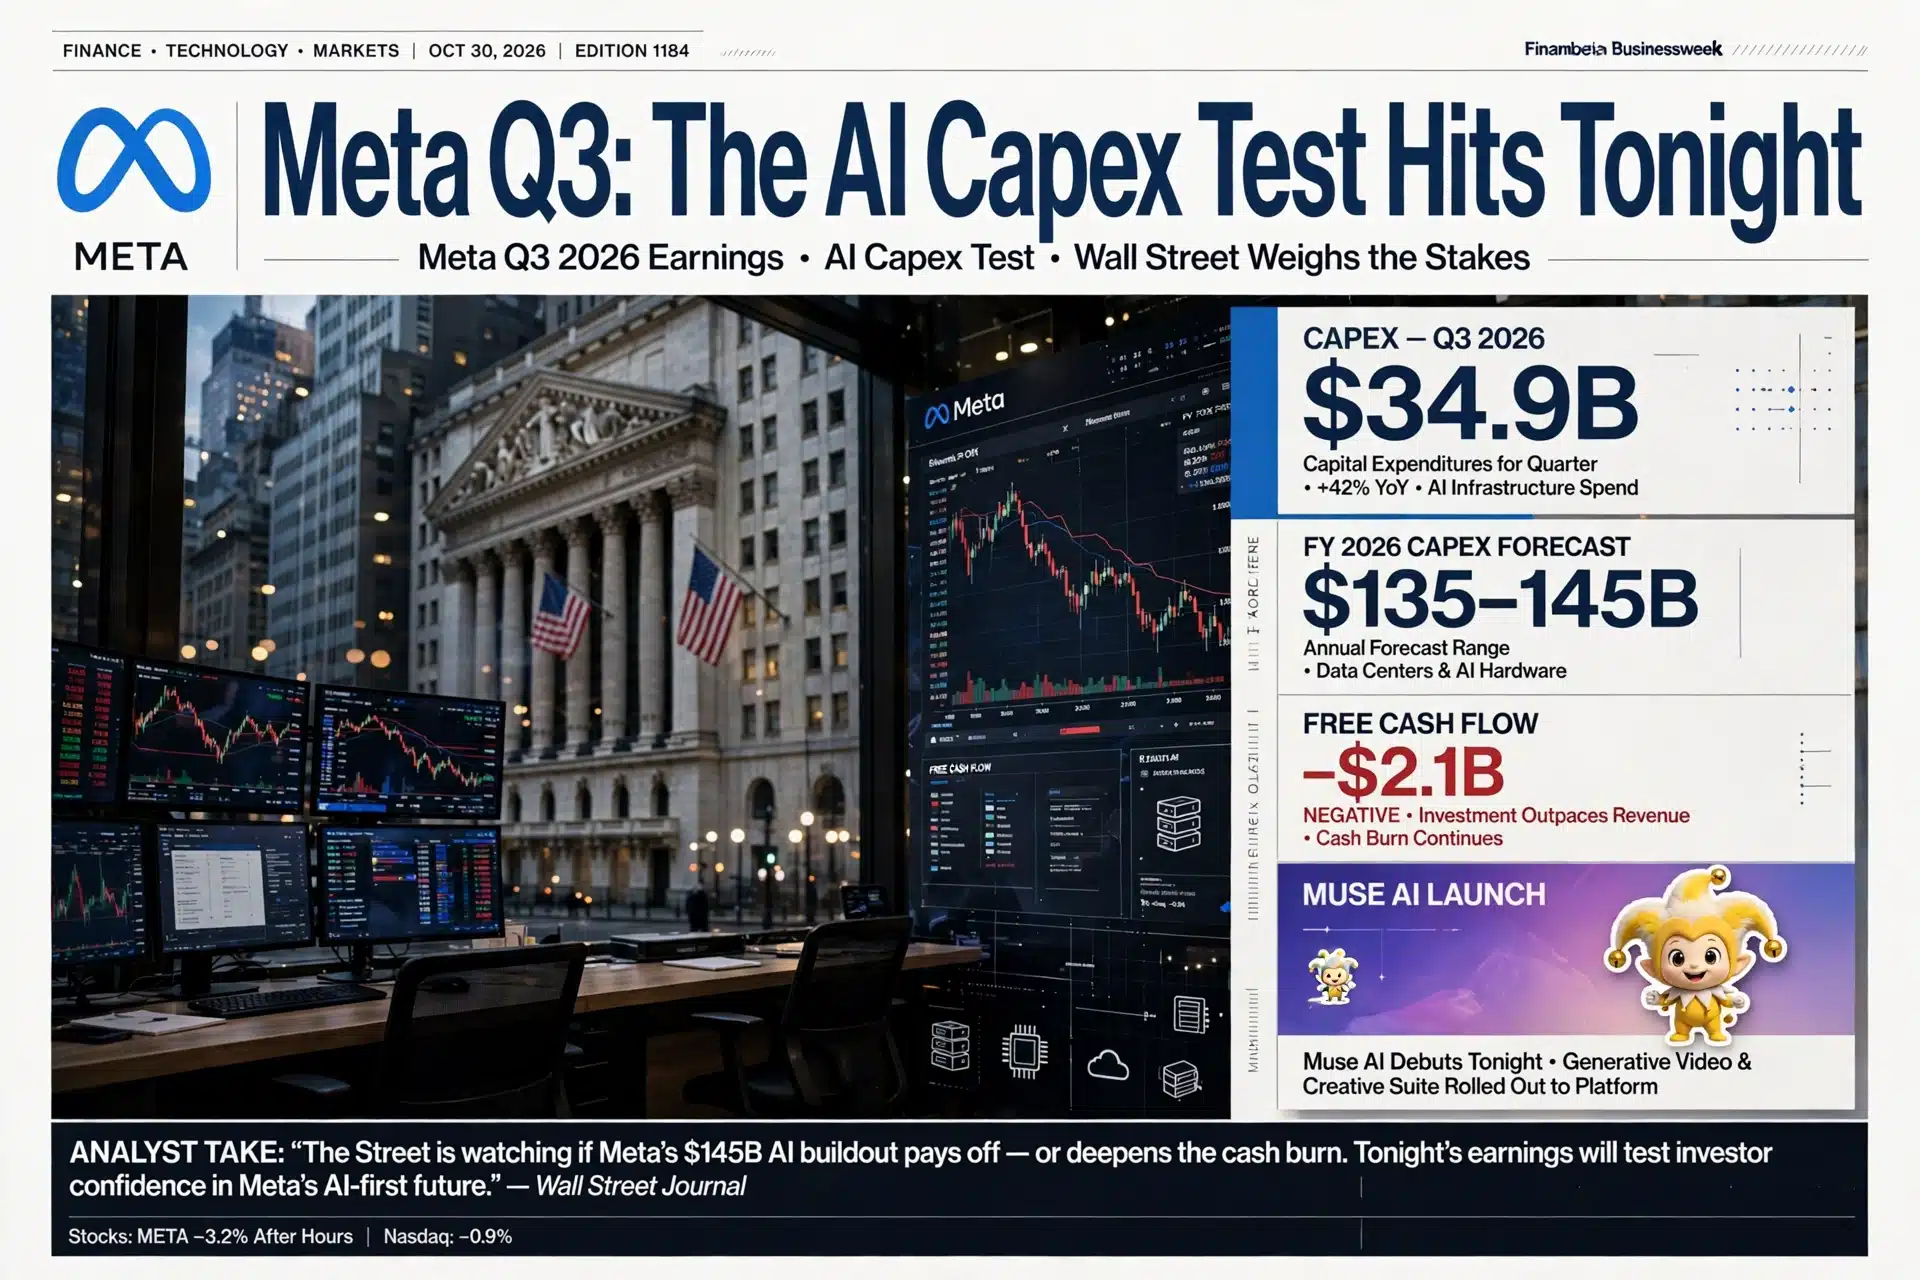
Meta reports Q3 2026 Meta Q3 earnings tonight, Wednesday, October 21, after the market close, and the print doubles as the first public verdict on whether Big Tech’s AI investment schedule can survive contact with free cash flow. Analysts expect about $63.3 billion in revenue, inside the company’s own $61 billion to $64 billion guidance, while the questions that matter sit below the revenue line: a roughly $10 billion legal accrual, a capital budget already at $130 billion to $145 billion for 2026, and the first 2027 capex number Meta has ever been expected to give in October. Traders have priced an expected move of about 6%.
Key Takeaways:
- – Meta reports Q3 2026 results after the close on Wednesday, October 21; consensus sits near $63.3 billion in revenue.
- – Bank of America cut its Q3 EPS forecast to $3.79 from $7.08 to reflect a roughly $10 billion legal accrual tied to a multistate settlement.
- – 2026 capex guidance stands at $130 billion to $145 billion, after two raises this year; BofA projects about $205 billion for 2027.
- – Q2 capex of $31.1 billion absorbed nearly all operating cash flow, leaving $784 million in free cash flow.
- – Implied move is around 6%; shares slid 8% to 10% after-hours following the Q2 report.
The Revenue Line Is the Easy Part
The top end hits its stride. Advertising remains the engine, and Bank of America forecasts Q3 ad revenue near $62.2 billion, up 24%, with its advertiser checks showing AI-based targeting lifting returns. The average analyst price target sits around $830, and Truist lifted its target to $1,000 on October 13. On revenue and user metrics alone, this should be a comfortable quarter: guidance already told investors what to expect, and nothing in the preview coverage suggests a demand problem. That is precisely why the market treats this report as a spending story rather than a sales story.
Capex Guidance Is the Real Headline
Meta started 2026 guiding capex to $115 billion to $135 billion, raised the range to $125 billion to $145 billion in April, and tightened it to $130 billion to $145 billion in July. Historically October is when the company lays out the next year’s plan, and this would be the first quarter in this AI cycle where the 2027 figure arrives inside the Q3 report. Analysts already model about $193 billion in capex for 2027, with Bank of America at $205 billion, and total expenses for 2026 guided at $165 billion to $169 billion. The asymmetry is uncomfortable: last October, Meta’s pointed-to-higher-spending report sent the stock down more than 10%, and nothing in this year’s spending curve suggests the direction reverses. Bears note that consensus EPS has been cut about 16% over the past 90 days and free cash flow is expected to stay negative through 2027, so a bigger-than-expected 2027 number lands on an already thin margin story.
The Legal Charge and the Numbers Behind It
The quarter includes a one-off that will scramble headline optics. Bank of America lowered its Q3 EPS forecast to $3.79 from $7.08 to account for a roughly $10 billion legal accrual tied to a multistate settlement. Underneath, the economics of the settlement are larger: tastylive’s preview pegs the total at roughly $18 billion over ten years, with about $5.3 billion contingent on whether TikTok and YouTube take comparable steps. Expect management to guide around the accrual with adjusted figures of the release. Investors watching the underlying business should compare operating margin against Q2’s 31%, down from 43% a year earlier, because that spread is where AI spending shows up when it outruns ad growth.
The Muse Variable
Meta’s AI agent Muse became the bull case after its September 8 debut; the stock rallied about 27% in September, its strongest month since November 2022, and Meta followed up on October 12 with Muse Wonder and Muse Wonder Full before the print. Skeptics want proof of usage depth rather than launch-week downloads: Morgan Stanley flagged retention around 20%, while Guggenheim emphasizes fast-rising daily users. The quarter captured only about three weeks of Muse revenue, so guidance will matter more than the reported quarter. One early monetization marker to watch is Family of Apps other revenue, which hit $1 billion in Q2, up 73%, led by WhatsApp paid messaging; similar acceleration would corroborate the AI monetization narrative Meta needs to justify the capex line.
How to Watch the After-Hours Reaction
Three checkpoints, in order. First, capex: any 2027 number at or above consensus ($193 billion to $205 billion was already the range) removes the roses; a refusal to guide reads as uncertainty and also trades lower, as it did in 2025. Second, adjusted EPS versus the $3.79 legal-charge-inclusive figure, which tells you whether operations beat while the charge distractions or the business itself slipped. Third, Muse metrics in the call, particularly any retention or daily-user figures Meta volunteers unprompted, because the stock’s October pullback to around $701 reflects a market that has started asking what the agent actually earns. With Big Tech capex now running near $750 billion industry-wide this year, up from about $410 billion, Meta’s evening verdict lands on a sector already defending its investment math.
What Happens Next
Whatever the print, the next leg of the story is structural. If the 2027 capex guide comes in high with a credible Muse monetization slide behind it, Meta re-earns its premium and the AI trade gets its first clean earnings-season vindication this cycle. If the guide comes in high without an answer on agent revenue, expect the Q2 after-hours playbook to repeat: estimates cut, free-cash-flow math dissected on every earnings call through spring. And if Meta surprises low for a change, it will be because agent revenue arrived faster than the bill, an outcome almost nobody is positioned for, which is exactly why tonight’s implied 6% move is considered cheap by options desks. US investors will hear the answer within hours of this article; the spending trajectory, not the EPS print, is the number that decides Meta’s next twelve months.
Frequently Asked Questions
When does Meta report Q3 2026 earnings?
Meta reports after market close on Wednesday, October 21, 2026, alongside Tesla, IBM, Texas Instruments and Lam Research in the same after-hours block.
Why is Meta’s Q3 EPS expected to be so low?
Bank of America cut its forecast to $3.79 from $7.08 mainly to reflect a roughly $10 billion legal accrual tied to a multistate settlement, not an operational miss.
What capex number should investors watch for 2027?
Analysts model about $193 billion, with Bank of America at $205 billion; Meta has historically used the October call to lay out the next year’s plan, making tonight’s guidance the key event.
Sources:
- https://www.tastylive.com/news-insights/meta-earnings-preview-muse-ai-capex-and-q3-outlook
- https://finance.biggo.com/news/9777b94e-0963-440a-b16e-d4adf2f531d5
- https://www.newsquawk.com/headlines/daily-us-earnings-estimates—21st-october-2026-dhr-tmo-t-pm-cme-abt-nee-meta-txn-lrcx-ibm-tsla
- https://www.investors.com/research/investing-action-plan/meta-tesla-spacex-earnings-season-high-gear/