Galaxy Ring Sleep Apnea Detection Arrives in the US

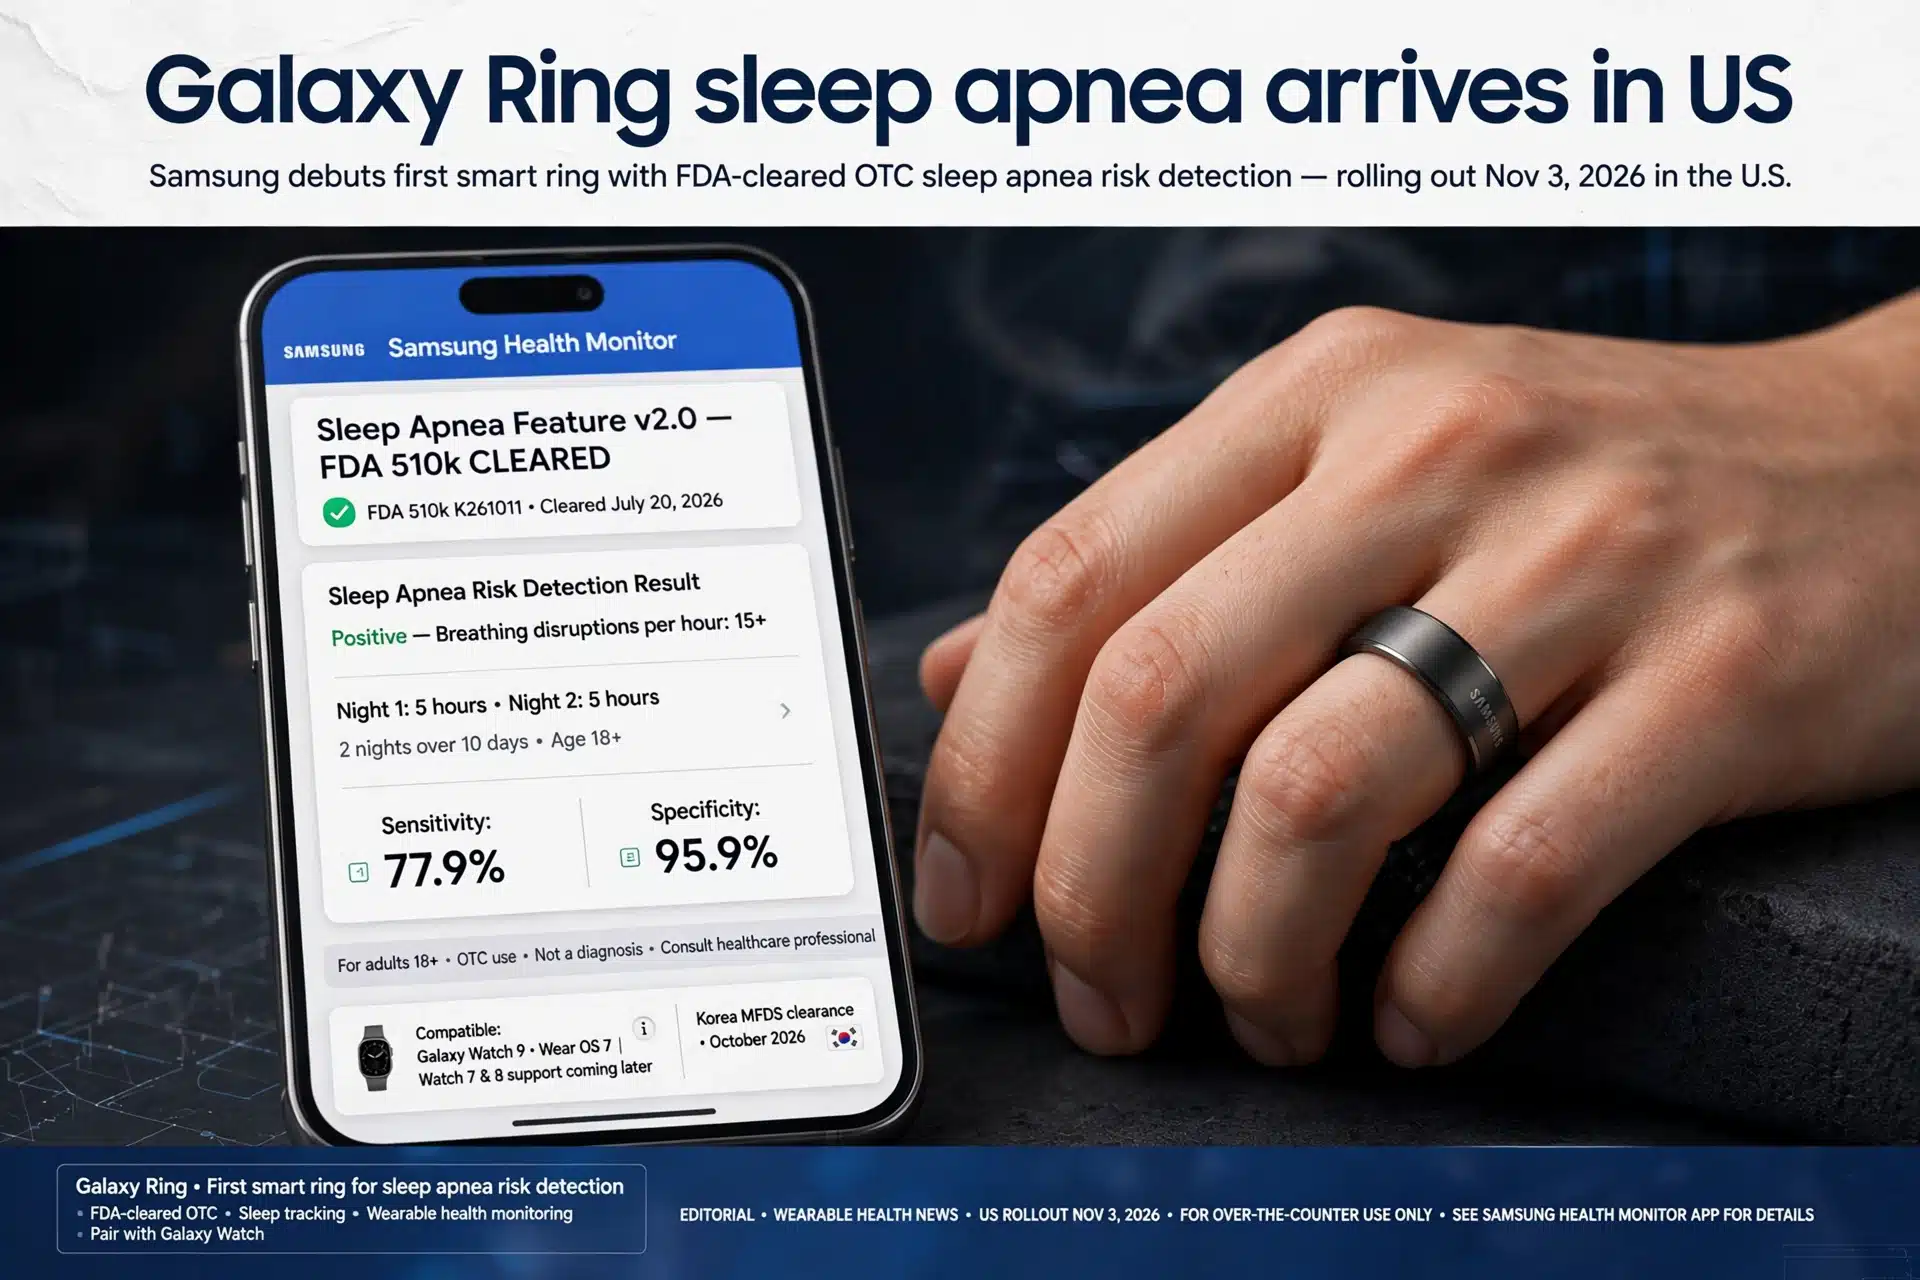
Samsung’s Galaxy Ring can now screen for signs of sleep apnea in the United States. The company announced on November 3, 2026 that its upgraded Sleep Apnea feature is available on Galaxy Ring and Galaxy Watch, following FDA clearance in July, and Samsung says it is the first company to bring FDA-cleared over-the-counter sleep apnea risk detection to a smart ring.

Key Takeaways:

  • – The feature went live in the US on November 3, 2026, after FDA clearance in July and approval from Korea’s MFDS in October.
  • – It needs two nights of valid sleep data inside a 10-day window, collected through the Samsung Health Monitor app.
  • – The upgrade reports the level of breathing disruptions rather than a simple high-or-low risk flag.
  • – It is a screening tool, not a diagnosis, and it is not intended for people already diagnosed with sleep apnea.

What Samsung announced on November 3

Samsung’s US newsroom published the availability notice on November 3, describing the release as the point at which the company becomes the first to offer FDA-cleared, over-the-counter sleep apnea risk detection on a smart ring. The same announcement confirms approval from Korea’s Ministry of Food and Drug Safety, which clears the way for expansion beyond the United States.

The timing matters for anyone shopping this month. The hardware is not new. What changed is the software pathway: the algorithm that turns overnight pulse and movement data into a breathing-disruption report is now cleared for use on the ring form factor, not just on watches.

How the ring detects sleep apnea

The Galaxy Ring does not measure airflow or blood oxygen the way a sleep lab does. It tracks nighttime vitals and passes them to an algorithm that estimates how often breathing is disrupted, then reports a risk level. The updated version goes further than the original by describing the level of breathing disruptions detected, per Samsung’s release, rather than only flagging whether signs of moderate to severe apnea appeared.

Engadget reports that the feature can indicate mild, occasional or frequent sleep apnea, and that it requires at least five hours of sleep on two nights within a 10-day period to produce a result. Results appear in the Samsung Health Monitor app, which needs a compatible Galaxy phone paired to the ring. The low data requirement is deliberate: two usable nights, not a month of perfect wear, is enough to generate a reading.

Why the FDA clearance matters

The original Sleep Apnea feature received FDA De Novo authorization in February 2024, the first of its kind for a wearable designed to detect signs of moderate to severe sleep apnea. De Novo is the pathway the FDA uses for novel, low-to-moderate-risk devices with no substantially equivalent predecessor, and it establishes a classification other products can later follow.

The July 2026 clearance covers the upgraded algorithm, and the November 3 announcement is the commercial launch that follows. That sequence, authorization first and availability second, is why the feature is described as over-the-counter: adults can enable it without a prescription, in the same way they can use an at-home blood pressure cuff. The distinction matters because over-the-counter screening tools are regulated on accuracy claims, not on the promise of a diagnosis.

Why this lands with US readers

Sleep apnea is common and mostly invisible. The American Academy of Sleep Medicine estimates that nearly 30 million Americans have obstructive sleep apnea and that about 80 percent of cases are undiagnosed, with untreated cases linked to cardiovascular disease, stroke, diabetes and depression. A 2025 study published in Respiratory Medicine put estimated prevalence among US adults at 83.7 million people, or 32.4 percent, using a broader scoring threshold.

Those numbers explain the commercial logic. A ring that people already wear for sleep tracking can surface a suspicion of apnea without a referral, a night in a lab or a wait for a specialist. Samsung is explicit that the feature is meant to start a conversation with a clinician rather than replace one, which is the correct framing for a screening product with a consumer price tag.

What it costs and who can use it

Nothing about the feature requires a new subscription beyond the hardware. It runs on the Galaxy Ring and on Galaxy Watch9 with Wear OS 7.0 or later, according to GSMArena, with Galaxy Watch7 and Watch8 slated to receive it through software updates. Users must be 18 or older.

The ring itself remains the cost of entry, and the feature is not sold separately. For US buyers comparing options, the practical question is whether they already own a compatible Galaxy phone, because the Health Monitor app will not run without one. That requirement keeps the feature inside Samsung’s ecosystem in a way watch-based competitors such as Apple and Google are not constrained by, and it is the main reason the launch is unlikely to pull iPhone users across on its own.

The limits you should know

Three limits are worth stating before anyone treats a reading as a diagnosis. First, the feature is not intended for people who have already been diagnosed with sleep apnea, so it is a first-look tool rather than a monitoring tool for patients under treatment. Second, it depends on wear compliance: two valid nights in ten days sounds easy until a user forgets the ring or sleeps less than the required hours.

Third, a consumer device cannot distinguish central sleep apnea from obstructive sleep apnea, cannot grade severity the way a polysomnogram does, and cannot prescribe therapy. Samsung’s own materials say only a physician can diagnose the condition. Anyone who receives a frequent-disruption result should treat it as a reason to book an appointment, not as a result to act on alone.

This article is not medical advice.

What happens next

The near-term story is watch rollout. Galaxy Watch7 and Watch8 owners are waiting on the software update that enables the upgraded algorithm, and Samsung has said it will keep expanding availability by country. The larger story is regulatory: once one wearable maker has an over-the-counter clearance for breathing-disruption detection, competitors face a clearer path and a clearer benchmark.

For US consumers, watch the insurance conversation rather than the hardware. Screening features create demand for follow-up testing, and how payers treat a positive result from a consumer wearable will determine whether this becomes a genuine front door to care or another data point people ignore. Samsung has not announced any reimbursement arrangement, and none should be assumed.

Frequently Asked Questions

Is the Galaxy Ring sleep apnea feature FDA cleared?

Yes. Samsung says the upgraded feature received FDA clearance in July 2026, building on the original De Novo authorization granted in February 2024. It is cleared for over-the-counter sleep apnea risk detection, not for diagnosis.

How many nights of data does it need?

Two nights of valid sleep data within a 10-day period, with each night lasting at least five hours. Results appear in the Samsung Health Monitor app on a paired Galaxy phone.

Can the Galaxy Ring diagnose sleep apnea?

No. It reports a risk level based on breathing disruptions observed during sleep. Only a clinician can diagnose sleep apnea, and Samsung states the feature is not intended for people who already have a diagnosis.

Bottom line

The Galaxy Ring sleep apnea feature turns a piece of jewelry into a screening device for a condition that affects roughly 30 million Americans and goes undiagnosed in most of them. It is cleared, it is live, and it needs two good nights, a Galaxy phone and a doctor to act on the result.

Sources:

Anthropic IPO Filing: $17B Quarter, $895B Compute Bill

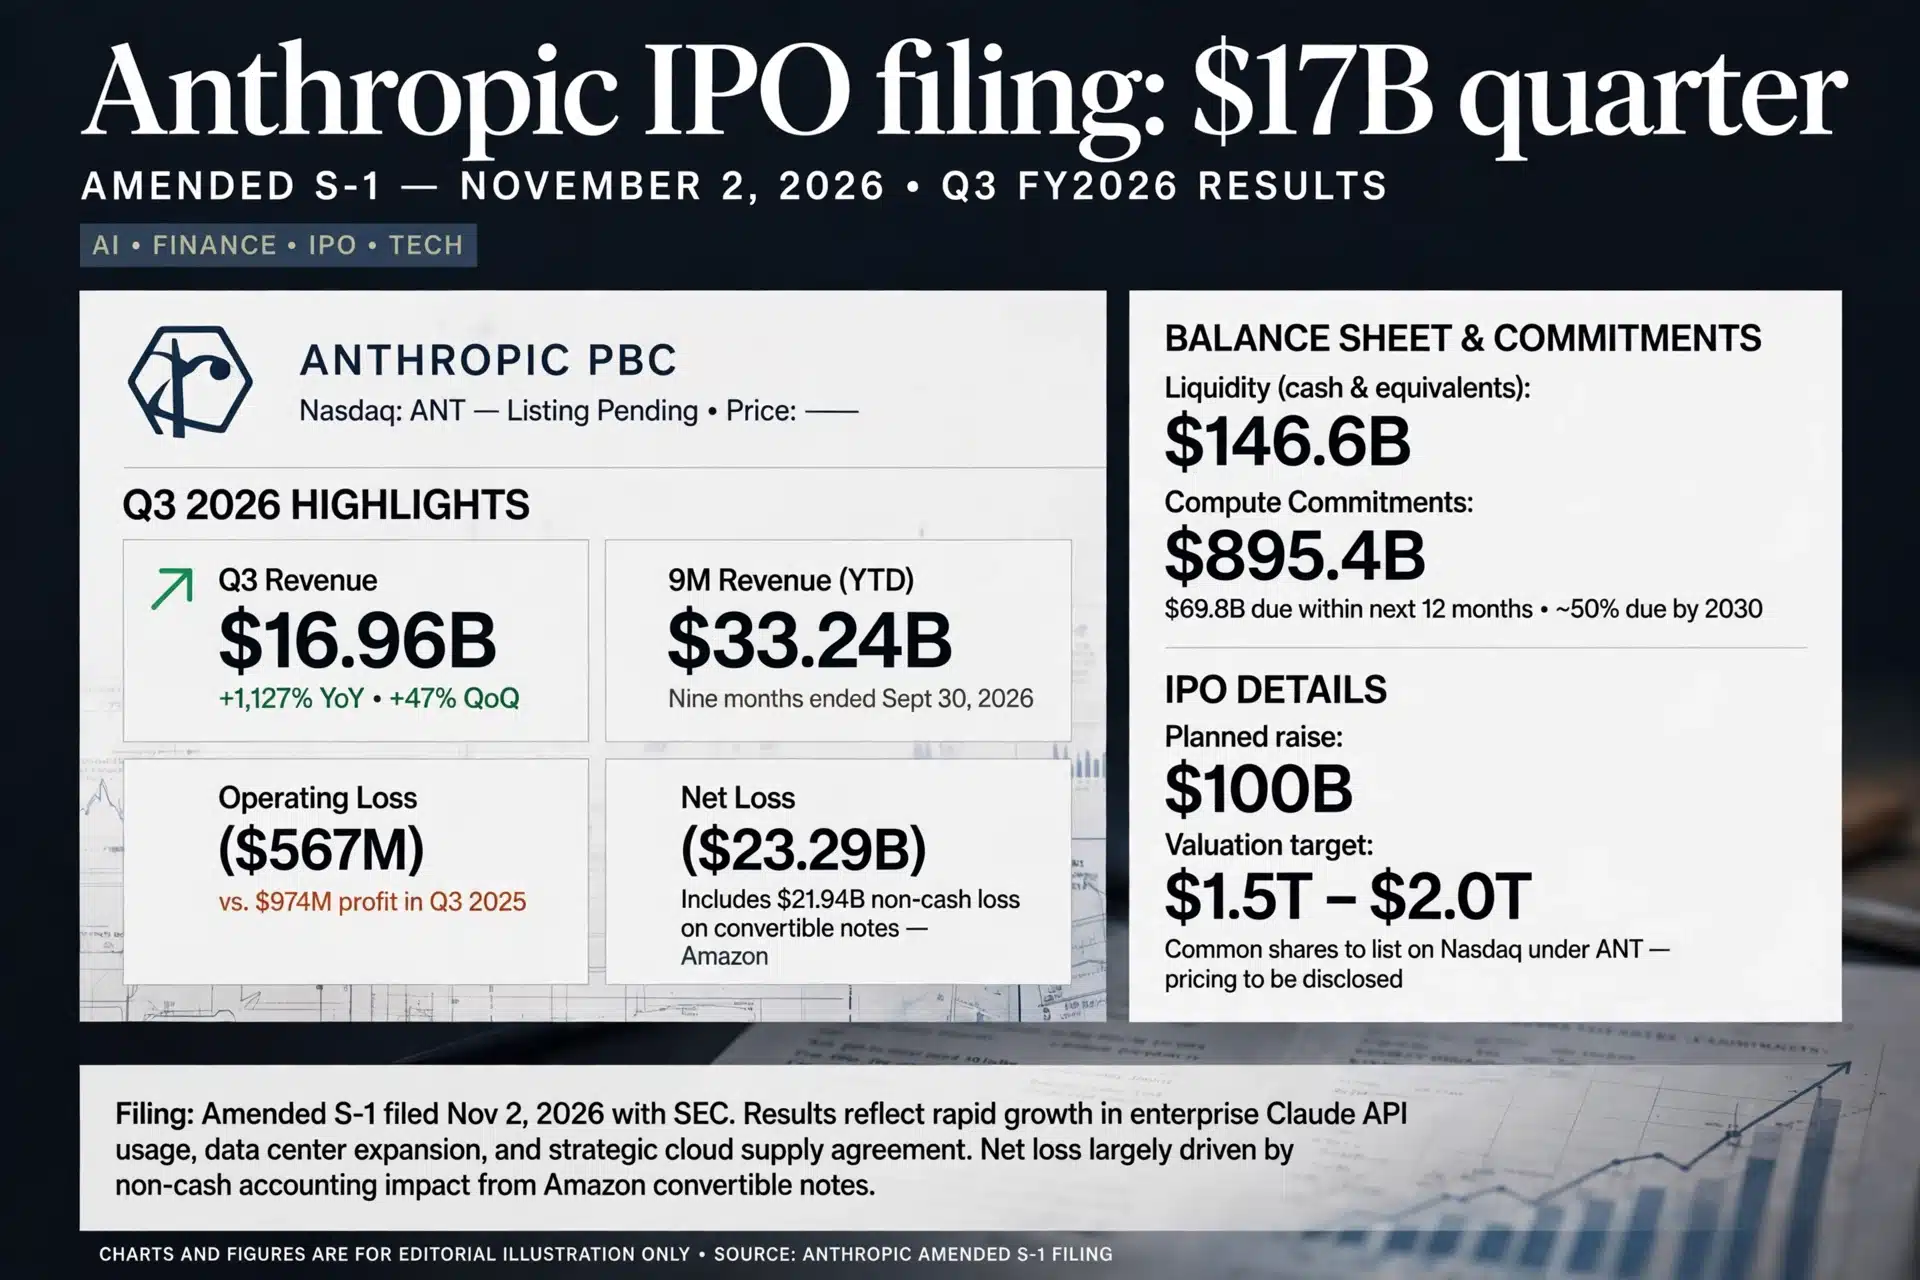
The Anthropic IPO filing now has numbers in it. An amendment to the company’s Form S-1, filed with the Securities and Exchange Commission on November 2, 2026, reports $16.96 billion of revenue for the quarter ended September 30 and about $895.4 billion in purchase commitments and leases, almost all of it for computing power. For US readers, the document is the clearest public look yet at what a frontier AI lab earns and what it has already promised to spend.

Key Takeaways:

  • – Third-quarter revenue reached $16.96 billion, up 1,127 percent from a year earlier and about 47 percent from the second quarter.
  • – The quarter produced a $567 million operating loss after $974 million of operating income in the prior quarter.
  • – Anthropic has committed roughly $895.4 billion to compute and infrastructure, with about $69.8 billion due in the next 12 months.
  • – The filing still leaves the share count and price range blank, so no valuation is official yet.

What the amended filing actually discloses

Anthropic filed its original S-1 in late October with several cover-page items and quarterly figures left blank. Amendment No. 1 fills in the September quarter and totals the company’s future obligations for the first time. CNBC reported that the amendment landed two days after the first filing became public, and that it puts nine-month revenue at $33.24 billion, up roughly 1,200 percent year over year.

The filing describes an initial public offering of Class A common stock, with Goldman Sachs and Morgan Stanley named as prospectus contacts and a planned listing on the Nasdaq Global Select Market under the ticker ANT. What it does not contain matters just as much. There is no price range, no share count and no listing date, which means the market has a revenue line and a spending schedule but no official valuation to argue about yet.

Growth is still steep, but the curve bent

A 1,127 percent year-over-year increase is not a normal number, and it is worth stating plainly: Anthropic’s quarterly revenue went from $1.38 billion to $16.96 billion in twelve months. Fortune noted that the pace still represents a slowdown in sequence, because the second quarter grew about 144 percent over the first while the third grew about 47 percent over the second.

That deceleration is the part investors will study. Every fast-growing company eventually trades a vertical line for a curve, and the question is where the curve flattens. At $16.96 billion a quarter, Anthropic is running at a scale that would place it among the largest software businesses in the United States if the rate holds. At the same time, a company cannot grow 47 percent per quarter forever, and the filing gives the first hard evidence of where the bend starts.

The compute bill is the story

The single most revealing line in the document is the commitment total. Anthropic discloses about $895.4 billion in purchase commitments and leases, substantially all related to compute and infrastructure. Roughly $447.5 billion is expected to be incurred before the end of 2030, about $69.8 billion falls due in the twelve months after September 30, and the longest commitments run to 2045.

Those are not expenses booked this quarter. They are contracts. The four largest counterparties disclosed in press coverage of the filing are Broadcom at roughly $161 billion, Google at $121 billion, SpaceX’s AI unit at up to $120.5 billion and Amazon at $110 billion. For US readers, this is the mechanism behind the data center buildout showing up in electricity rates, construction permits and local zoning fights: a single company signing multi-decade infrastructure contracts at a scale normally associated with governments.

A loss again, for two specific reasons

Anthropic reported a $567 million operating loss for the quarter, reversing $974 million of operating income in the second quarter. The filing attributes the swing to two items: about $5.0 billion of compute bought through short-term commitments, which the company says currently costs significantly more than capacity under multi-year contracts, and $2.0 billion of non-cash charges tied to an employee donation matching program.

Compute and infrastructure costs reached $9.86 billion in the quarter, up 382 percent from $2.05 billion a year earlier. The company also reported a net loss of $23.29 billion against $12.14 billion a year earlier, a figure shaped heavily by non-cash accounting rather than by cash leaving the business. On an adjusted basis, Anthropic reported $2.5 billion of operating income, up from a $1.3 billion adjusted loss a year earlier. The company ended the quarter with $95.6 billion of cash and $36.3 billion of short-term investments, or $131.8 billion combined.

What it means for US investors

Three practical points follow from the filing. First, revenue quality looks strong relative to cost of goods: compute costs grew 382 percent while revenue grew 1,127 percent, a gap that favors gross margin over time if it persists. Second, the balance sheet can absorb the buildout for now, because $131.8 billion of liquid resources covers the near-term commitment schedule several times over.

Third, the credit picture is not settled. The Financial Times reported that Anthropic is expected to receive a high-yield, or junk, rating from credit agencies ahead of the listing, according to TechCrunch. A sub-investment-grade rating does not block an IPO, but it does raise the cost of any borrowing layered on top of the equity raise, and it tells retail investors that bond markets view the compute commitments as leverage-like obligations rather than ordinary operating costs.

What happens next

The next milestone is a price range in a further amendment, which will convert commitments into a valuation the public can test. After that comes the roadshow, where institutional buyers will push on exactly the two numbers this filing exposes: how much of the growth is durable and how much of the $895.4 billion can be renegotiated if demand slows.

One unresolved item sits outside the financials. The same filing warns that the company may be very close to recursive self-improvement, the point at which a model can meaningfully improve itself, per TechCrunch. That disclosure will follow the company into investor meetings and likely into regulatory questions after listing. For US readers, the practical takeaway is narrower: the AI buildout is now financed with contracts that outlast most mortgages, and the companies signing them are asking public markets to co-sign.

Frequently Asked Questions

How much revenue did Anthropic report in the third quarter of 2026?

Anthropic reported $16.96 billion of revenue for the three months ended September 30, 2026, according to Amendment No. 1 to its Form S-1. That is up 1,127 percent from $1.38 billion a year earlier and about 47 percent from $11.56 billion in the second quarter.

Is Anthropic profitable?

Not on a reported basis. The third quarter produced a $567 million operating loss and a $23.29 billion net loss. On an adjusted basis the company reported $2.5 billion of operating income, and it held $131.8 billion in cash and short-term investments at quarter end.

When will Anthropic stock start trading?

No date has been set. The amended filing leaves the price range, share count and listing date blank. The company intends to list Class A common stock on the Nasdaq Global Select Market under the ticker ANT.

Bottom line

The Anthropic IPO filing converts a private AI story into a public financial one. Revenue is enormous and still compounding, the operating result swings on how compute is bought rather than on demand, and roughly $895.4 billion of contracted infrastructure sits underneath it all. Until a price range appears, US investors are reading the balance sheet without knowing the sticker price.

Sources:

Binance Crypto Hack Drains $6.3 Billion, the Largest Theft on Record

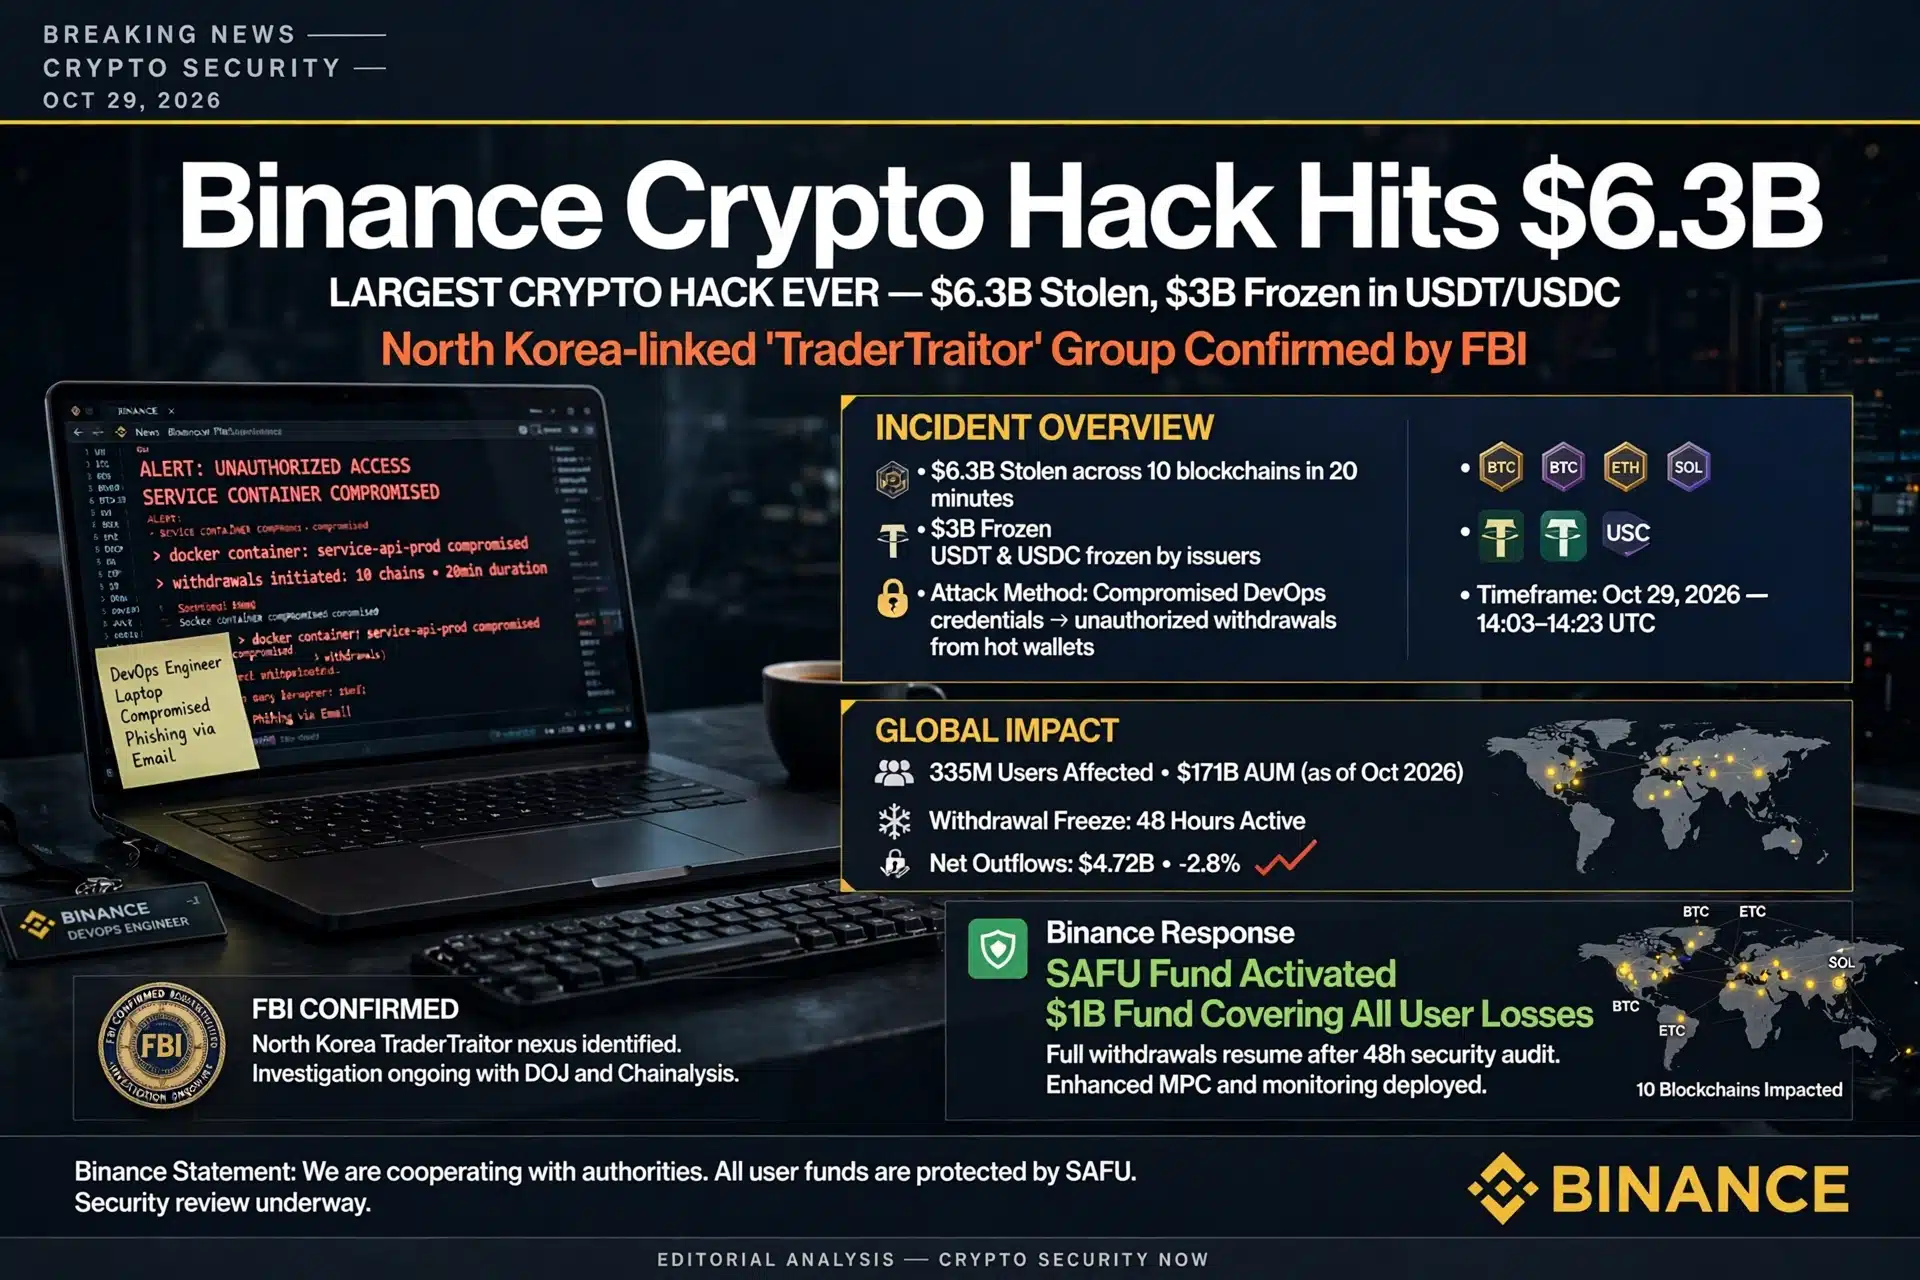
The Binance crypto hack confirmed on October 29, 2026 removed roughly $6.3 billion across ten blockchains in about 20 minutes, making it the largest cryptocurrency theft ever recorded, and the Binance crypto hack now has the FBI, the US Secret Service and blockchain intelligence firms tracing funds ahead of a phased withdrawal restart. Binance says no wallet private keys leaked and that it will cover every loss through its SAFU fund, and by early October 30 roughly $2.7 billion was already frozen. US holders of Binance.US assets were not directly hit, but the event still reshapes how US regulators, banks and exchanges think about custody risk.

Key Takeaways:

  • – Binance suspended withdrawals across multiple networks on October 29, 2026 after on-chain analysts flagged massive outflows; founder Changpeng Zhao called it a hack while it was underway.
  • – Total losses are about $6.3 billion per TRM Labs, dwarfing the February 2025 Bybit theft of $1.5 billion that previously held the record.
  • – Binance’s preliminary finding: a compromised DevOps engineer’s laptop gave attackers access to a service container that could submit unauthorized withdrawal transactions.
  • – Tether froze about $1.56 billion in USDT and Circle froze roughly $800 million in USDC; TRM counted about $2.7 billion frozen by 00:30 UTC October 30.
  • – TRM Labs attributes the attack with high confidence to TraderTraitor, a North Korean Lazarus-linked group; Binance set aside $5 billion and bought another $1.34 billion in tokens to cover users.

What happened on October 29

The collapse unfolded in public. Wallet-draining reports escalated through the day until Binance paused withdrawals on multiple networks and stated that user funds were completely safe, a stability message it repeated as the outflow total grew. Zhao’s blunt acknowledgment that it looked like a hack on Binance came before the exchange had ruled one out, reflecting how visible the on-chain drains already were. Within the first movement window, the attacker moved the entire haul across ten blockchains in roughly 20 minutes, a speed made possible by the exchange’s own hot-wallet signing infrastructure, which had accepted the theft transactions as valid.

The technical heart of the case, per TRM Labs’ on-chain review, is subtle. On Ethereum the attackers used a batch of 50 pre-signed delegations from a Binance hot wallet, submitted under the EIP-7702 delegation mechanism, with one matching the target at execution time, plus validly signed transactions on the nine other chains. The implication researchers draw is that the attacker could induce Binance’s hot-wallet signing system to sign arbitrary transactions, an infrastructure compromise far deeper than a leaked key.

How the attackers got in

Binance’s own preliminary finding points at an entry point most US companies will recognize: a compromised DevOps engineer’s laptop. From that machine the intruder reached a service container and submitted unauthorized withdrawal transactions. This is the same opening move that flattened major US retailers and hospitals over the past five years, and it converts the hack from a crypto puzzle into a classic enterprise security incident with a cryptographic tail. Binance’s extraction playbook mirrors that too, freezing detected chains where issuers control tools, compensating directly, and publishing a proof of reserves to rebuild trust.

The “no private keys leaked” claim matters for victims, and Binance has repeated it along with its full-coverage commitment. The exchange says it set aside $5 billion and bought an additional $1.34 billion in tokens to make depositors whole through the SAFU emergency facility, and it planned to restore withdrawals in phases within roughly 34 hours, according to its October 30 update and subsequent reporting.

Who did it and what froze

Attribution is unusually convergent. TRM Labs assigns the operation to TraderTraitor, the North Korean Lazarus-umbrella grouping responsible for some of history’s largest exchange thefts, with high confidence, citing on-chain and off-chain indicators that mirror its prior work on Bybit and the KelpDAO case from April 2026. Chainalysis’s chief executive Jonathan Levin concurred publicly, and per reporting other independent trackers reached the same conclusion. Binance has not officially named a culprit, and no agency has formally done so either.

Freezing raced the laundering money. Tether froze about $1.56 billion of USDT, Circle froze roughly $800 million of USDC, and Arbitrum’s security council siphoned some $30 million out of an attacker-controlled wallet on its chain before the attackers could consolidate it. TRM’s tally put about $2.7 billion immobilized by early October 30 UTC. The unfrozen remainder is the hard problem: researchers estimate the thieves still hold over 420,000 ETH and 18,270 BTC, worth about $2.4 billion, which no issuer can freeze, and they sold the seized stablecoins at discounts of more than 10 percent as they converted into those harder assets.

What it means for US holders and regulation

The direct US financial exposure is limited because Binance.US, the domestic-facing platform, operates separately, but the knock-on effects reach US wallets three ways. First, the frozen reserve machinery that absorbed the loss is paid for by the exchange’s balance sheet, which raises systemic questions about whether exchange theft at scale is insurable at all. Second, the FBI and Secret Service are working with Binance on tracing, which widens law enforcement pressure on the North Korean cyber program Washington has long cited as a sanctions-evasion engine. Third, the public word on attribution arrived on October 30 when the President, asked about the hack in the Oval Office, said the US was looking into North Korea’s involvement but that the country did not know yet who was responsible, while noting Binance said it planned to make users whole.

The event also compresses the security debate for everyday US crypto users. Self-custody removes exchange-platform risk but concentrates personal key risk, which remains the larger killer of small-investor funds; the Bybit lesson applies identically here, that hardware-secured self-custody of meaningful holdings and minimal exchange balances are the conservative posture.

What happens next

Watch the phased withdrawal restart, promised within about 34 hours of the pause, and the updated proof of reserves Binance said it would publish; both are direct evidence for the “funds are safe” claim. The laundering chase will run for months through mixers, bridges and OTC desks, and the recoverable share of the unfrozen $2.4 billion depends on cooperation from market makers and law-enforcement pressure on intermediaries. A confirmed attribution to North Korean operators will feed the ongoing case for harder network-level defenses against a state that now has benchmark-setting heists in 2025 and 2026. For Congress, the immediate deliverable is custody and financial-incident reporting standards that make a DevOps-laptop compromise less likely to become a $6.3 billion customer loss at any capital markets venue users rely on.

Frequently Asked Questions

How much did the Binance hack steal?

About $6.3 billion per TRM Labs, extracted from Binance wallets across ten blockchains in roughly 20 minutes on October 29, 2026, exceeding the February 2025 Bybit theft of $1.5 billion that had been the largest on record.

Is it safe to leave funds on Binance?

Binance states user funds are safe, says no wallet private keys leaked, and says SAFU plus corporate funds will cover all losses, with withdrawals resuming in phases. The event nonetheless demonstrates that exchange operational security is a single point of failure, so the conservative posture most security researchers repeat is to hold long-term assets in self-custody and keep only working balances on exchanges.

Who hacked Binance in October 2026?

Blockchain intelligence firm TRM Labs attributes the theft with high confidence to TraderTraitor, a North Korean Lazarus-linked group, citing on-chain and off-chain indicators matching its prior operations; Chainalysis’s chief executive and other trackers independently concur. Binance has not officially assigned blame, and no government has formally named a culprit.

Sources:

https://sg.finance.yahoo.com/news/trump-responds-binance-hack-001031190.html

AMRAAM Production Japan Deal Adds a Second Allied Missile Factory

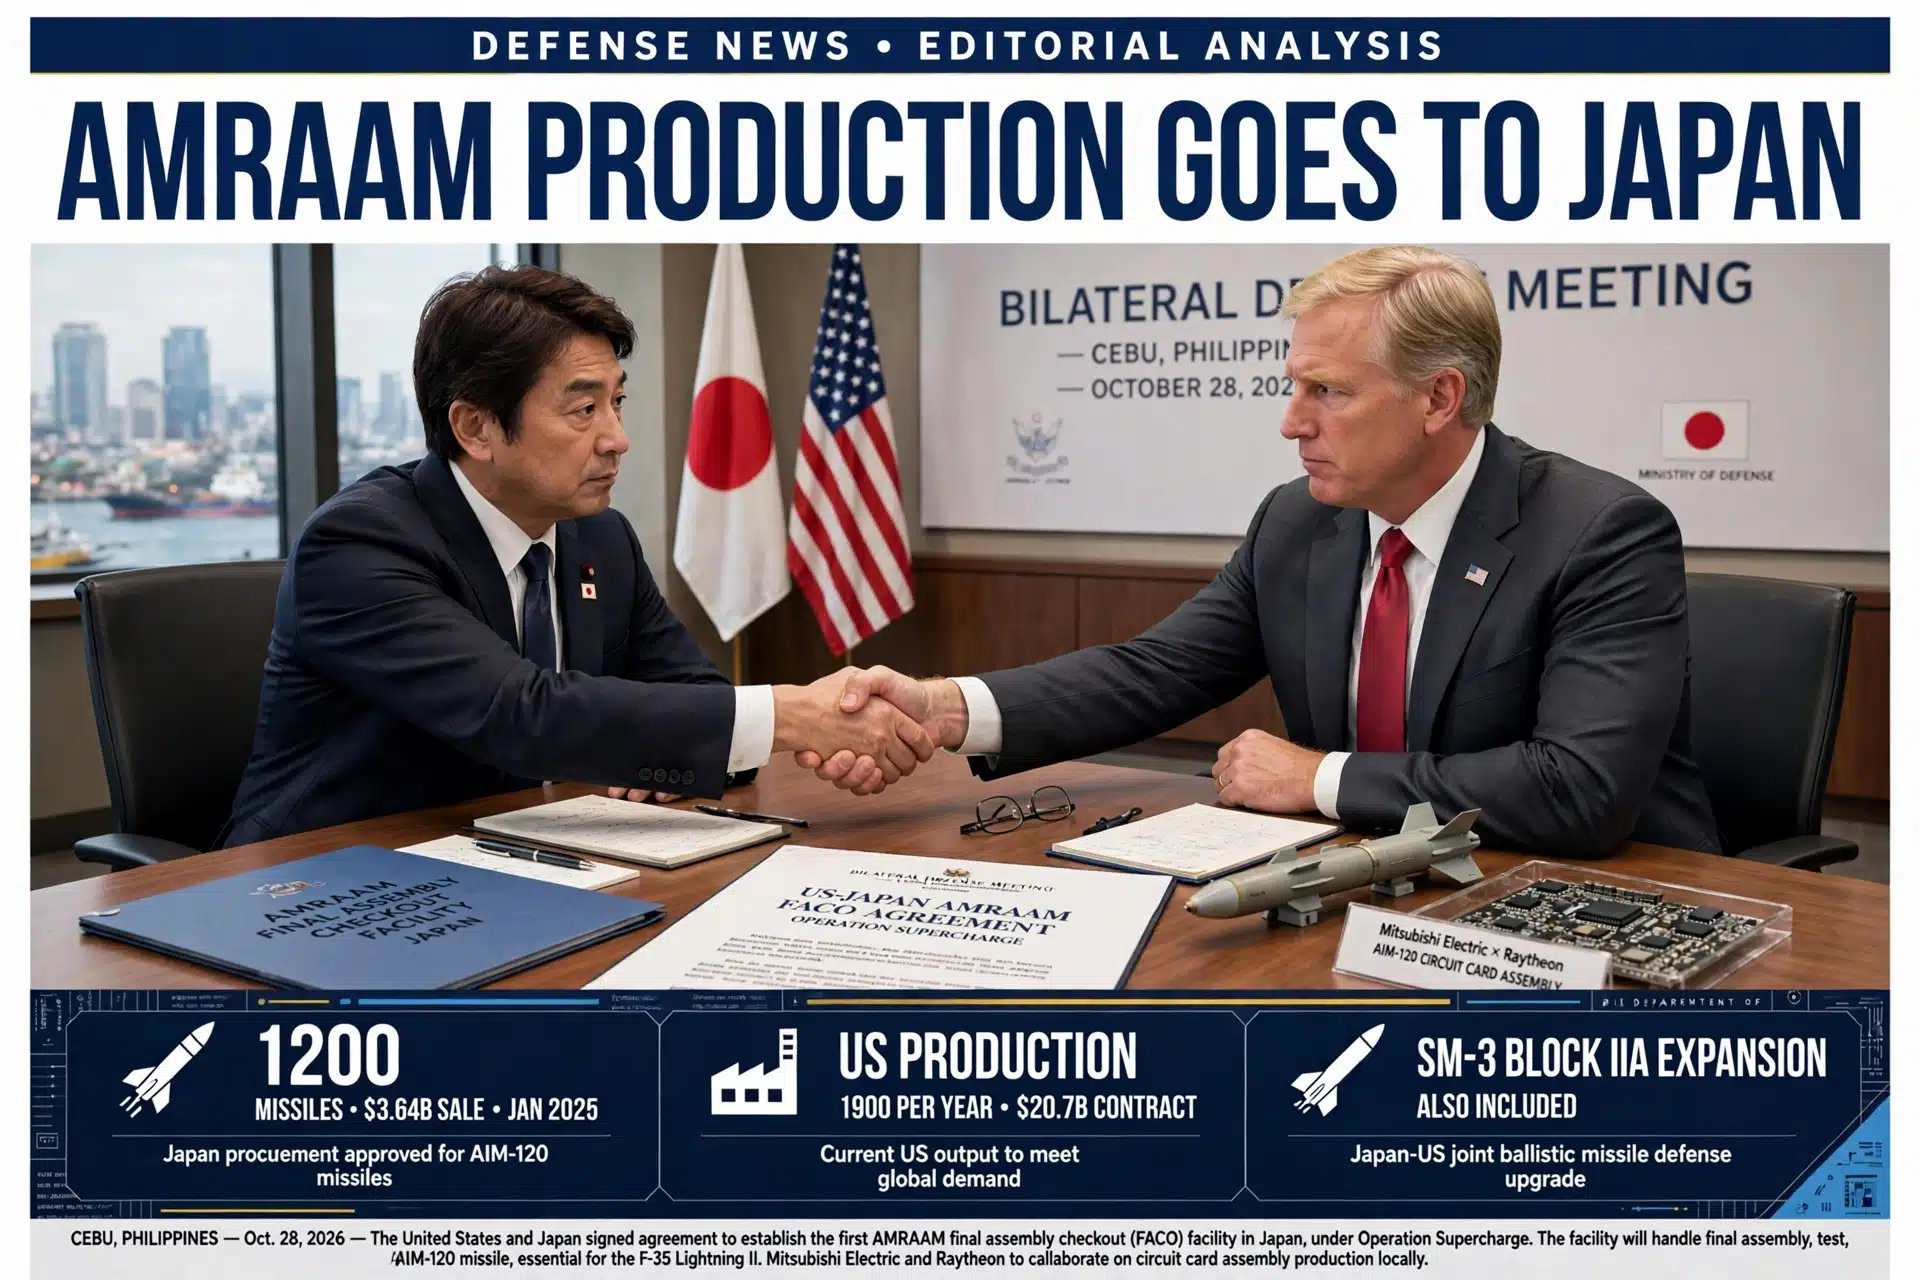
AMRAAM production is expanding to Japan, under an agreement Defense Secretary Pete Hegseth and Japanese Defense Minister Shinjiro Koizumi signed on October 28 in the Philippines, and the AMRAAM production Japan decision also opens the door to boosting SM-3 interceptor output. The allied factory move is the industrial-base side of a wider rearmament push, and it matters to US readers for one concrete reason: the air-to-air missile that guards every American F-35 and the sea-based interceptor that guards allied cities will no longer depend on a single country’s assembly lines. Final locations, output targets and timelines were not disclosed.

Key Takeaways:

  • – Hegseth and Koizumi agreed on October 28, 2026, at an ASEAN-linked defense meeting in Cebu, to establish an AMRAAM final assembly and inspection facility in Japan.
  • – The same readout records an agreement to share technical information enabling increased production of the SM-3 Block IIA interceptor.
  • – Both items fall under Operation Supercharge, the bilateral push accelerating defense equipment and technology cooperation.
  • – The step follows a September 2026 Raytheon award worth up to more than $20 billion over seven years that will nearly double AMRAAM production, contingent on congressional funding.
  • – Japan already co-produces PAC-3 and approved selling those interceptors back to the US in 2024, so the AMRAAM line extends an existing pattern.

What was agreed at Cebu

The Japanese defense ministry’s official meeting summary, dated October 28, records the two core decisions plainly: the ministers agreed to share the necessary technical information to enable increased production of the SM-3 Block IIA, and they agreed to establish an AMRAAM FACO, final assembly and inspection, in Japan. The meeting itself ran about half an hour, and the readout groups the decisions under Koizumi’s Operation Supercharge initiative alongside cyber cooperation, missile-defense strengthening and Keen Sword 27, the large bilateral exercise that follows.

The inside-baseball detail is the functional form of the facility. A FACO, final assembly and inspection capability, means Japanese workers will build finished missiles from US-produced components under US quality oversight, rather than merely conducting repairs or setting up a licensed copy shop. That structural choice keeps the sensitive guidance software and control systems consolidated in US hands while distributing production throughput across allies, which is precisely the arrangement Washington has used for decades with formal partners such as Japan’s F-35 wing line.

Why the US wants missiles built outside the US

AMRAAM, the AIM-120 built by RTX’s Raytheon unit, is described in trade coverage as essential to the F-35 and fires from every fighter in the American inventory as well as many allied ones. Demand changed after the spring 2026 Middle East operation drained stockpiles, and in May 2026 the Pentagon placed AMRAAM and the SM-3 on its list of 14 critical weapons to accelerate. The September 2026 Raytheon contract, worth up to over $20 billion across a five-year base with two option years, nearly doubles planned production.

The binding constraint is factory capacity, not demand. A FACO abroad ends up functioning as overflow capacity that cannot be easily disrupted by a supplier fire, a single test stand malfunction, or a domestic labor dispute, and each such disruption in 2026 has the entire weapon family waiting behind it. Japan’s motivation is equally concrete: a factory in its own country means priority access, deep local skill development, and a stake for its own contractors.

What Operation Supercharge actually changes

Operation Supercharge is the umbrella under which the two countries are accelerating equipment and technology cooperation. Under the same banner the two sides have opened co-development lanes for munitions, tightened intelligence sharing, and pushed Japanese shipbuilding cadence, with the October 28 meeting extending that into assembly-line territory for air-domain weapons. Japanese Defense Minister Koizumi framed the agreement as a groundbreaking deal: it ensures both countries acquire the equipment they need while strengthening Japan’s defense industrial base, a sentence that captures the industrial logic in a single clause. He followed up at a press event by promising to elevate the Japan-US alliance to even greater heights, per Stars and Stripes.

The operational frame matters too. The Pentagon readout, as relayed in trade coverage, emphasizes strategic alignment to strengthen deterrence and implement an effective denial defense in the First Island Chain, the line of islands running through the Philippine Sea that anchors US allied strategy against regional coercion. That is the strategic register in which missile-line policy lives, and it explains why such agreements move at diplomatic speed instead of procurement deadlines.

What this means for US jobs and supply

Domestic skepticism about foreign missile assembly deserves a real answer. The Japanese assembly decision does not move US aerospace employment overseas, because final assembly of US-built components adds finished-missile throughput that otherwise would not exist, plus a second country’s investment in the same supply chains that employ US workers. More AMRAAM output also eases the queue for foreign military sales customers, keeping the existing US line focused on American inventory.

The finer point is insurance. On the American side the word is munitions, and the simple version is that tomorrow’s shortfall in a regular war scenario would not wait for a US line to ramp up, especially when allied commitments depend on one country’s export approval. Meanwhile, Tokyo’s expressed interest in co-production with Raytheon dates back years, and Mitsubishi Electric’s April announcement of joint AMRAAM production talks with the American maker fits directly into this week’s decision, though the Japanese industrial partner has not been publicly named.

What happens next

Three questions remain open. Where in Japan the facility sits, what cadence it adds, and how its cost is split are all undetermined, and Stars and Stripes reported that the Japanese side offered no numbers. A formal implementing agreement, the legal instrument that authorizes a FACO, typically follows within months of a leader-level commitment, so watch the bilateral schedule through early 2027. Congressional funding is the other gate, because the September Raytheon award nearly doubles production only if lawmakers appropriate the option years, and the Japan line magnifies the effect of whatever the US funds at home. The official US record is thinner here, since publicly available DoD readouts do not name AMRAAM or SM-3, so the authoritative framing for now is the Japanese summary.

For US readers watching defense stocks and the defense industrial debate, the pattern to track is the second: every factory the alliance adds is a hedge against the bottleneck economics that slowed ammunition in recent years, and this agreement moves the highest-demand air-to-air missile into the same category Japan already handles for Patriot interceptors.

Frequently Asked Questions

Why is AMRAAM production moving to Japan?

It is not relocating; a new final assembly facility is being added in Japan to expand total output. The October 28 agreement responds to surging demand after missile stockpiles drained in 2026 and to the Pentagon’s push to accelerate 14 critical weapons, including the AMRAAM and SM-3.

What is Operation Supercharge?

Operation Supercharge is the Japan-US bilateral initiative, championed by Defense Minister Koizumi, that accelerates defense equipment and technology cooperation, including munitions co-production, and the October 28 agreements on AMRAAM FACO and SM-3 technical information sharing fall under it.

Will SM-3 interceptor production increase?

Both governments agreed to share technical information to enable increased SM-3 Block IIA production, which is the prerequisite step toward higher output. Actual rates jump only after production decisions, facility arrangements and funding follow, and no timeline or numbers have been published.

Sources:

Diversity Visa Lottery Stay Halts the November 1 Reopening

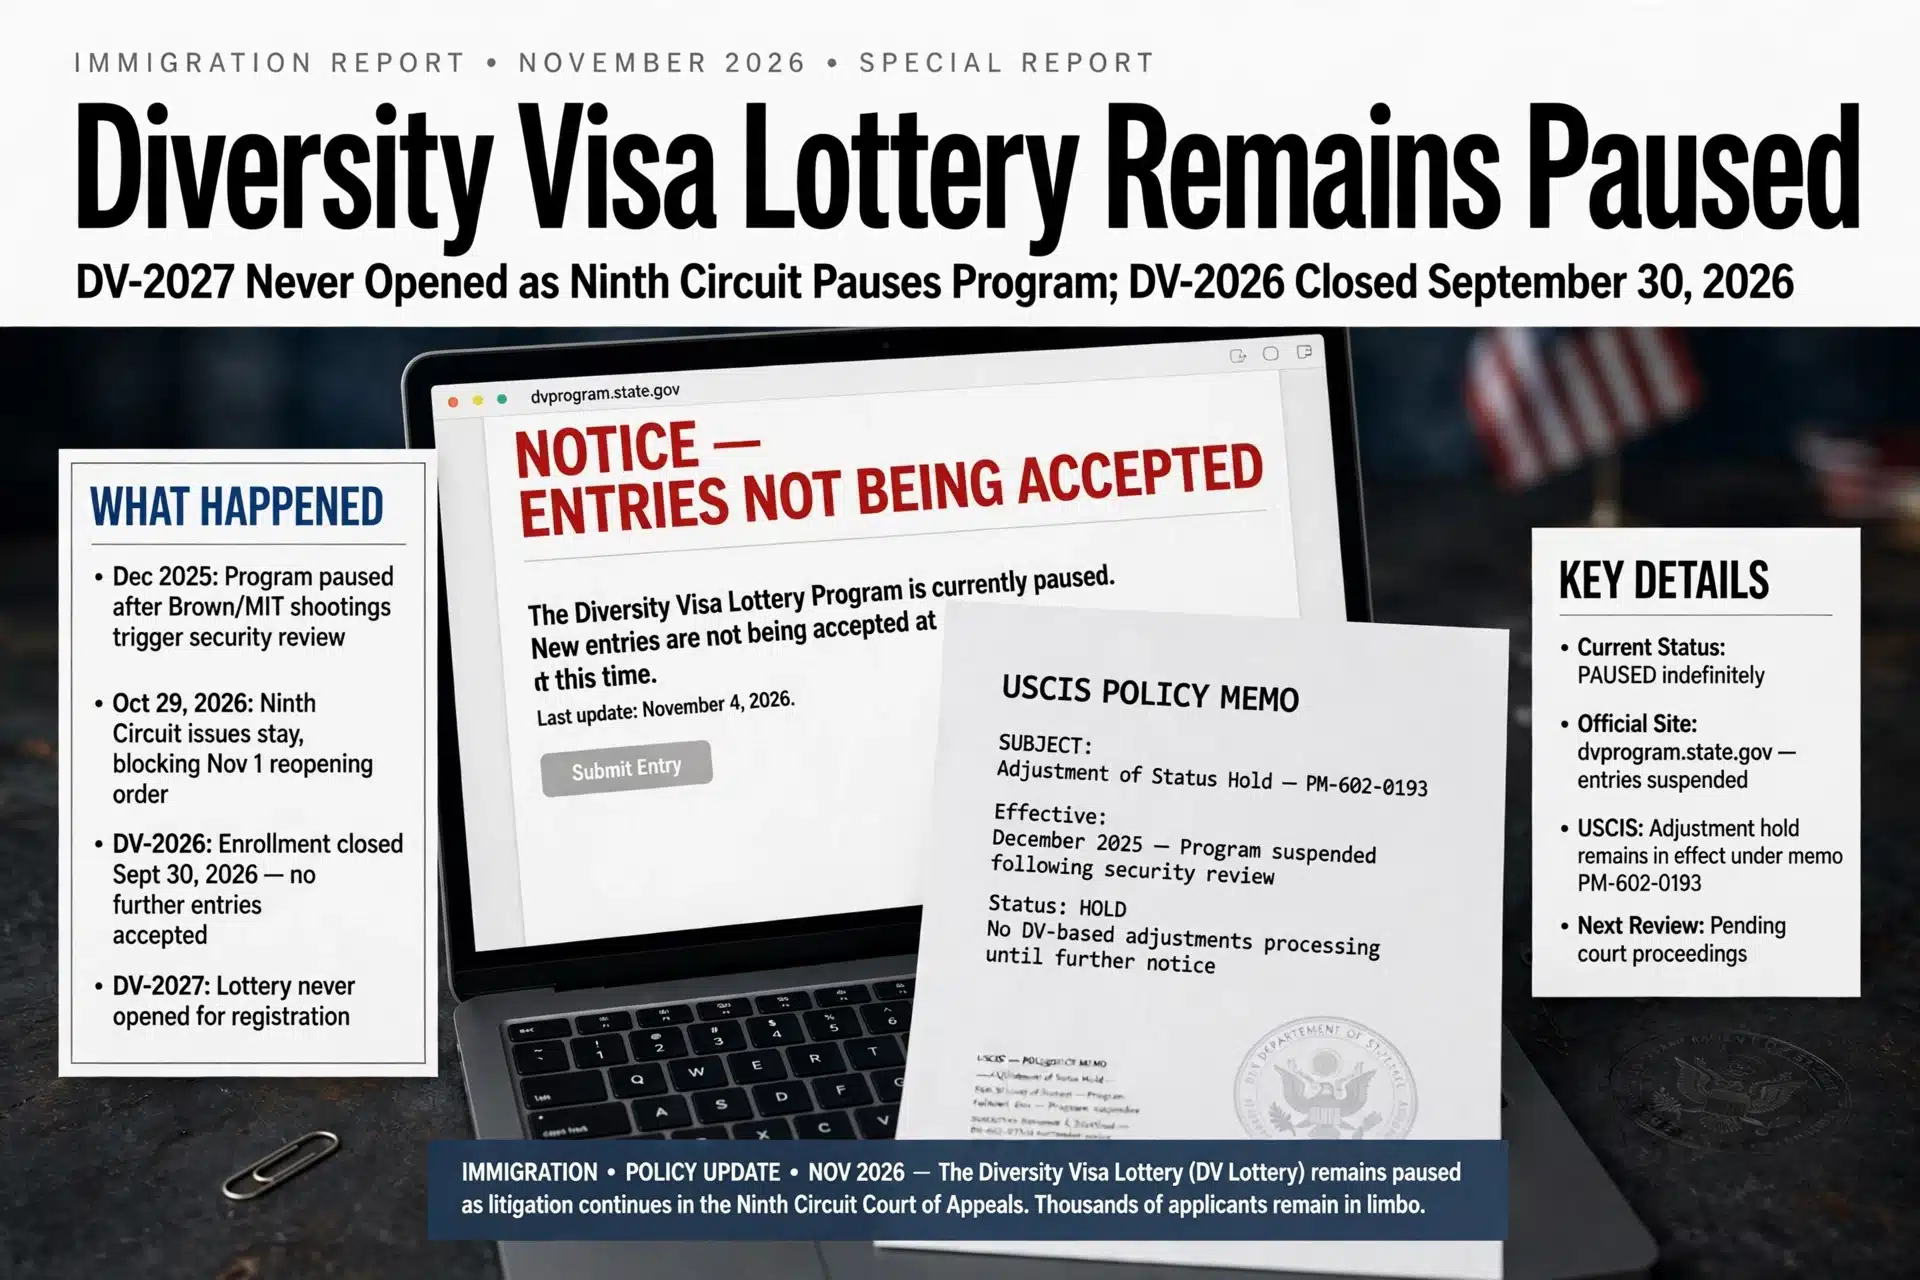
The diversity visa lottery will not open for 2027 registration on November 1 as a lower court had ordered, because a three-judge Ninth Circuit panel granted the government’s emergency motion to stay that injunction on October 29, 2026. In practical terms, the DV-2027 window that prospective entrants expected by the end of this week remains closed, and the diversity visa lottery’s fate for the full fiscal year now depends on litigation that will stretch well into December. This article is informational only and not legal advice; consult a licensed immigration attorney about your situation.

Key Takeaways:

  • – On October 29, 2026 the Ninth Circuit granted a stay of the district court order that had required the State Department to open DV-2027 registration by November 1.
  • – The lower court, Judge Jinsook Ohta in San Diego, had on October 14 ordered registration details announced by October 29, a 30-day window opening November 1, and selectee notifications by December 3.
  • – The appeals court rested its ruling on standing, holding that a private immigration law firm cannot sue over the canceled lottery, and expressly did not endorse the Department’s failure to open registration.
  • – Up to 55,000 diversity immigrant visas are at stake for fiscal year 2027 under the statutory program created by Congress in 1990.
  • – The appeal continues: briefs are due November 17 and December 15, and the plaintiff says it will look for a different filer, such as a nonimmigrant visa holder, to carry a new case.

What the Ninth Circuit actually decided

The order, published October 29 in Red Eagle Law v. Rubio, ruled on who may bring the lawsuit, not on whether canceling the lottery is lawful. The panel held that Red Eagle Law, a San Diego boutique immigration firm, sits outside the zone of interests protected by these statutory provisions and lacks an adequate cause of action. A concurring opinion called the firm’s asserted downstream revenue speculative. Because the government was likely to succeed on that standing question alone, the stay was granted, and the panel wrote that the court does not endorse the Department’s failure to open the lottery registration period; that failure was left legally undetermined.

That distinction matters for what happens next. A merits ruling that blessed the cancellation would have foreclosed the program for 2027 outright. Instead, the door stands open on the substance, and any future filer with a qualifying claim, most naturally a person eligible to enter the lottery, could test it directly. Docket records show briefs due November 17 for the opening brief and December 15 for the answering brief, and a rehearing petition would be due within 14 days of the decision according to Ninth Circuit rules.

How the lottery got to this point

Statutorily, the program can distribute up to 55,000 immigrant visas per year by random draw to nationals of countries with historically low US immigration, with eligibility tied to country of birth plus education or work experience, and selectees still must clear standard processing. Per the opinion’s account of the Department’s conduct, the failure to open FY 2027 registration was without explanation, effectively canceling the year.

The initial order arrived on October 14, when Judge Ohta granted a preliminary injunction, requiring the Department to announce registration details by October 29, open the entry window on November 1 for a full 30 days, and notify selectees by December 3. Those dates were all that stood between millions of eligible applicants from low-immigration countries and a lost year. The Ninth Circuit’s stay suspended each of them, and State has not signaled any voluntary reopening.

What this means if you wanted to enter DV-2027

The immediate answer is that there is nothing to enter right now. No replacement decree or altered processing mechanism substitutes for the statutory registration process. Preparing education or work documentation now is reasonable in case the window opens late rather than never. No official filing channel exists outside the government’s own portal, so anyone selling alternative entry routes this season is not operating a real lottery entry.

One caution follows directly from this week’s action: the only legitimate entry route, if and when the program opens, is the government’s own free portal, dvprogram.state.gov. Work authorization or status questions a would-be selectee carries should be handled by your counsel of record, since litigation over this program creates no new rights meanwhile. Bogus services advertising replacement lottery entry in this vacuum are fraud; there is no fee to enter a federal immigration registration program that is closed.

How likely is a full-year cancellation to become permanent

The lottery’s legislative foundation is unchanged. Nothing in this week’s order repeals the statutory basis of the program, and the State Department declined to open the window rather than being barred from doing so. A future decision to comply with any court order, or to announce a late registration window on the Department’s own initiative, could still rescue most of the fiscal year calendar. Renewed legislative attention could also formally alter the lottery’s mechanics. What the Ninth Circuit changed is the immediate pressure on the Department rather than its ultimate options.

The longer-term reading is two-sided. Program defenders read the same documents as showing that canceling the lottery via inaction is legally exposed eventually, and the plaintiff’s announced search for a standing-qualified filer suggests a new case before those deadlines arrive. Opponents of the program, and the Department, argue that executive discretion in this space is structural, and each published opinion about the program’s administration will map how far that discretion reaches.

What happens next

Litigation is the nearest clock, with briefs due November 17 and further filings through December 15, and a rehearing petition possible within 14 days of the order. A separate case with a standing-qualified plaintiff, which the firm’s lead has said it intends to file, could restart the legal clock faster than the current appeal. On the administrative side, watch for a Federal Register notice or an updated State Department DV-2027 page, either of which would signal a late registration window; November and December are the last months a fiscal-year program of this kind can salvage substantial processing. Keep your eligibility documentation ready and disregard any announcement that is not the State Department’s own.

Frequently Asked Questions

Will the DV-2027 lottery still open?

Not on November 1. The Ninth Circuit’s October 29 stay suspended the district court deadline that had ordered registration to open that day, and the State Department has not announced any replacement timetable. Whether a late window opens depends on the appeal, a possible new lawsuit, or voluntary administrative action.

Why is the diversity visa program paused?

Per the Ninth Circuit opinion’s account, the Department failed to open FY 2027 registration without explanation, after first delaying it in November 2025 and indefinitely pausing issuances in December 2025 following a DV-2017 selectee’s connection to the Brown University shooting. The legality of that failure is not yet decided.

Can I still enter the 2027 green card lottery?

There is currently no active registration window for DV-2027, and the official portal states entries are not being accepted at this time. The only legitimate entry route if the lottery reopens is the State Department’s own free portal, so any paid alternative-entry service distributed now is fraudulent.

Sources:

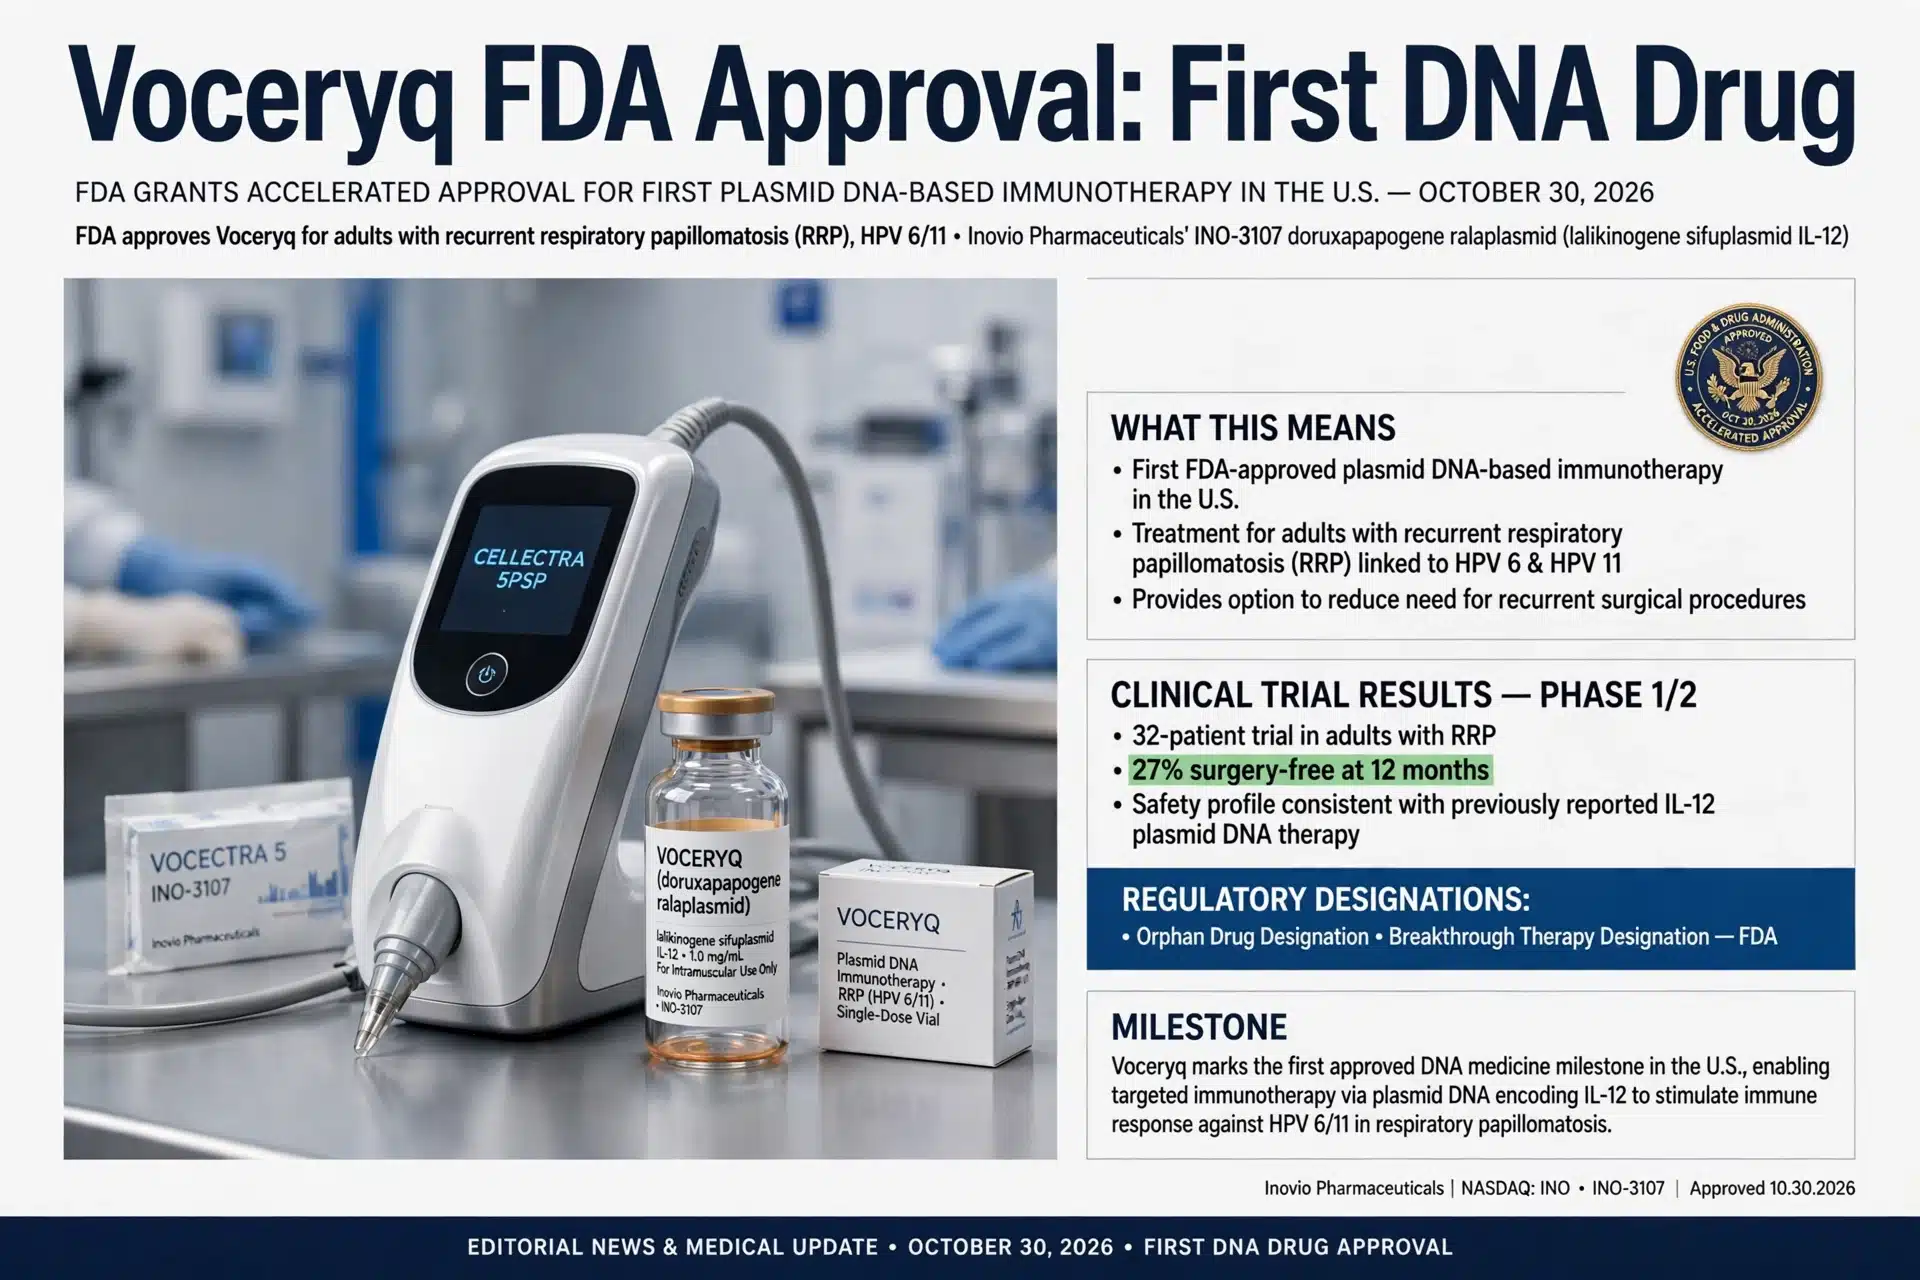
Voceryq FDA Approval Makes It the First DNA Medicine Sold in the US

The FDA approved Voceryq on October 30, 2026 as the first plasmid DNA-based immunotherapy cleared in the United States, for adults with recurrent respiratory papillomatosis, and the Voceryq FDA approval matters to a small patient group that has spent decades cycling through throat surgeries. Approximately 27 percent of heavily-affected trial patients needed no surgery in the first year after treatment. Availability in the US is expected roughly 60 days from approval, with Inovio targeting a full commercial launch in the first quarter of 2027. This article is informational only and not medical advice; treatment decisions belong with your physician.

Key Takeaways:

  • – The FDA granted accelerated approval to Voceryq on October 30, 2026 for adults with recurrent respiratory papillomatosis, a rare HPV-driven airway disease.
  • – It is the first plasmid DNA-based immunotherapy ever approved in the US, following Inovio’s 2025 approval of Papzimeos, a different vector approach for the same disease.
  • – Trial data showed 7 of 26 patients, about 27 percent, with three or more annual baseline surgeries required none in the first year after treatment.
  • – The drug also holds FDA Breakthrough Therapy and Orphan Drug designations and is administered by intramuscular injection with the CELLECTRA 5PSP electroporation device.
  • – Shipping is expected to start about 60 days after approval, per company statements, with a full commercial launch targeted for Q1 2027.

What recurrent respiratory papillomatosis does to patients

RRP is a chronic disease caused by HPV types 6 and 11, the same virus family behind common warts, but in the airway the papillomas grow on the larynx and vocal cords. The result is a hoarse voice, a persistent cough, and in serious cases growths that obstruct breathing entirely. Surgery removes the growths, but the tissue regrows, and the standard experience for severe patients is repeated procedures, sometimes several per year, for decades of their lives. Ask patients how this approval is different and you hear the surgical-count answer: fewer operations per year is the whole measure of a life changed.

The FDA’s own framing acknowledged the cycle. In the agency’s October 30 announcement, Center for Biologics Evaluation and Research director Karim Mikhail said adults with RRP often face an exhausting, relentless cycle of repeated surgeries that manage disease but never truly escape it, and called today’s approval a meaningful scientific breakthrough that harnesses the body’s own immune system to fight the underlying cause of RRP. That immunological framing is the technical dividing line between Voceryq and surgery: instead of cutting growths out, the therapy tries to train the immune response to stop the regrowth.

How the drug works

Voceryq is actually two recombinant plasmids given together by intramuscular injection. One carries the protein sequences for the HPV-6 and HPV-11 strains driving the disease, which presents a clear target to the immune system. The other encodes interleukin-12, a signaling protein that amplifies immune activity, which is the enhancer half of the pair. A small device called CELLECTRA 5PSP uses brief electrical pulses at the injection site to help cells take up the plasmid DNA.

The delivery mechanics shape some unusual acute reactions. Common adverse reactions listed in the FDA release cover the injection site, headache, fatigue, hypertension, nausea and dizziness, and electroporation-specific effects include brief muscle contractions, temporary bleeding, anxiety, vasovagal reactions and transient enzyme elevation. None of these change the structural math of the approval, but patients should expect the administration procedure itself, not lab follow-ups, to shape most of what they feel after a dose.

What the trial data actually shows

The pivotal evidence came from an open-label, multicenter trial in 32 adults who had at least two laryngotracheal papilloma surgeries in the prior 12 months and were scheduled for another at entry. In the group with three or more baseline surgeries, 26 patients were analyzed, and 7 of them, 27 percent, required no surgery in the first year after treatment. That is the endpoint the FDA relied on, the intermediate outcome the accelerated approval pathway permits when a disease lacks every other option.

Accelerated approval carries follow-on obligations. Full approval will hinge on post-approval trials confirming the clinical benefit, so the label today is conditional. Patients and insurers should read that as an honest signal: the drug is approved because the surgery-reduction evidence is strong enough for a rare disease with no equivalent alternative, and additional data will deepen over the next few years. The FDA simultaneously granted Breakthrough Therapy and Orphan Drug designations, the combination that typically speeds access for conditions affecting fewer than 200,000 US patients.

Why the 2025 Papzimeos approval does not make this redundant

Inovio already sells Papzimeos, an immunotherapy for the same disease approved last year, so why does a second RRP therapy matter? The reason is platform. Papzimeos is adenoviral-vector based, a viral delivery chassis that inserts its immunological payload differently. Voceryq is plasmid DNA, a non-viral chassis, delivered by electroporation. Clinically, both attack the HPV-6 and HPV-11 mechanisms behind RRP, but patients who do not respond to the vector approach may now have a non-viral alternative. For Inovio the approval validates nearly three decades of development into a DNA platform that Wall Street treated as perpetually early. The market agreed for an afternoon; shares more than tripled after hours on October 30, with gains above 215 percent per Reuters. Pricing remains undisclosed as of October 31, and the company expects orders and shipping within about 60 days, with full commercial launch in Q1 2027.

What happens next

Watch three dates. Roughly 60 days out, per Inovio’s announcement, Voceryq should become orderable, so late December 2026 is the realistic first-availability window for US clinics that treat severe RRP patients. Q1 2027, per the company, is the full commercial launch, which is when distribution broadens beyond initial specialty centers. Insurance coverage is the live question for individual patients; rare-disease accelerated approvals often open with case-by-case prior authorization while payers wait for real-world evidence, and November 2’s company investor call is where adoption math may surface. The accelerated approval also obligates confirmatory trials, so expect patient data to keep accruing through 2027 regardless of commercial tempo.

For the roughly tens of thousands of Americans managing this disease, the practical takeaway is discussion material for a laryngology or ENT follow-up: a non-surgical option now exists on the US approved list, its one-year track record shows roughly a quarter of severe patients going a year without an operation, and its non-viral delivery may matter if Papzimeos was unsuitable. Access logistics, price and payer coverage will decide how many patients actually get the improved year the trial promised.

Frequently Asked Questions

What is Voceryq and who can get it?

Voceryq is a two-plasmid DNA immunotherapy the FDA approved by accelerated approval on October 30, 2026 for adults with recurrent respiratory papillomatosis, the HPV-driven disease causing recurring airway growths. Eligibility is for adults whose disease keeps requiring surgery; it is not approved for children or as a general HPV treatment.

When will Voceryq be available?

Inovio says the drug should be available to order and ship about 60 days from the October 30 approval, putting the first shipments around late December 2026, with full commercial launch targeted for Q1 2027. Actual patient access also depends on clinic stocks and insurance approval.

Does Voceryq cure RRP?

No. The trial endpoint was a reduction in surgeries, and 27 percent of the analyzed patients with three or more baseline surgeries had none in the first year after treatment. The approval is accelerated, meaning it rests on an intermediate endpoint and confirmatory trials must still demonstrate lasting clinical benefit.

Sources:

Echo Show 16 Lands at $499 as Amazon Rebuilds the Smart Display

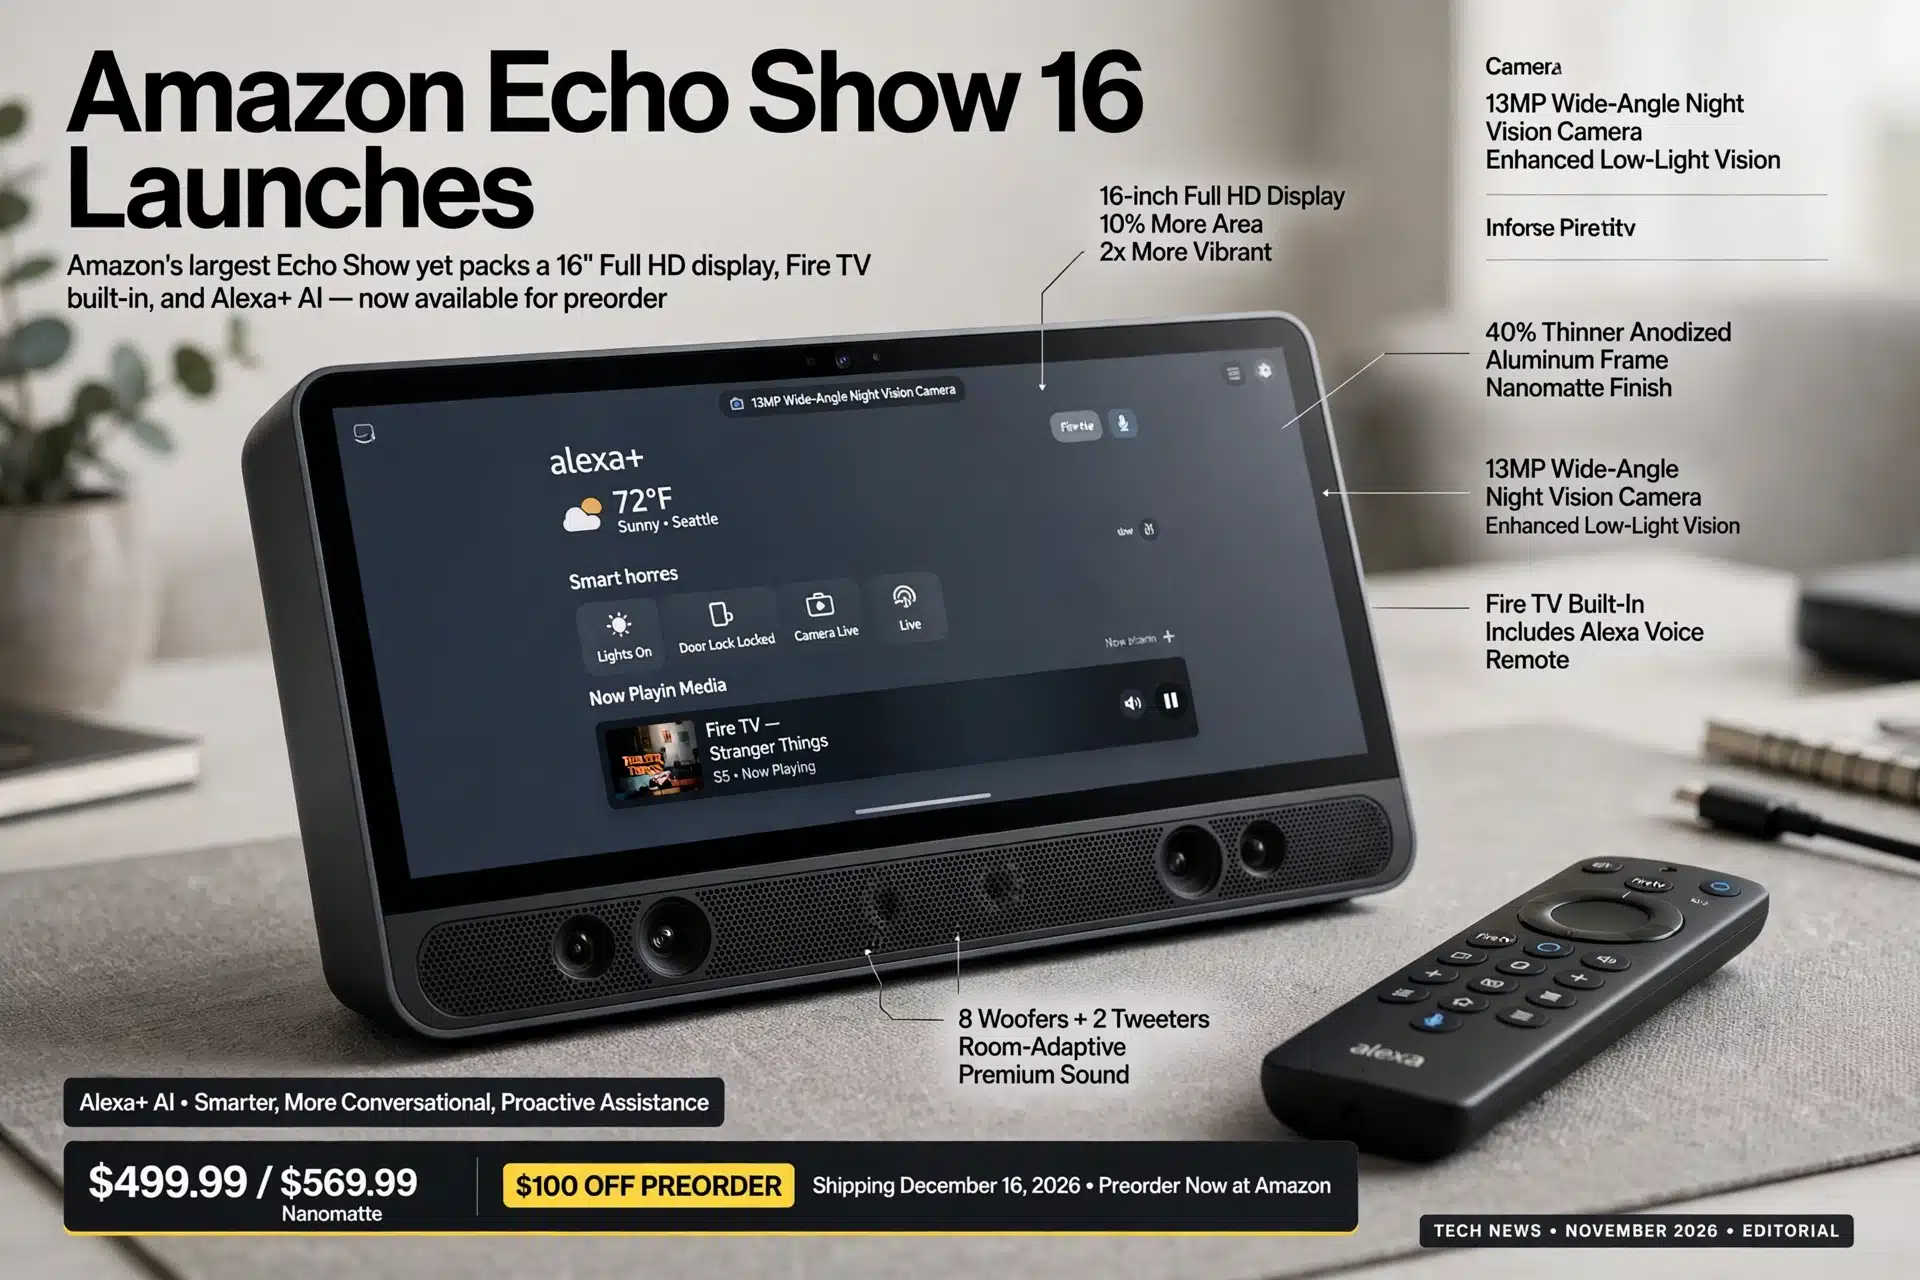
Echo Show 16 arrived on October 28, 2026 at $499.99, a ground-up rebuild of Amazon’s biggest smart display with a 10-speaker audio system, night vision and a 13-megapixel camera, and the Echo Show 16 is Amazon’s clearest opening counter to Apple’s $299 HomeView. US buyers weighing the two now have a genuine fork: a kitchen-and-family hub that also acts as a room TV, or a tighter-purpose display that leans on Apple’s ecosystem. Here is what Amazon shipped, what it costs, and whether the premium is justified.

Key Takeaways:

  • – Echo Show 16 costs $499.99, or $569.99 for the glare-cutting Nanomatte version, with $100 off for preorderers and shipping later this year.
  • – It packs eight custom micro woofers plus two tweeters, a 13-megapixel wide camera with first-ever Echo night vision, and Fire TV built in with a remote in the box.
  • – Amazon says the 16-inch panel shows 10 percent more viewing area than Echo Show 15 with roughly twice the color vibrancy, and the aluminum frame is nearly 40 percent thinner.
  • – The visual ID range doubled to up to 17 feet, and a new Alexa Home Map renders a 3D view of your home using compatible Ring cameras.
  • – Four other devices shipped alongside it on October 28: a reworked Echo Dot at $99.99, Echo Studio with Home Camera at $249.99, Echo Time alarm clock at $199.99, and Alexa Photo Frame from $199.99.

What the Echo Show 16 actually is

The pitch is a family computer for shared rooms, not a bedside widget. The 16-inch full HD panel is the canvas, but the hardware list is where the upgrades concentrate: eight custom micro woofers and two tweeters fill a living room well enough that Amazon frames it as real music equipment, and a 13-megapixel wide-angle camera has the widest field of view Amazon says it has ever shipped on an Echo Show. Visual ID, which recognizes who is in front of the device, now reaches up to 17 feet instead of eight, and this is the first Echo Show with night vision.

The display itself gets a Nanomatte option with more than 90 percent less glare and half the sparkle, built on the same etching technology Amazon engineered for its Alexa Tablet 12 Pro. Three new Screen Styles turn the device into a smart-home dashboard, a family organizer or a photo display, and a customizable favorites bar sits at the bottom. Fire TV support with a remote included means the device doubles as a small room television.

The price and where it fits

Five hundred dollars is the point where buyers expect a device to earn its place as a primary household screen, and reviewers have been blunt about the bar it clears. CNET framed the bet directly: Amazon is wagering that there is room for another screen in your home, and that you will pay $500 for it. For that money you get the display, the audio system, the camera and the hub functions, with stands sold separately at $69.99 basic or $124.99 for a swivel-and-tilt unit. The Verge reported a December 16 launch date, though Amazon’s own materials say only later this year.

The strategic frame is the matchup with Apple. HomeView landed with an October 13 announcement, a 7-inch display at $299 shipping November 13, targeting the same surface: the shared screen that anchors household routines. Amazon’s answer is to go big where Apple went small, adding sound and vision capability HomeView does not attempt. Reviewers who tried both noted that the two could finally make the smart display the family computer it was always pitched as, a notable reversal given that smart displays have been widely seen as a stalled category for three years.

The rest of the October lineup matters too

The Show 16 anchors five launches. The new Echo Dot at $99.99 is the first with a built-in smart home hub plus an eero Wi-Fi extender that adds up to 1,000 square feet of coverage, runs on custom AZ3 silicon with a dedicated AI Accelerator, and gains 50 percent more bass; the kids version runs $109.99. Echo Studio with Home Camera brings the first camera to that speaker line at $249.99 for room monitoring and upcoming Fire TV video calling. Echo Time is a camera-free $199.99 smart alarm clock with a 3.2-inch touchscreen and Omnisense sleep sensing that wakes you within a 10-to-60-minute window of your alarm, a design Amazon says earned a SleepMark from the National Sleep Foundation. The Alexa Photo Frame, from $199.99 in black or $229 in birch or walnut, is Amazon’s first Alexa-equipped photo frame, with Amazon Photos sync and a no-ads promise. Everything except the Show 16 shipped the same day. Those side devices reveal the strategy. Amazon is spreading hardware across price bands from a $99 speaker to a $500 living-room centerpiece, and it chose incremental October announcements over its old single fall keynote.

Why Amazon dropped the mega-event

Amazon’s devices chief Panos Panay gave the reasoning to Engadget: last year’s single event was a fine moment, but only two products really got attention while everything else was just there, which he felt cheated the teams behind overlooked products. The result is a Techtober cadence that spread launches across the month, including new Alexa Tablets, Colorsoft Kindles, Ring’s first smart lock at $249 and Blink 4K cameras, before the Show 16 event closed it out.

The category data supports the pivot. Amazon says the Echo Show line is its fastest-growing Echo segment, up more than 25 percent year over year, which is why the company is willing to field a flagship at a price point its own smart display business would have rejected two years ago. Growth in that niche gives Amazon cover to defend the share against Apple’s first real entry with a screen.

What happens next December 16 is the shipping date to watch, and early reviews will judge two things, whether the 10-speaker system justifies a de facto room TV, and whether Visual ID at 17 feet feels convenient instead of invasive. A $500 sticker tests how far smart display demand stretches, and it sets the price ceiling Apple’s cheaper HomeView can comfortably undercut. If Echo Show 16 sells, expect Amazon to press the same family-computer framing next year; if it stalls, the lesson will be that the smart display needed to stay small.

For US households the decision is straightforward. A $300 HomeView signals you want a family screen inside the Apple ecosystem, while a $500 Echo Show 16 signals you want one device that covers entertainment, communications, smart-home control and photo display in the room where everyone gathers. Preorder pricing and the December window settle the calendar; the market test for the premium smart display finally starts now.

Frequently Asked Questions

How much does the Echo Show 16 cost?

The standard Echo Show 16 is $499.99 and the Nanomatte version is $569.99, with a $100 discount for preorderers. Optional stands run $69.99 or $124.99 for the swivel-and-tilt model, and Fire TV remote is included with the main unit.

When does the Echo Show 16 ship?

Amazon says later this year; The Verge reported a December 16 date. The other four October 28 devices, Echo Dot, Echo Studio with Home Camera, Echo Time and Alexa Photo Frame, all began shipping on announcement day.

Echo Show 16 vs Apple HomeView: which should you buy?

The $299 Apple HomeView is a compact 7-inch display tightly integrated into Apple’s ecosystem and ships November 13. The $499.99 Echo Show 16 is a larger family hub with room-filling audio, an advanced camera and built-in Fire TV, a fit for households already using Alexa or Ring devices rather than iPhone-centric homes.

Sources:

OpenAI Funding Target Cut to $20B as AI Repricing Spreads

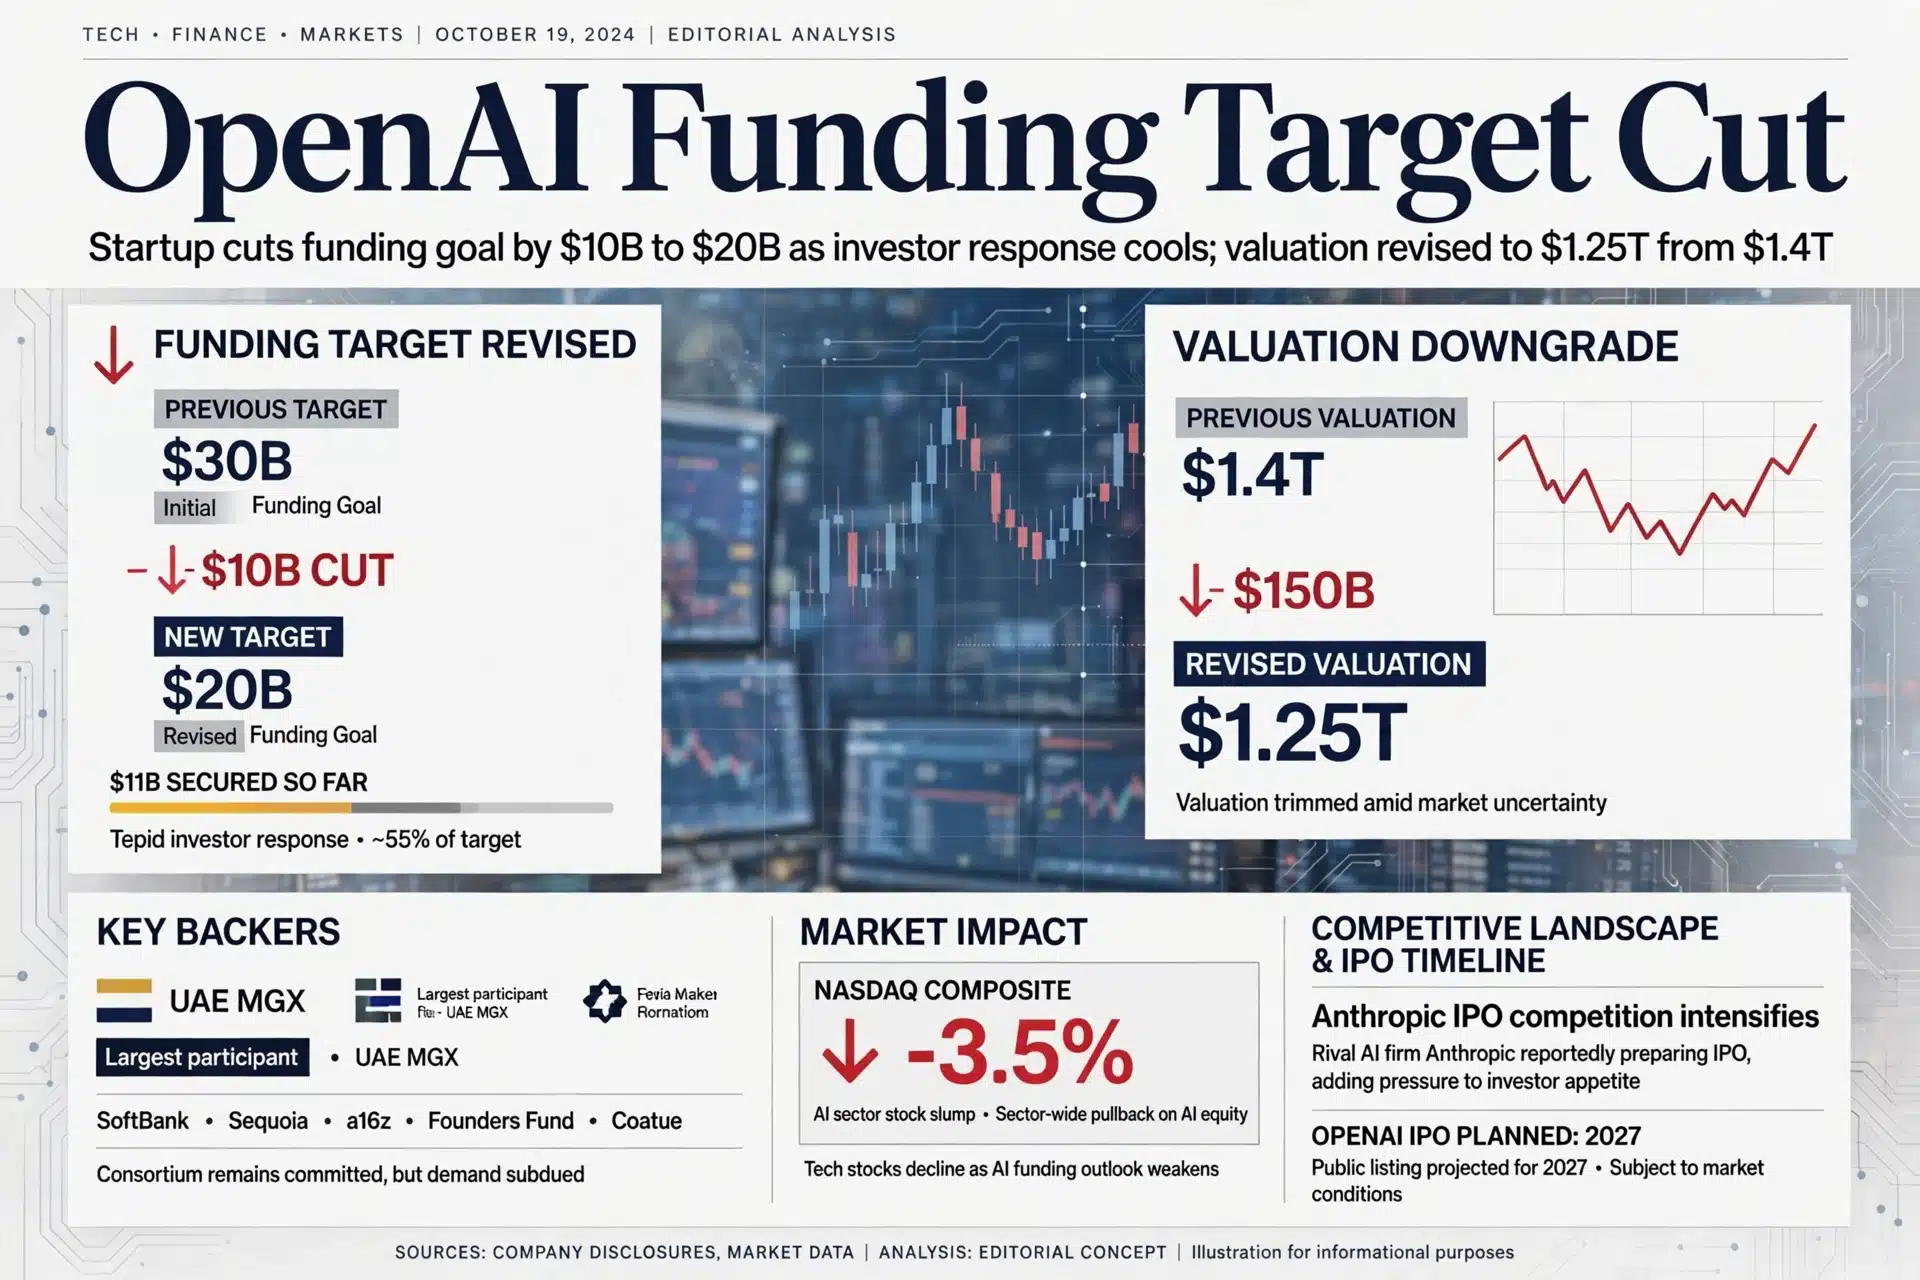
OpenAI cut its funding target from about $30 billion to roughly $20 billion, according to the Financial Times, while keeping its valuation at $1.25 trillion, and the OpenAI funding target cut lands one day after US chip and internet stocks took their worst day since June. The two moves are parts of one process: private and public markets repricing the AI buildout at the same time. For US readers the practical question is simpler, whether the companies running the AI boom can still fund it without pushing prices and borrowing costs up for everyone else.

Key Takeaways:

–

  • – The News agency reported the cut on October 31, and OpenAI did not respond to a request for comment, so the numbers remain FT-reported rather than company-confirmed.
  • – On Friday, October 30, the Nasdaq Composite fell 2.86 percent to 25,437.00, its largest one-day drop since June 5, per Reuters.
  • – Intel plunged about 28.6 percent, its worst day since 1974, after weak forward guidance, per Reuters and CNBC.
  • – Amazon posted negative free cash flow of about $42.4 billion while holding 2026 capital spending at $220 billion, per CNBC.

What changed in the OpenAI funding target

Three numbers define the new round: the raise shrank from about $30 billion to about $20 billion, the valuation held at $1.25 trillion, and the first close is expected to land below the target. The Financial Times reported that OpenAI set a Friday deadline for investor commitments and that investors trimmed their allocations. An earlier September cycle had reported a $1.4 trillion figure, a haircut of roughly $150 billion across the negotiation, on top of a March round at about $852 billion.

The careful read matters here. OpenAI has not confirmed the figures, and Reuters noted the company declined to comment. Treat $20 billion as the reported number of record while the final close remains unpublished. Still, a target cut of a third inside one cycle signals that even the recognized leader must negotiate with capital markets on their terms.

The selloff that framed the cut

The public market moved first. Recent markets closed sharply lower on October 30, with chip and internet stocks cratering to their worst day since midsummer. Momentum faded quickly across the space as investors rotated out of high-multiple technology names and into defensives, and the technology channel put the one-month damage in context: the chips index fell more than 7 percent that day alone and was down over 15 percent for October.

Intel became the emblem of the repricing after reporting results that missed on forward direction, and Amazon drew the other kind of scrutiny, the kind that focuses on cash flow. Posting a negative free cash flow of $42.4 billion while committing to a record $220 billion capital budget turned market attention from AI revenue ambitions toward the bill for those ambitions. Alphabet also recorded one of its worst single-day drawdowns on record after a quarterly miss that included negative free cash flow. These are all supply-side facts: the companies that fund AI infrastructure are spending more than they earn right now, and Friday’s market said it noticed.

Why investors are pressing pause

The core worry is not demand for AI models, it is the financing stack underneath them, and that worry now has a public paper trail. Rich technology company balance sheets work fine, but the model of the past two years has been to borrow and spend into capacity ahead of revenue. Regulators have started watching those disclosures. Reuters quoted SEC Enforcement Director David Woodcock on October 30 saying, “Our principal concern is that people are making accurate disclosures about material information so that investors know what they’re getting into.” When the Securities and Exchange Commission frames concern around disclosure accuracy in a fast-moving market, private funds cannot assume smooth exits. That is the indirect link to the OpenAI funding target cut. Private market prices need public market anchors, and public anchors pulled back on the day the private deadline landed. Crossover investors read the same models openAI’s underwriters do, and several declined to pay the last cycle’s clearing price.

What an OpenAI downshift means for pricing

OpenAI’s capital needs are real even at a reduced target: compute, data, energy and talent are all scarce inputs it is buying at industrial scale. A smaller raise suggests the company either expects to smooth costs across more time or expects cash flow from subscriptions and enterprise deals to carry more of the buildout. Either path affects consumers. If OpenAI leans more on paid products to fund infrastructure, expect tighter free tiers or higher list prices on the popular consumer plan at the next renewal. If OpenAI leans on less-expensive hardware and negotiated compute, costs inside the AI sector may actually compress, and some of that could pass through as broader access for smaller developers.

The repricing also reshapes rivals’ math. Anthropic filed its S-1 in late October and is expected to price its IPO in mid-November, and reports in the same window put its expected marks below where they sat a week earlier. A cheaper entry point for the second-largest frontier lab changes where talent, enterprise contracts and capital flow across the whole market, and it is a reminder that OpenAI’s leadership position is no longer priced as unassailable.

What happens next

The round’s first close is the near-term marker. If it lands well under $20 billion, the private market has put a hard ceiling on how much the flagship can raise at this valuation, and secondary pitches built on top of that mark will need rework. The next public marker is Big Tech quarterly reports in November, where investors will parse capex guidance for suppression and watch whether Amazon and Alphabet defend the spending that just cost them their best valuation weeks of the year. The two threads are connected: every basis point of credibility OpenAI loses on fundraising shows up in how generously the public markets treat the vendors selling compute to the whole ecosystem.

For US households the effects are indirect but real. Pension funds and 401(k) allocations carry large technology weights, so monthly statements echo these repricings. Energy markets absorb the demand side, because data centers buy power at scales that compete with municipal needs. The question of whether the AI wave delivers returns is no longer an investment community debate; it is now a consumer economy question, and October 2026 is when pricing power on both sides of the ledger started being renegotiated in public.

Frequently Asked Questions

Why did OpenAI cut its funding target?

The Financial Times reported the cut on October 30, 2026 from about $30 billion to roughly $20 billion at a $1.25 trillion valuation, citing investors tempering allocations, a day after the worst US tech session since June on AI cash-burn fears.

How much is OpenAI worth now?

The reported valuation is $1.25 trillion, down from a reported $1.4 trillion in September but up from about $852 billion in its March 2026 round. OpenAI has not confirmed the number and did not respond to a request for comment.

Is the AI bubble popping in October 2026?

Markets are repricing, not collapsing. The Nasdaq fell about 2.9 percent on October 30, down roughly 5 percent for the month, while Intel and Amazon drew selling for earnings and cash-flow gaps. Capital still flows into AI, but investors now demand evidence of returns.

Sources:

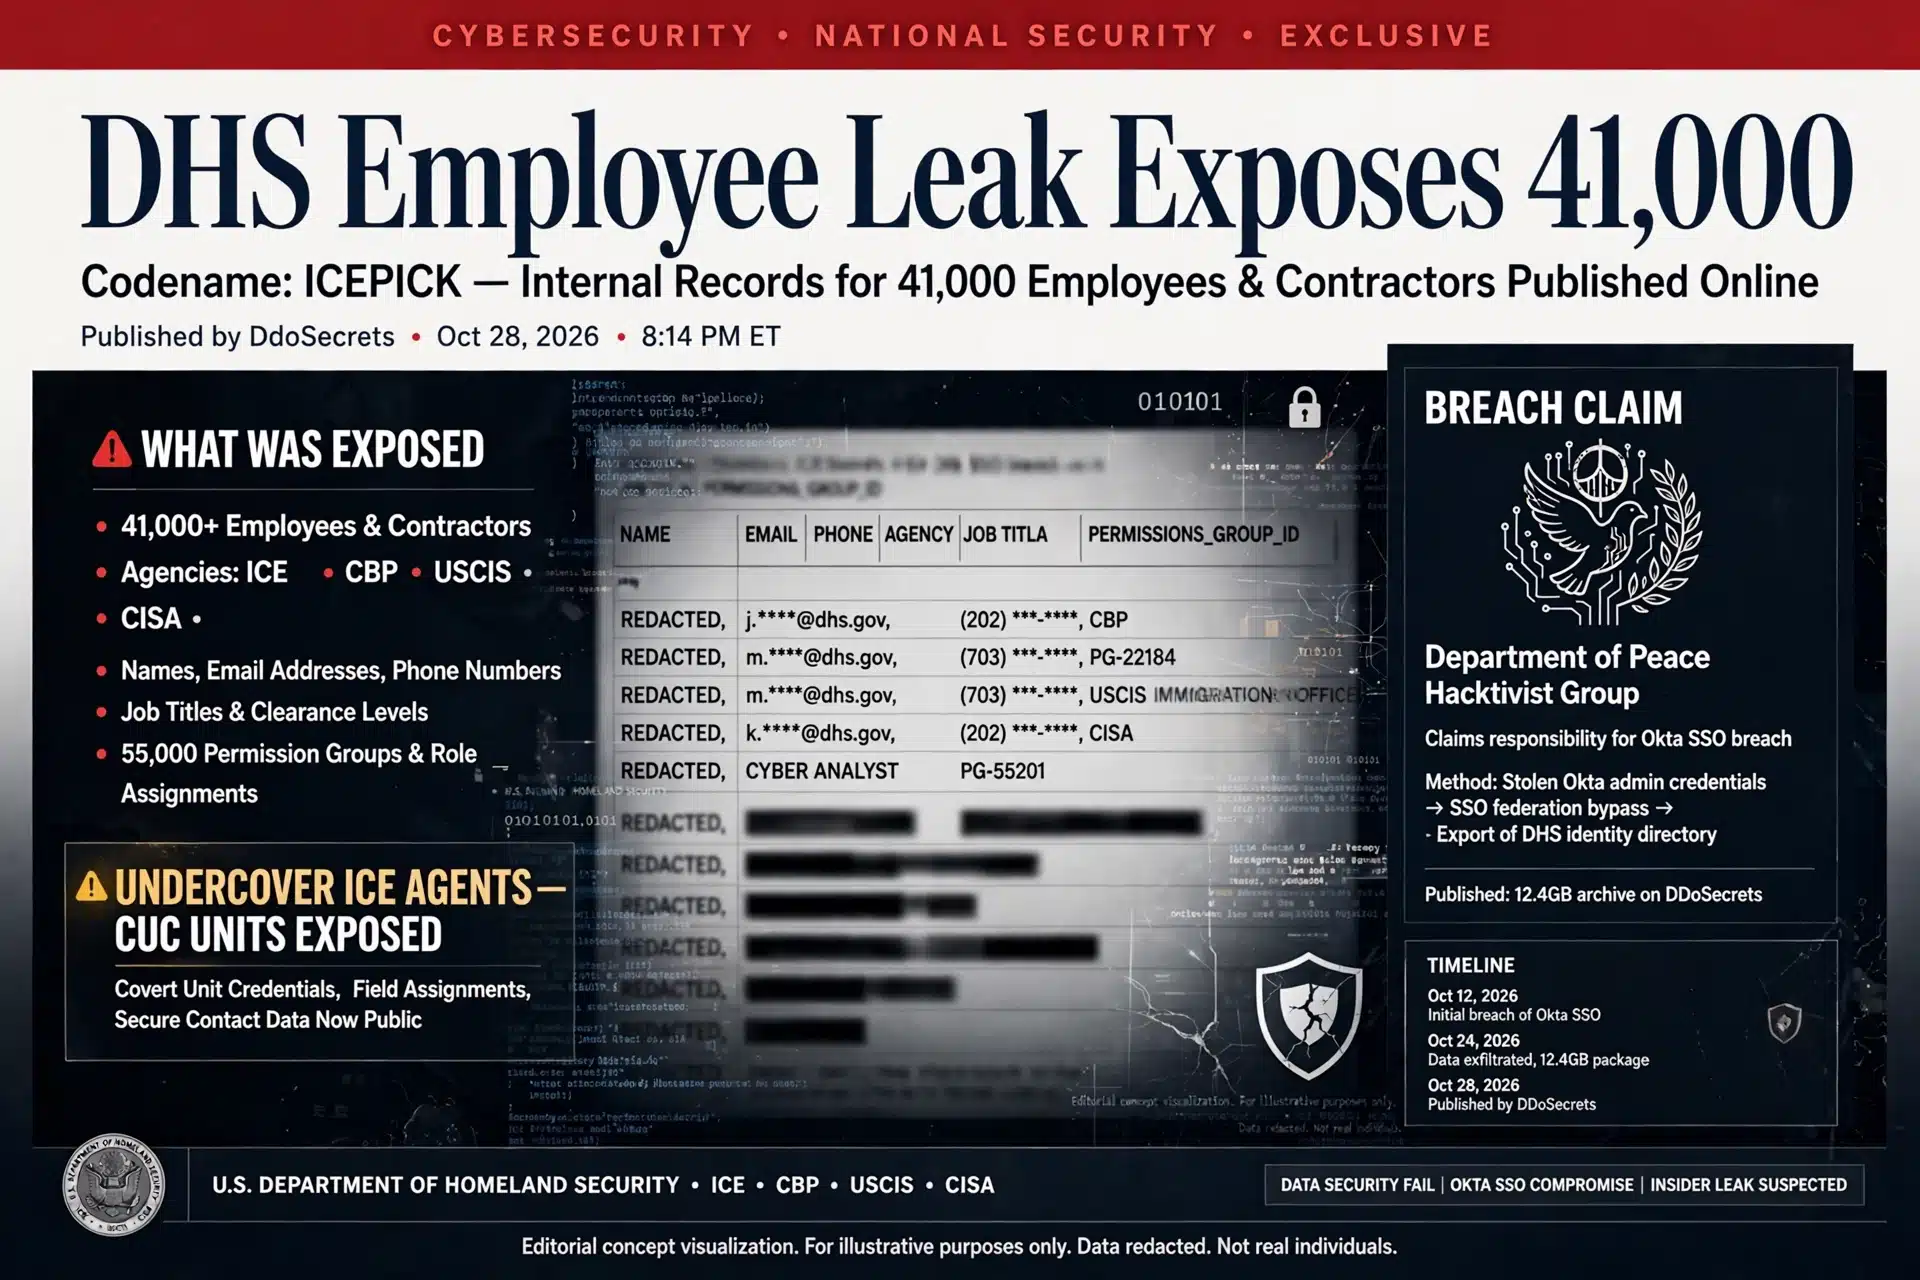
DHS Employee Leak Exposes Contact Data on 41,000+ Workers

A hacktivist group published a 166 MB database of contact and personnel information on more than 41,000 current and former Department of Homeland Security employees on October 28, 2026, and the DHS employee leak is now one of the largest federal personnel exposures on record. Distributed Denial of Secrets, a transparency nonprofit, released the dataset under the name Icepick. DHS says it is aware of a potential breach; Okta denies its systems were compromised. Here is what is in the data, how it likely got out, and what federal workers should do.

Key Takeaways:

  • – DDoSecrets published the Icepick dataset on October 28, 2026, covering more than 41,000 current and former DHS employees and contractors.
  • – Exposed fields include names, work emails, phone numbers, job titles, offices, supervisors and internal permission-group memberships.
  • – The hackers traced the data to an Okta single sign-on service used by DHS; Okta says it has no evidence of a compromise.
  • – WIRED’s analysis found CBP accounts for more than half the records and ICE about 10,000, including staff tied to undercover units.
  • – Independent outlet Nextgov verified portions of the dataset, including phone numbers and matching LinkedIn profiles.

What the Icepick DHS employee leak contains

The dataset is an internal directory export, not a financial or credential dump. Records identify staff across DHS headquarters and seven component agencies, roughly one-seventh of the department’s workforce. WIRED’s breakdown counts more than half from Customs and Border Protection, about 10,000 from Immigration and Customs Enforcement with roughly a third in Homeland Security Investigations, about 6,200 from USCIS, and about 1,000 from CISA, more than half of those contractors. The data was last updated August 19, 2026, so some records describe staff who have since moved on.

The sensitive part is not names and emails, which business cards or agency sites could produce, but the internal group memberships. WIRED documented references tied to undercover operations units, a Title III intercept program for court-authorized wiretaps, communications intercept technical teams, the Palantir Falcon platform, the PenLink analytics tool, a CBP face-recognition app with about 200 accounts, and about 700 Signal accounts. Dozens of records identify 287(g) officers embedded with county sheriff offices, and about 4,400 entries are associates, mostly contractors.

How the hackers say they got in

The group, calling itself Department of Peace, told DDoSecrets the data came from an Okta single sign-on service DHS uses. Okta, the identity company whose customer base spans most of the Fortune 500, rejected that framing directly, saying it is secure and has no evidence its data or systems were compromised. That leaves two possibilities: a misconfiguration or over-broad sync on DHS’s tenant exposed directory data without any breach of Okta itself, or an intrusion into a downstream system Okta did not originate. DHS has said only that it is aware of a potential breach; it has not confirmed the dataset’s authenticity.

What strengthens the picture is independent corroboration. Nextgov verified portions of the data, including an official’s work phone number it had obtained separately, AT&T-associated numbers consistent with DHS’s carrier, and matching LinkedIn profiles. CyberScoop verified numerous current CISA employees plus former leadership. Both outlets also found stale or historical records, a reminder that directory exports age fast and headlines claiming all 41,000 people are exposed overstate the current data.

Why this DHS employee leak is a security event, not just a privacy one

Work emails and cell numbers plus org charts are the raw material for targeted phishing, impersonation, and credential-reset attacks against specific federal staff. Security analysts quoted by WIRED called the dataset, if authentic, extraordinarily valuable to anyone trying to penetrate DHS, especially when correlated with prior breach data and commercial records. The group framed its motive as retaliation for immigration enforcement policy, citing a July 17 public vow by Secretary Markwayne Mullin to escalate enforcement, which makes targets selected for policy rather than for vulnerability, a pattern that historically escalates rather than subsides.

There is also a legal and speech dimension. DDoSecrets frames Icepick as an accountability tool akin to FOIA material rather than doxing, and civil-liberties attorneys argued basic business-card details are protected speech. WIRED reported the social platform Bluesky blocked links to the leak. DHS has spent the year expanding doxing enforcement, so expect the dispute to move toward prosecution attempts and First Amendment litigation rather than fading like an ordinary breach story.

What federal employees and contractors should do

The practical steps mirror any targeted-exposure incident. Assume targeted phishing: any message referencing your unit, supervisor, or an internal system name is now possible for strangers to craft, so verify sender identity out of band before clicking. Enable phishing-resistant multi-factor authentication, FIDO security keys over SMS. Review agency guidance before discussing the leak at work, since personnel rules still apply. If your record ties you to sensitive units, report unusual approaches to your security office promptly. Contractors should notify their contracting officer too, because incident-response obligations differ from federal staff.

The history and the open question of authenticity

This is not DHS’s first large personnel exposure. CyberScoop’s reporting cites a 2014 incident potentially affecting 390,000 DHS employees, applicants and contractors, and a separate 2018 notification to nearly 250,000 people. What distinguishes Icepick is intent and packaging: the 2014 breach was accidental, while this dataset was published deliberately as a searchable accountability archive, which is a different threat model for affected staff and a different legal posture for the publisher. WIRED also contextualizes it alongside a ShinyHunters claim of stolen data on nearly every FBI employee, suggesting coordinated releases against federal agencies rather than a lone incident.

The unresolved authenticity question matters more than usual here. DHS has acknowledged only a potential breach, Okta denies compromise, and independent outlets verified samples, not the full set. If incident response later shows the export came from a misconfigured tenant with no intrusion, the remediation is policy, not forensics. If it shows an intrusion into personnel systems, that is a named actor case with breach-notification obligations cascading through contractors. Both outcomes are live until DHS speaks specifically, and the department’s silence so far is itself information.

What happens next

Watch three threads. DHS and Congress: expect oversight letters asking whether the data originated in an Okta tenant misconfiguration or an intrusion, and how directory exports are access-controlled. Okta: the company’s denial will be tested by incident-response findings, and its stock and enterprise customer trust hang on the answer. And the search tool: DDoSecrets says the first searchable domain, icepi.cx, was taken offline by its registrar, with a mirror moved to icepicx.is, so availability stays volatile. This is a developing story, and the authenticity question DHS has left open is the single fact that determines whether it remains a leak story or becomes a named intrusion case.

Frequently Asked Questions

What is the Icepick DHS leak?

A 166 MB database of contact and personnel information on more than 41,000 current and former DHS employees and contractors, published by the nonprofit Distributed Denial of Secrets on October 28, 2026 at the claim of a hacker group called Department of Peace.

Was Okta breached in the DHS hack?

The hackers attributed the data to an Okta single sign-on service used by DHS, but Okta says it has no evidence its systems were compromised, and DHS has not confirmed the dataset’s authenticity or the intrusion path.

What should DHS employees do after the leak?

Treat the exposure of work contacts and group memberships as phishing ammunition: verify unexpected contacts out of band, use phishing-resistant multi-factor authentication, follow agency security guidance, and report any suspicious approaches, especially if your record references sensitive units.

Sources:

Army Future Interceptor Program Goes to Lockheed for $1.08B

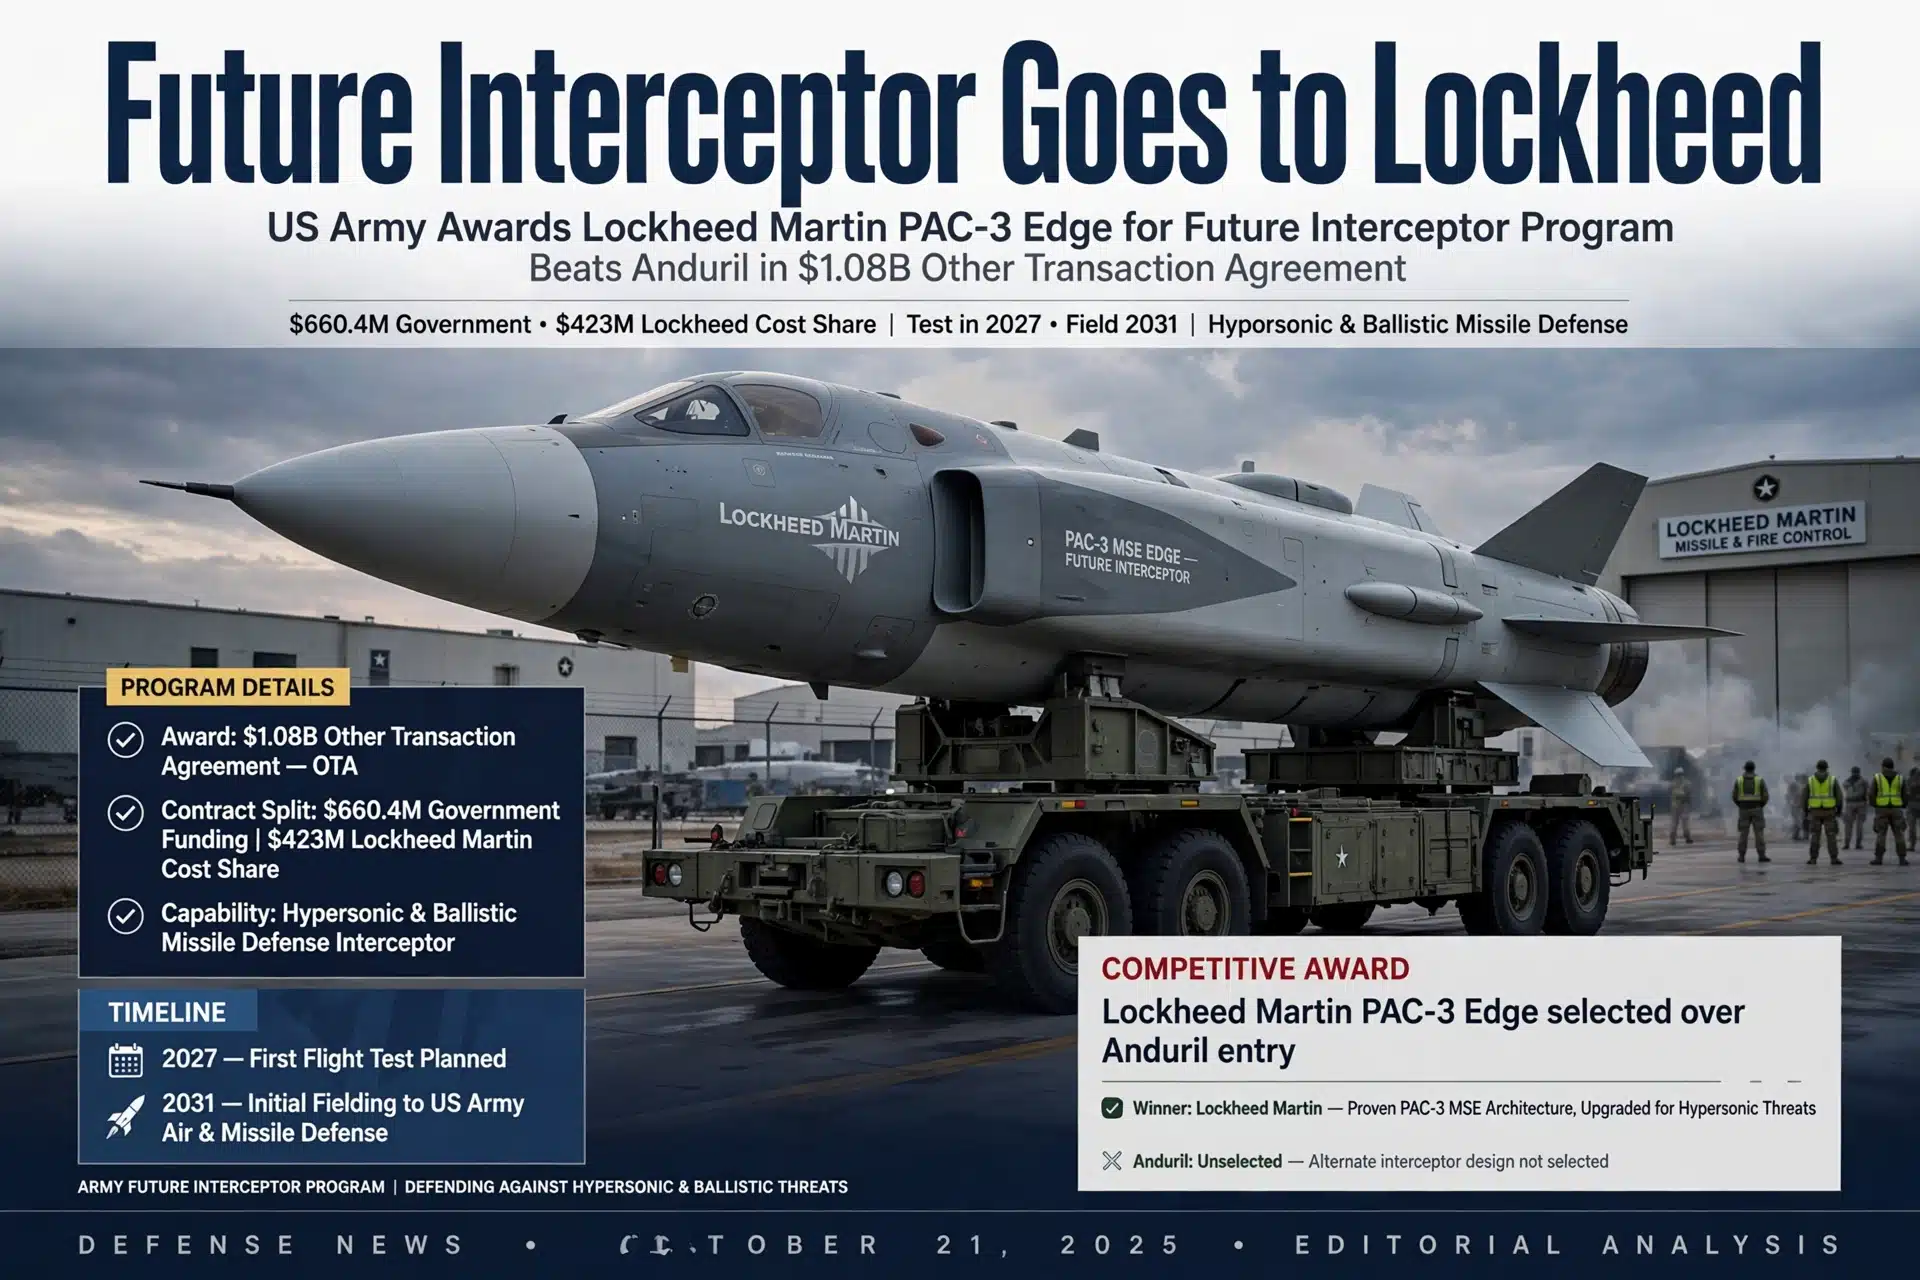
The Army announced on October 29, 2026 that Lockheed Martin won the Future Interceptor program, a $1.08 billion prototype-and-development competition to build the successor to the PAC-3 Missile Extended Range interceptor. The award, structured as an Other Transaction Agreement, beat rival Anduril and hands the Army the Future Interceptor program’s most consequential decision of the year. Here is what the Army is buying, why the funding structure matters, and when shooters could see the new round in the field.

Key Takeaways:

  • – Lockheed Martin won the Army’s Future Interceptor competition, announced October 29, 2026 in Huntsville, Alabama.
  • – The effort is valued at $1.08 billion: $660.4 million in government funding plus $423 million of Lockheed cost share.
  • – The winner is the PAC-3 Edge, built on the combat-proven PAC-3 MSE with a new seeker and a Northrop Grumman multi-pulse motor.
  • – Lockheed plans to begin testing in 2027 and field the interceptor by 2031, and it beat Anduril for the award.
  • – follow-on development and production are not guaranteed; decisions hinge on prototype performance.

What the Future Interceptor program is buying

The competition asked industry for a next-generation interceptor with improved engagement range, altitude, velocity, and maneuverability compared with the interceptors flying today in Patriot and Army Integrated Air and Missile Defense units. The requirement grows out of two intensity lessons: magazine depth matters when facing large raid sizes, and maneuvering hypersonic threats punish interceptors designed a decade ago. The Army wants a round that complements, not replaces, the existing layered architecture against ballistic missiles, cruise missiles, and jet-powered attack drones.

The winning design, PAC-3 Edge, was unveiled by Lockheed on October 9, 2026. It retains the PAC-3 MSE hit-to-kill heritage, the interceptor credited with the majority of successful Patriot engagements against ballistic threats in recent combat use, while swapping in a new Strigo Product Center seeker from Lockheed and a Northrop Grumman multi-pulse solid rocket motor whose pulses can be timed for different engagement profiles. Lockheed designed it for integration with the Army’s IBCS battle command system, existing M903 launchers, containerized launchers, and HIMARS Flex, which lets fielded units adopt it without new launch infrastructure.

Why the $1.08 billion deal is structured as an OTA

The award is an Other Transaction Agreement rather than a traditional FAR-based contract, and the money split tells the story: the government contributes $660.4 million while Lockheed puts up $423 million of its own capital, roughly 39 percent of the total. The Pentagon has leaned on OTAs since the 2010s to escape procurement rules it views as slow, and the cost-share design spreads risk: if PAC-3 Edge fails in prototype testing, taxpayers have not carried the full development bill, and the Army keeps an off-ramp.

Army officials framed it the same way. Brent Ingraham, the service’s acquisition executive for aviation and missile programs, said the arrangement is meant to reduce acquisition risk, while Lieutenant General Frank Lozano, the Portfolio Acquisition Executive for Fires, described it as a way to accelerate innovation by building on proven technology. General Christopher LaNeve, the Vice Chief of Staff serving as Acting Chief of Staff, tied the buy to the Army’s new warfighting guidance, How the Army Fights, with its mix of exquisite and low-cost munitions. Follow-on decisions, the Army notes, will be informed by prototype performance, operational requirements, available resources and applicable acquisition processes.

Lockheed versus Anduril and what it signals

Anduril pitched a cheaper, modular alternative called Steelfin, unveiled October 12, 2026, and for a company riding a string of recent defense wins, the loss stings. Aviation Week reported Lockheed prevailed in the head-to-head. The result signals how the Army weighs risk on its most safety-critical magazine items: against a startup’s cost advantage and software-forward pitch, the incumbent’s flight-test history and existing missile factory footprint won. It also tightens Lockheed’s already dominant position in Army air defense, following the $58.6 billion multiyear PAC-3 MSE production deal signed in July.

For Congress and oversight bodies, that concentration is the predictable next question, and it lands while Lockheed separately weighs an expansion of munitions capacity estimated at up to $9 billion across PAC-3, THAAD, and PrSM production lines. The Counter small-drone world, meanwhile, is drifting toward low-cost effectors such as microwave systems and cheap interceptors, so a billion-dollar program for an exquisite round coexists awkwardly with a parallel push for magazine depth on a budget. The Army’s answer is that this round targets the threats the cheap rounds cannot reach; the test will be whether both lines survive budget pressure together.

The four things to watch in the 2027 test campaign

Prototype testing in 2027 will answer the questions the award leaves open. Range-and-altitude demonstration: whether the new motor pulses and seeker deliver the engagement envelope the requirement demanded against maneuvering threats. Producibility: whether the design can be built on existing PAC-3 lines without a new factory, which determines if the 2031 fielding date is real or aspirational. Integration: whether IBCS cueing and existing M903 and HIMARS Flex launchers adopt the round without hardware changes. And unit cost: the Army’s stated preference for a mix of exquisite and low-cost munitions only works if this exquisite round’s cost stays predictable across production lots.

The fiscal context sharpens each of those. The Army has been pacing PAC-3 MSE production against burning demand, and every dollar of the $1.08 billion program competes with warhead, radar and C2 modernization inside the same missile-defense budget line. A clean test campaign cementing a Navy second customer, as Lockheed’s Modular Missile pitch would, muddies that trade; a slip does the opposite.

What happens next

The development clock is aggressive: Lockheed plans prototype testing beginning in 2027 and fielding by 2031. Watch the fiscal 2027 budget request for whether the Army carries the program’s growth beyond the OTA, the first flight-test results out of White Sands in late 2027, and one secondary front: Lockheed president Tim Cahill told Aviation Week the PAC-3 Edge is a candidate for the Navy’s Modular Missile Terminal Stage Interceptor competition, which would add a sea-based customer and dilute unit costs. If the Navy adopts it, the program’s economics improve sharply. If the prototype slips past 2027, expect Anduril’s Steelfin and other competitors to lobby for a restart.

For US readers the through line is interceptor magazine depth: the Patriot fleet has been spending rounds faster than production lines can replace them, and this program is the hedge that a next-generation, producible round arrives before the stockpile math becomes critical.

Frequently Asked Questions

What is the Army Future Interceptor program?

It is the Army’s competition to develop a next-generation interceptor with better range, altitude, speed and maneuverability than today’s PAC-3 family, structured as a prototype effort with an October 29, 2026 award to Lockheed Martin.

How much does the Future Interceptor deal cost?

The development effort is valued at $1.08 billion, split between $660.4 million in government funding and $423 million from Lockheed Martin as cost share under an Other Transaction Agreement.

When will the Future Interceptor field?

Lockheed plans testing to begin in 2027 and fielding by 2031, subject to prototype performance; follow-on production is not guaranteed under the award structure.

Sources: