USCIS Enforcement Actions Reach 2.2 Million in Under Two Years

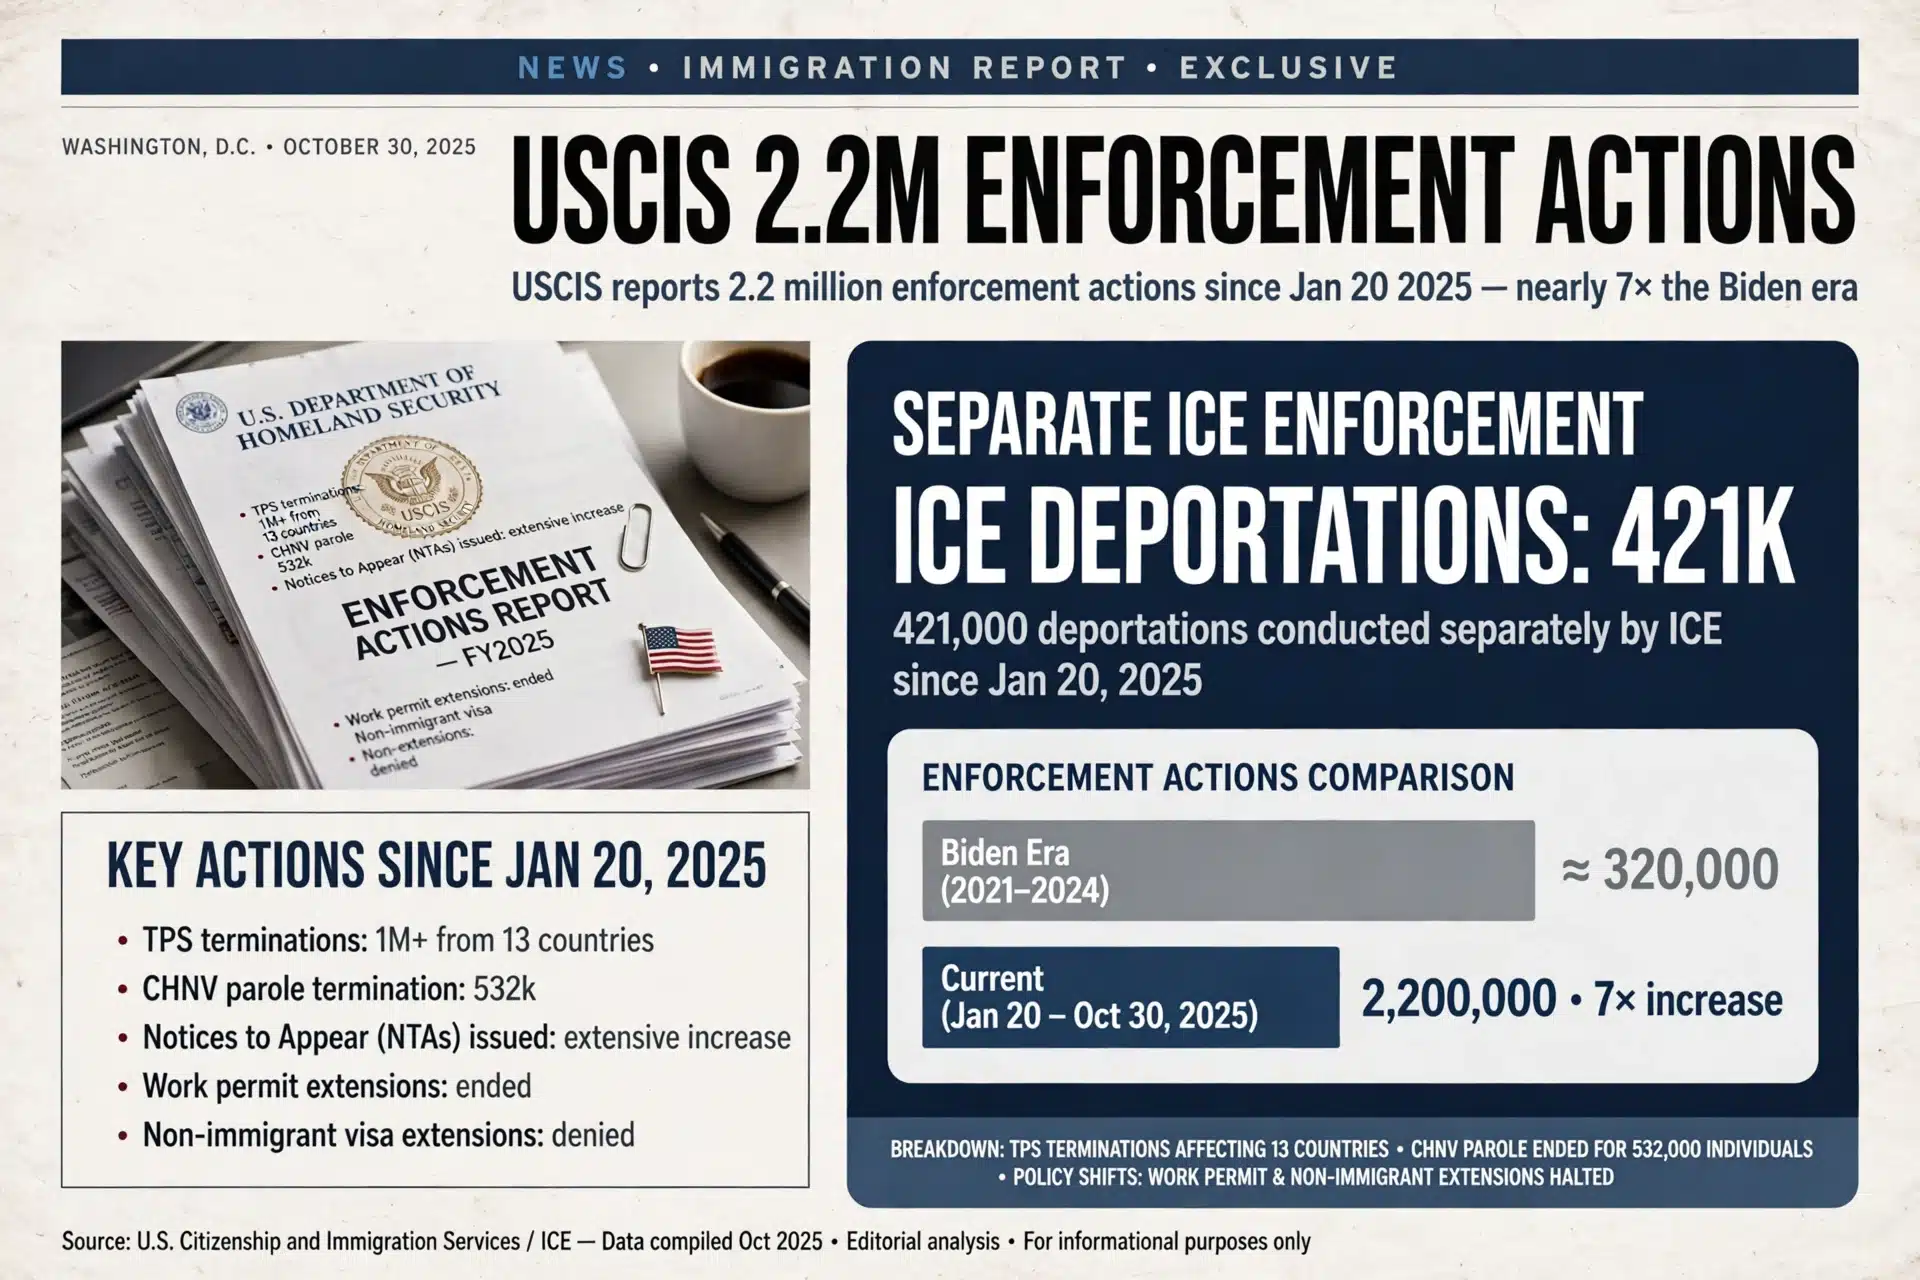
USCIS announced on October 29, 2026 that it had carried out USCIS enforcement actions to revoke or terminate the status of roughly 2.2 million people since January 20, 2025, a figure the agency calls unprecedented and read on Capitol Hill and campaign trails alike this week. The announcement lands five days before the November 3 midterms, and the paper trail behind it shows the count is not a deportation total. Here is what the number contains, who is actually affected, and what happens next for the people inside it.

This article is informational and not legal advice; individuals with status questions should consult a licensed immigration attorney or an accredited representative.

Key Takeaways:

  • – USCIS announced on October 29, 2026 that approximately 2.2 million people have had status revoked or terminated since January 20, 2025.
  • – The count spans five categories: TPS terminations, extension denials, Notices to Appear, ending automatic EAD extensions, and terminating categorical parole.
  • – TPS terminations cover more than 1 million nationals of 13 countries, and the CHNV parole program covered about 532,000 travelers.
  • – Some TPS terminations are enjoined in ongoing litigation, so not every counted action is currently in force.
  • – No category-by-category breakdown has been published, which makes the headline figure impossible to audit independently.

What the 2.2 million figure actually counts

The USCIS release lists five categories of action. Terminating Temporary Protected Status designations, described as making TPS truly temporary again. Denying extensions or changes of nonimmigrant status when the agency finds no legal basis to continue. Issuing Notices to Appear in immigration court, which formally opens removal proceedings. Ending automatic extensions of Employment Authorization Documents, a change that hits green-card applicants who relied on continued work authorization while their pending cases sat in backlogs. And terminating categorical parole programs in favor of case-by-case parole decisions.

Two programs dominate the arithmetic. TPS terminations for more than 1 million nationals across 13 countries form the largest block, though several of those terminations are tied up in court. The CHNV parole process, which had allowed Cubans, Haitians, Nicaraguans and Venezuelans to enter with sponsors, covered about 532,000 people per DHS’s March 2025 Federal Register notice. An attorney analysis published the same day estimates the two programs account for roughly 70 percent of the total. The remaining categories, including Notices to Appear and EAD extension ends, fill out the rest without published subtotals.

Why this is not a deportation count

The most important caveat in the announcement is definitional. Revoking a status or terminating a program designation is an administrative action, not a removal. DHS has not confirmed that all 2.2 million people actually lost legal status, and it cannot yet, because some TPS terminations, including litigated designations, are enjoined pending appeal. Commentators and the agency itself both flagged the distinction, and the absence of a category breakdown means duplicate actions, such as a TPS holder who also received a Notice to Appear, may or may not be de-duplicated inside the total.

That does not make the number meaningless. It changes what it measures. The release is a scoreboard of administrative tightening: hundreds of thousands of people whose work authorization lapsed, whose pending petitions were denied, or whose court dates were set. For employers running I-9 compliance checks and for households relying on a single paycheck, those administrative consequences are as disruptive as formal removal in the short term, even though the legal avenues differ sharply.

Who is affected in practice

The affected population is no longer primarily recent arrivals. TPS holders from countries including Haiti, Venezuela, Honduras, El Salvador, Nicaragua and others have lived and worked in the US for years, many with US-citizen children and mortgages. CHNV parolees arrived under a program that required sponsors and flights, meaning many arrived with existing ties to US communities. The end of automatic EAD extensions ripples to green-card applicants in employment-based backlogs, who now face work-authorization gaps that can cost jobs, and to the US employers who sponsored them.

Adjacent figures released in the same week frame the broader enforcement picture. ICE reported about 421,182 removals between October 2025 and August 24, 2026 in its September report. The White House said in October that more than 300,000 visas had been revoked overall, including roughly 4,000 birth-tourism visas and about 6,000 held by foreign students with criminal or security flags. These sit alongside, not inside, the 2.2 million USCIS figure, and conflating them in coverage has been a recurring error this week.

How the number compares with prior administrations

The release frames the total as nearly seven times what the prior administration produced in its final two years, which implies a baseline of roughly 315,000 comparable actions, and the framing itself tells you how the milestone is meant to be used politically. Congressional Research Service reporting counts 13 of 17 TPS designations as terminated so far, most of them contested. For context, the CHNV parole program alone processed about 532,000 travelers in roughly 15 months, which shows the same administrative machinery installed people at speed even faster than it is now removing their status. Whether sevenfold speed in one direction cancels sixfold speed in the other is exactly the argument the midterms will answer.

Employers are the quiet audience for this announcement. The end of automatic EAD extensions means HR teams must now track expiration dates for employees in employment-based backlogs, request interim evidence, and budget for recourse when extensions are denied, work that previously ran on autopilot. The Department of Homeland Security has not published employer guidance alongside the milestone release, so trade associations are fielding the questions USCIS paperwork used to answer.

What happens next

Three developments will determine whether the milestone holds. Litigation: several TPS terminations remain before appellate courts, and a ruling in the coming months could restore status for a meaningful share of the count. Publication: if USCIS or DHS releases a category breakdown, the figure becomes auditable and its political use changes from talking point to dataset. And the midterm aftermath: with the announcement timed five days before November 3, expect it in campaign advertising this week and in budget or oversight hearings afterward, where DHS officials can be asked to reconcile the number against program-level records.

For individuals inside the affected groups, the practical steps have not changed since the underlying program terminations were first announced: check your EAD card against the automatic-extension rule in effect for your category, confirm any pending USCIS case status before making job or lease decisions, and respond to any Notice to Appear, because missed hearings are a leading cause of in-absentia orders. Community legal aid organizations remain the fastest free resource for confirming which of the five categories, if any, applies to your file.

Frequently Asked Questions

Does the 2.2 million figure mean 2.2 million people were deported?

No. It counts administrative actions, including status revocations, program terminations, extension denials, and Notices to Appear. ICE separately reported roughly 421,182 removals from October 2025 through late August 2026.

Which groups are inside the USCIS enforcement actions total?

Mostly TPS holders from 13 terminated designations, about 1 million people, and CHNV parole beneficiaries, about 532,000, plus Notices to Appear recipients, denied extensions, and people who lost automatic EAD extensions.

Is the 2.2 million number verified?

It is an official USCIS claim, but no category-by-category breakdown has been published and some counted TPS terminations are enjoined in litigation, so the total cannot be independently audited yet.

Sources:

CDC’s Ebola Attestation Order Tightens Rules for US-Bound Air Travel

The CDC amended its Ebola attestation order on October 28, 2026, and the change is significant for anyone flying to the United States: airline crews are now covered alongside passengers, and no traveler from an affected list of countries can board without a signed statement that they were not in the Democratic Republic of the Congo in the prior 21 days. The Ebola attestation order takes effect at 11:59 p.m. EST on November 3 and runs through December 18, 2026. This explainer covers who is affected, what airlines say, and what US travelers should actually do.

This article is informational and not medical or legal advice; travelers with specific health or visa questions should consult a clinician or licensed immigration counsel.

Key Takeaways:

  • – CDC issued an amended order on October 28, 2026, published in the Federal Register on October 30, requiring attestations from all persons arriving in the US by air.
  • – The amendment changed passenger to person so crew members, including cargo pilots and deadheading crews, are covered for the first time.
  • – Airline groups American Airlines-backed A4A and IATA asked CDC to delay the November 3 start date, citing two weeks of technical lead time.
  • – CDC reports no Ebola cases linked to the current outbreak in the US, with a low overall risk level for the American public.
  • – False attestations can be referred to the Department of Justice under the federal false-statements statute.

What the amended Ebola attestation order requires

The original order, signed October 22 and published in the Federal Register on October 27, barred boarding for any passenger on a US-bound flight unless that passenger presented a signed attestation, paper or digital, confirming no physical presence in the DRC during the 21 days before boarding. Airport transit counts as presence, even without leaving the aircraft. The October 28 amendment broadens the requirement to crews, applies to flights connecting through the United States, and exempts aircraft carrying authorized Ebola patients and travelers with individual CDC humanitarian or government exemptions.

Airlines must collect and retain attestations for 42 days after departure and can be compelled to hand them to the US government. Carriers may refuse boarding to anyone who will not sign. The order rests on the Public Health Service Act and its implementing regulations at 42 CFR 71.20 and 71.31 through 71.32(b). A companion Paperwork Reduction Act notice is open for comment at regulations.gov under docket CDC-2026-1750. Land borders and seaports are not covered, which becomes a central point of the airline pushback.

The outbreak behind the rule

The DRC declared its 17th Ebola outbreak in May 2026, caused by the Bundibugyo virus, and CDC’s situation page, updated October 29, counts 10,224 confirmed cases and 4,964 confirmed deaths as of October 27 across the affected region: 10,193 cases in the DRC itself, 20 in Uganda, 9 in Kenya, and 1 each in Nigeria and France. CDC describes it as the second-largest Ebola outbreak on record and notes it surpassed 1,000 confirmed cases within 40 days, roughly six times faster than the 2018 outbreak reached that mark.

Against those numbers, the screening logic is arithmetic: the virus has a 21-day incubation window, so a traveler with no DRC exposure in that window is extremely unlikely to be infectious on arrival. CDC’s guidance for US-bound travelers who were in the DRC is to remain outside the country for 21 days, with return permitted from day 22, and heightened screening applies at designated airports for travelers transiting Uganda and South Sudan. The agency counts roughly 500 staff on the response, more than 120 of them deployed overseas.

Why airlines are pushing back

Airlines for America, representing American, Delta, United and Southwest, wrote to CDC’s Division of Global Migration Health on October 26, and IATA wrote on October 27, urging a delay of the November 3 deadline. Their arguments, reported by Reuters on October 29: only about two weeks to rebuild check-in systems, capture electronic signatures, and train agents worldwide; some European hubs carry roughly 75 percent connecting passengers with boarding windows as short as one hour; and CBP screened about 130 million air passengers in 2025 with fewer than 25,000 holding any DRC connection, so the odds the rule ever catches a case are small while compliance costs are certain.

The groups also flagged the asymmetry with Canada and the United Kingdom, which rely on narrower travel-history-based measures rather than blanket attestations, and with US land and sea entry points, which face no equivalent requirement. CDC amended the order on October 28 but expanded coverage to crews rather than delaying the effective date. Enforcement teeth sat with carriers; the Transportation Department issued an enforcement notice on October 28 confirming airlines may deny boarding, including to US citizens, but must offer a rebooking, a prompt refund, or a transferable travel credit valid at least five years, with a written explanation within 10 days on request.

What US travelers should do now

First, check your itinerary against the requirement before November 3. Any onward journey routed through DRC airports, even an airside connection, triggers the attestation problem, so rebook or reroute through hubs outside the DRC if your trip window overlaps. Second, US citizens are not exempt: the attestation applies to all persons, and DOT’s notice confirms carriers can deny boarding to Americans as well, so travelers returning from DRC-adjacent itineraries should build refund flexibility into bookings. Third, if you were in the DRC within 21 days and need to reach the US, plan the 21-day wait outside the country rather than attempting an attestation you cannot honestly sign; false statements carry DOJ referral risk under 18 U.S.C. 1001.

Finally, note the expiration. The order lapses at 11:59 p.m. EST on December 18, 2026, squarely in peak holiday international travel. An extension or rescission will turn on case counts, geographic spread, and containment capacity in central Africa, so travelers booking December itineraries should expect the rule to still be in force and check CDC’s order page within 72 hours of departure.

What happens next

Watch three markers. Whether CDC grants any operational delay or exemption tweaks after the airline letters, expected in the final week before November 3. Whether the Federal Register docket at regulations.gov draws significant public comment, which shapes how the rule gets litigated or renewed. And whether a first confirmed US-linked case emerges, which would transform a low-risk screening measure into a politically durable policy. For now, the practical reality for US-bound flyers is simple: from November 4, the attestation is the price of admission, crews and passengers alike.

Frequently Asked Questions

Who must sign the CDC Ebola attestation?

Every person aboard a US-bound flight, including US citizens, children signed by a guardian, connecting passengers through airports transiting the DRC, and, since the October 28 amendment, crew members on both passenger and cargo flights.

When does the Ebola travel rule take effect?

At 11:59 p.m. EST on November 3, 2026, and it remains in effect through 11:59 p.m. EST on December 18, 2026, unless CDC extends or rescinds it.

Can an airline deny me boarding if I refuse the attestation?

Yes. Carriers may refuse boarding without a signed attestation, and a Department of Transportation notice confirms that denial is permitted, though airlines must then offer rebooking, a refund, or a transferable credit and provide a written explanation.

Sources:

Apple’s MacBook Pro Touchscreen Breaks a 10-Year Company Rule

Apple announced the first touchscreen MacBook Pro on October 28, 2026, ending a decade-long stance that touch does not belong on a laptop. The new MacBook Pro touchscreen pairs a tandem-OLED PROLED XDR panel with M5 Pro and M5 Max chips, preorders opened the same day, and the 14-inch model starts at $2,899 with US availability from November 6. Here is what changed, what it costs, and whether US buyers should upgrade before the holidays.

Key Takeaways:

  • – Apple unveiled the MacBook Pro with PROLED XDR Display, its first Mac laptop with touch input, at the October 28 Pro and tell event.
  • – US pricing starts at $2,899 for the 14-inch and $3,399 for the 16-inch, both with M5 Pro; M5 Max models start at $4,499.
  • – A maxed-out 16-inch with 128GB memory, 16TB storage and nano-texture glass reaches $14,549.
  • – Preorders opened October 28 and the first units ship Friday, November 6, 2026.
  • – The entry 14-inch is $400 above the prior generation, an OLED and touch premium over the M6 models sold alongside it.

What the MacBook Pro touchscreen actually adds

The headline change is a tandem-OLED panel Apple brands PROLED XDR. It delivers up to 2,000 nits of peak brightness in both HDR and standard content, a 10,000,000:1 contrast ratio, and adaptive refresh from 10Hz to 120Hz. Apple removed the notch in favor of a Dynamic Island that houses Spotlight, Live Activities, and Siri. The touch sensor sits inside the panel stack rather than layered on top, which cuts latency and keeps the display thin. A redesigned hinge stabilizes the screen when you tap or drag it.

The catch is macOS itself. Apple has not rebuilt the operating system around touch the way iPadOS is; taps largely map to clicks, and the payoff depends on the app. Creative tools are where it shows: Lightroom sliders, DaVinci Resolve scopes, Blender viewports, and canvas apps like Notion and Canva all benefit from direct manipulation. If your work lives in spreadsheets and terminals, the touch layer is a nice-to-have rather than a reason to upgrade, and hands-on reviews will matter more than the spec sheet before spending this much.

Pricing: what the premium buys

Per MacRumors’ price tables, the 14-inch starts at $2,899 with an M5 Pro, 24GB of memory and 1TB of storage, up from $2,499 for the previous base model. The 16-inch starts at $3,399, up from $2,999. M5 Max configurations begin at $4,499 and $4,799. The ceiling is genuinely high: 128GB of unified memory, a 16TB SSD, and the nano-texture finish push the flagship 16-inch to $14,549, with the storage upgrade alone contributing $7,000. Apple is clearly leaning into the pro segment it named the event after.

Portability improved at the same time. Apple lists the new 14-inch at 3 pounds and the 16-inch at 4 pounds, with the chassis roughly half a millimeter to a full millimeter thinner depending on size. Displays grew slightly to 14.2 and 16.3 inches. The machine keeps three Thunderbolt 5 ports, HDMI, an SDXC slot, MagSafe charging, Wi-Fi 7, Bluetooth 6, a 12MP Center Stage camera, and a six-speaker system Apple says produces 50 percent deeper bass, with up to 24 hours of battery life.

How it compares to the cheaper M6 models

Buyers now face a fork. Apple sells this touchscreen machine alongside the M6 14-inch MacBook Pro and the M6 iMac announced the day before, both of which undercut the OLED line by hundreds of dollars. The M5 Pro and M5 Max chips inside the touchscreen models are last-generation silicon by name, but paired with the new display they target a different buyer: colorists, photographers, and video editors who bill by the accuracy of what they see. For general productivity, coding, and schoolwork, the M6 machines deliver more value per dollar, and that is the honest recommendation for most US households this holiday season.

There is also a storage-economics warning. The 16TB SSD option reflects ongoing memory and NAND pricing pressure across the industry, and paying $7,000 for storage that cloud services or an external drive could replace at a fraction of the cost is hard to defend for most workflows. Buy the storage tier you need today rather than the one you might need in three years.

Why Apple changed its mind about touch

Apple spent roughly fifteen years arguing against laptop touchscreens; Steve Jobs famously called them ergonomically terrible in 2010. The reversal tracks with a broader run of firsts under new CEO John Ternus: the HomeView smart display, the iPhone Duo foldable, and now this. Each moves a product category Apple once defended by tradition. The likely driver is the growing overlap between iPad Pro workflows and Mac workflows, where artists and editors increasingly split time between the two and asked why the Mac could not take direct input.

Hardware context matters too. Tandem OLED allows the bright, thin panel while the in-panel touch sensor avoids the thicker capacitive stacks that made early touch laptops clunky. Competing Windows machines have shipped OLED touch panels for several years, and Apple entering that market with a 120Hz, 2,000-nit panel is both a catch-up and a statement that it intends to lead on image quality rather than arrive late on specs.

What happens next

Shipments begin November 6, about three weeks before Black Friday. Apple almost never discounts brand-new Macs, so expect trade-in credits and gift-card promotions rather than price cuts; if a deal is the priority, watch refurbs of the previous mini-LED models instead. Reviews landing in early November will answer the two open questions that matter: thermals under sustained M5 Max loads in a thinner chassis, and how tolerable macOS click-mapped touch is in daily creative work. If either disappoints, the M6 non-touch line becomes the default holiday recommendation without changing a single accessory purchase.

For US buyers deciding this week, the decision rule is simple: if color-critical visual work pays your bills, the $2,899 entry point is a real tool and the OLED panel justifies the premium. For everyone else, preorder nothing and let the first hands-on reports arrive before the Black Friday window.

Frequently Asked Questions

How much does the touchscreen MacBook Pro cost in the US?

The 14-inch starts at $2,899 and the 16-inch at $3,399, both with M5 Pro, 24GB of memory and 1TB of storage. M5 Max models start at $4,499, and a fully loaded 16-inch reaches $14,549, per MacRumors’ pricing breakdown.

When can US customers get the MacBook Pro touchscreen?

Preorders opened October 28, 2026, and the first units become available Friday, November 6, 2026, in time for the holiday shopping season.

Does macOS really support touch on the MacBook Pro?

Yes, but conservatively. The operating system maps most touches to clicks, so the benefit shows up in touch-friendly creative apps rather than a tablet-style interface. Reviewers’ hands-on reports in early November will show how it feels in practice.

Sources:

Microsoft’s $25 Billion Bond Sale Puts AI Debt in the Spotlight

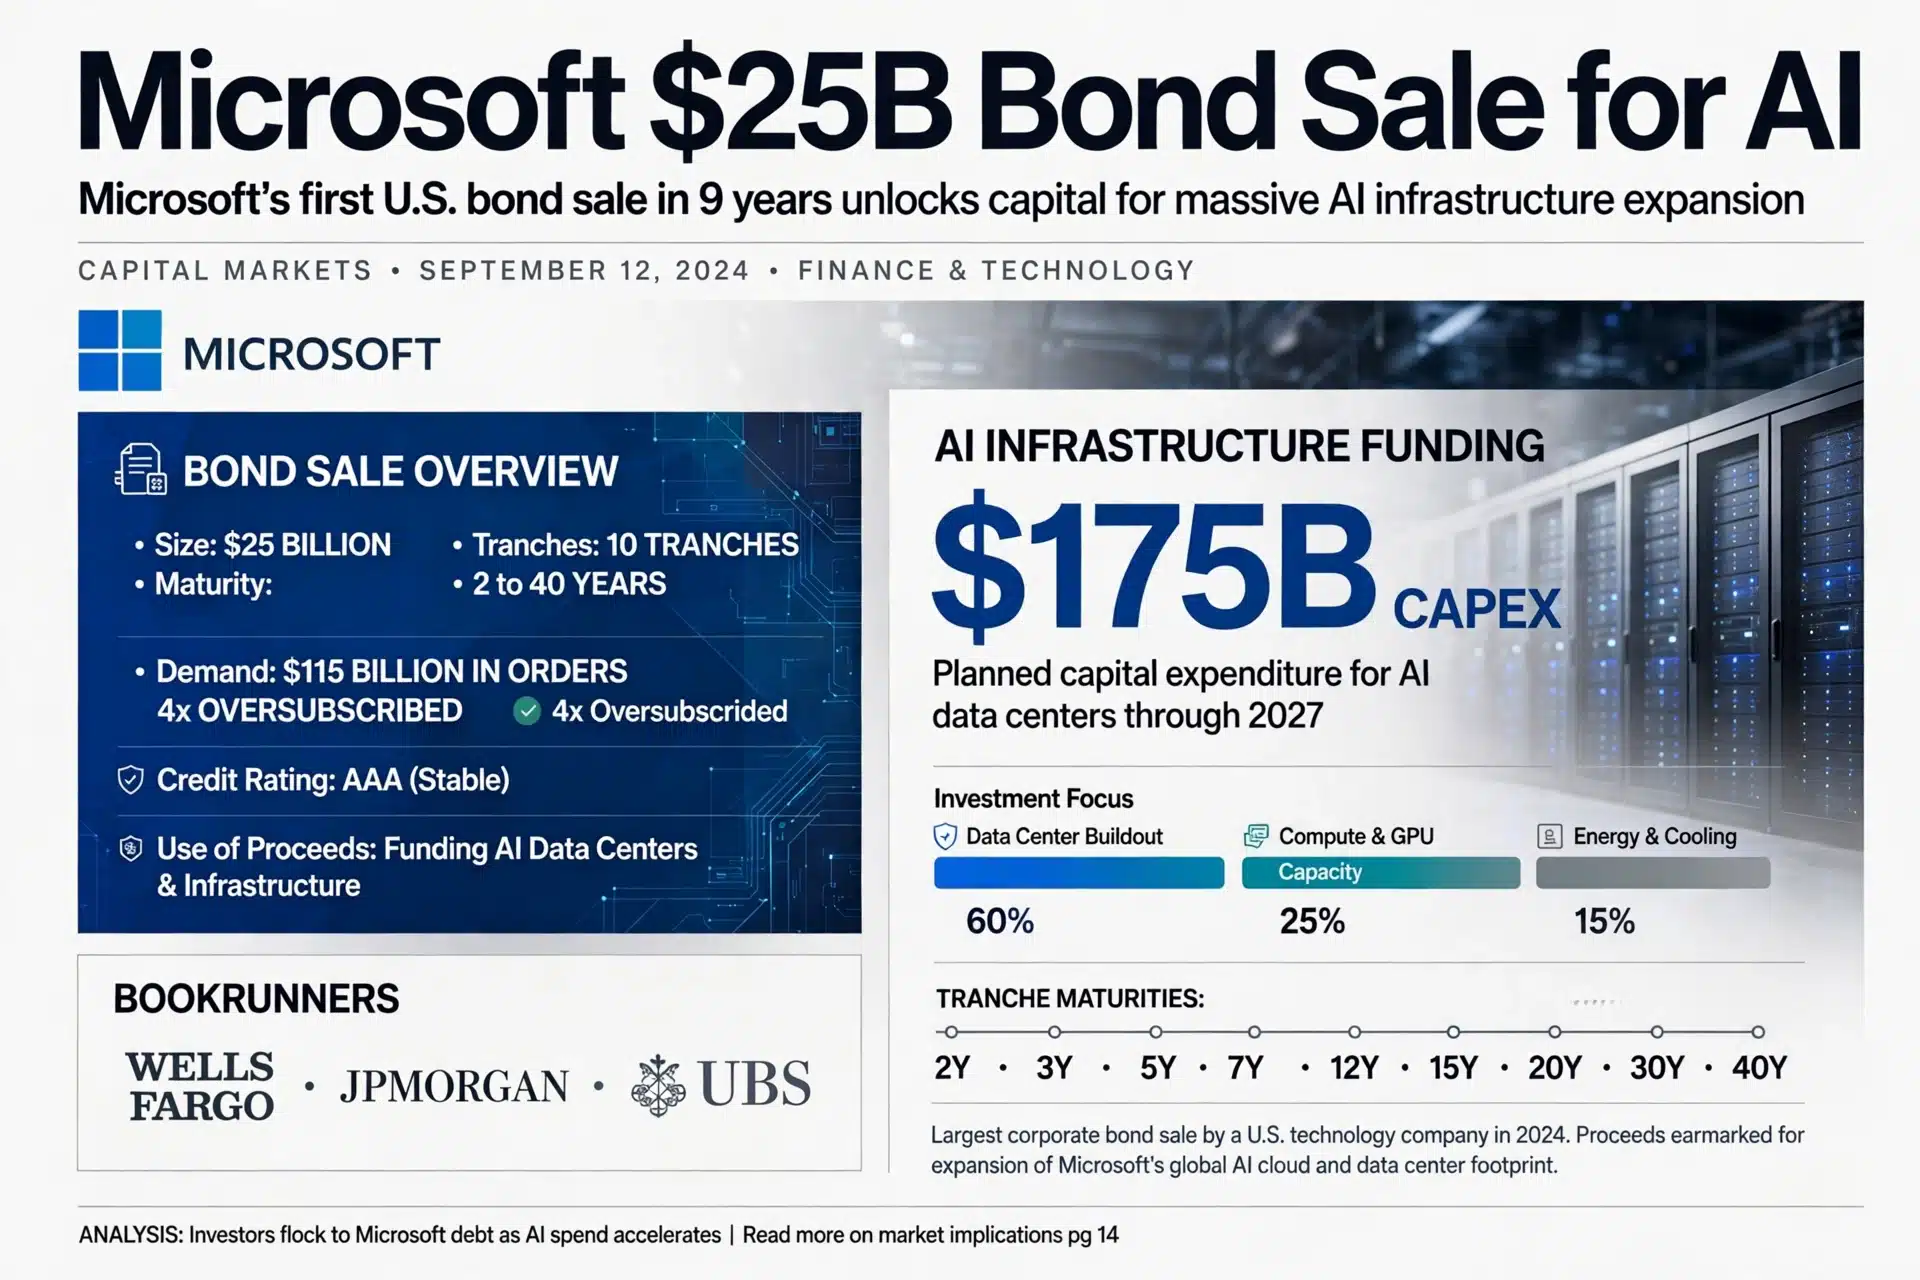
Microsoft launched a $25 billion bond sale on October 29, 2026, its first US investment-grade debt offering in more than nine years, and the Microsoft bond sale is now the clearest test yet of whether credit markets will keep funding the AI buildout. Proceeds feed a capital program headed toward roughly $170 billion in calendar-2026 spending, and the timing raises the bigger question for US readers: when the cash machine behind AI starts borrowing, does everyone else pay more to borrow too?

Key Takeaways:

  • – Microsoft priced a $25 billion senior unsecured bond offering on October 29, 2026, its first US investment-grade sale since a $17 billion deal in 2017.
  • – The deal splits into as many as 10 tranches with maturities from 2 to 40 years, and the longest tranche is due in 2066.
  • – Microsoft is one of only two publicly traded US companies, alongside Johnson & Johnson, rated AAA by both Moody’s and S&P.
  • – One day earlier, Microsoft reported fiscal Q1 2027 revenue of $92.3 billion, up 19 percent, and a record quarterly capital bill.
  • – Hyperscaler and data-center investment-grade issuance has topped $313 billion in 2026 per Bloomberg data, so this deal sets the pricing benchmark.

What Microsoft is actually issuing

The offering is senior unsecured debt, meaning bondholders stand behind deposits and payroll but ahead of shareholders if things go wrong. Per the preliminary prospectus supplement, the structure includes two floating-rate notes priced off Compounded SOFR plus a spread and eight fixed-rate tranches. Maturities run from two years out to forty, with the 2066 note carrying initial price talk of up to 1.35 percentage points over Treasuries. J.P. Morgan, UBS Investment Bank and Wells Fargo Securities are the joint book-running managers, and the deal is expected to close on November 4, 2026.

A forty-year bond from a software company would have been unthinkable a decade ago. It is normal now because lenders are pricing Microsoft against sovereign-adjacent credits, not tech credits. The stated use of proceeds is general corporate purposes, which may include working capital, capital expenditures, repurchases of capital stock, acquisitions, and repayment of existing debt. In practice, every dollar supports an AI infrastructure pipeline: land, power, chips, and the data centers behind Azure’s reported 48 percent revenue growth.

Why AAA status is the whole story

Only two US public companies carry AAA ratings from both Moody’s and S&P, and Microsoft is one of them. That rating is what lets the company borrow at spreads barely above the US government. It also explains why CFO Amy Hood said on the October 28 earnings call that the company had not yet tapped debt markets and was fortunate to have access at its ratings level. She was signaling that the cheapest funding source in the corporate world had been deliberately saved for the moment capex crossed a threshold the balance sheet no longer wanted to carry alone.

The July 2017 comparison matters. Microsoft raised $17 billion then to fund acquisitions and buybacks during a low-rate era. This sale lands after the fastest rate cycle in decades, with Microsoft’s own 10.2 billion returned to shareholders in the quarter and $35.481 billion of total debt already on the books as of September 30. Borrowing while free cash flow is tightening is a different calculation than borrowing while it is expanding, and bond desks will price that difference into every AI-adjacent issuer that follows.

The earnings context behind the sale

The bond timing was not accidental. Microsoft reported fiscal Q1 2027 results on October 28: revenue of $92.3 billion, up 19 percent; net income of $36.6 billion, up 32 percent; Microsoft Cloud revenue of $63.9 billion, up 30 percent; and Azure growth of 48 percent to $33.17 billion. But capex plus finance leases hit $45.2 billion for the quarter, and free cash flow fell 27 percent to $18.63 billion. Commercial remaining performance obligations jumped 73 percent to $677 billion, which is the demand signal, yet the cash statement shows the bill arriving before revenue does.

That gap is precisely why the debt tap opened. Microsoft is targeting about $170 billion in calendar-year capital expenditures, a number that dwarfs what most US states spend on construction yearly. Free cash flow down 27 percent while capital spending climbs means the company is choosing to smooth that curve with debt rather than cut investment, a bet that AI demand keeps compounding faster than the interest bill.

How the Microsoft bond sale reshapes credit markets

Microsoft is not alone. Alphabet sold $25 billion of bonds on August 6, Oracle unveiled a $10 billion raise on October 28, and Amazon and Meta are regular issuers. Bloomberg data puts hyperscaler and data-center investment-grade issuance above $313 billion for 2026 already. When the strongest borrower in the group prices a forty-year note at roughly 1.35 points over Treasuries, that print becomes the reference every weaker credit gets marked against. Utility companies financing data-center power, municipal issuers, and eventually mortgage borrowers all sit downstream of that reference in a demand-heavy market.

There is also a supply effect. Ten tranches hitting a single week absorbs demand from insurance companies and pension funds that would otherwise spread it across other issuers. Dealers reportedly saw heavy interest in the deal, but heavy supply in a week when technology stocks sold off can widen spreads for mid-tier borrowers. For everyday US readers the transmission is indirect but real: corporate borrowing costs feed into the cost of everything from data-center electricity contracts to office construction, which feeds into household bills and hiring.

What happens next

Watch the final pricing when the deal closes on November 4, 2026. If the 2066 tranche prices tighter than the 1.35-point talk, markets are endorsing the AI capex story at the longest end of the curve. If it prices wider, bond investors are demanding a premium for duration risk on a forty-year bet that AI revenue arrives on schedule. Also watch whether Microsoft returns to the market within the fiscal year: a repeat tap so soon after the first would signal that internal cash generation is falling further behind the buildout. Competitor prints from Oracle’s October 28 raise and any Meta or Amazon issuance later in the quarter will show whether Microsoft’s spreads become the sector’s floor.

The honest caveat is that this is not distress borrowing. Microsoft generates some of the largest profits in corporate history and holds an AAA rating with no immediate maturity wall. The sale is strategy, not survival. But strategy at $25 billion scale still moves markets, and October 29 may be remembered as the week the AI boom formally moved from the equity ledger to the credit ledger.

Frequently Asked Questions

Why is Microsoft selling bonds now?

To fund an AI infrastructure buildout targeted at roughly $170 billion in calendar-2026 capital expenditures after free cash flow fell 27 percent in fiscal Q1 2027, per its October 28 earnings report. Debt lets the company spread that spending across years instead of draining cash reserves.

How big is the Microsoft bond sale?

At least $25 billion in senior unsecured notes across up to 10 tranches maturing between 2 and 40 years, with the longest tranche due 2066. It is Microsoft’s first US investment-grade sale since 2017 and is expected to close November 4, 2026.

Will the Microsoft bond sale raise interest rates for consumers?

Not directly, but heavy issuance from AAA-rated tech companies absorbs investor demand and can lift spreads for other corporate borrowers, which flows into business financing costs and eventually consumer prices. The Federal Reserve’s own rate path matters far more for mortgages and car loans.

Sources:

SpaceX Phone Network Plan Sent Carrier Stocks Reeling

SpaceX is negotiating access to at least 80,000 US cell sites as it builds Starlink Mobile into the country’s fourth nationwide phone carrier by 2028, and investors reacted fast: on October 23, 2026, AT&T and T-Mobile shares fell nearly 8 percent after Bloomberg’s report. The carriers’ trade group has already asked the FCC to intervene, with carriers warning the agency’s decisions carry real consequences for consumers. Here is how the SpaceX phone network plan would actually work and what it could mean for US phone bills.

Key Takeaways:

  • – Bloomberg reported October 23 that SpaceX is in talks to access at least 80,000 US cell sites; AT&T and T-Mobile each fell nearly 8 percent that day.
  • – SpaceX President Gwynne Shotwell said on the October 20 earnings call that new spectrum and FCC approvals pave the way for Starlink Mobile, with service targeted for early 2028.
  • – SpaceX bought up to 14 MHz of nationwide 800 MHz spectrum in a deal valued near $8 billion, per the Wall Street Journal.
  • – The FCC cleared SpaceX to deploy up to 15,000 next-generation direct-to-phone satellites on October 6.
  • – The US has had three national carriers since the Sprint deal closed in 2020; regulators had counted on a fourth that never materialized.

Note: this article covers a competitive and regulatory story and is not investment advice.

How the SpaceX phone network would be built

A fourth carrier does not mean building 80,000 towers from scratch. SpaceX plans to pair satellite connections with ground-based radios, and Shotwell told investors the company will basically leverage the real estate from Starlink installs and other towers, per coverage of the earnings call and Bloomberg’s tower talks report. Tower landlords such as Crown Castle are reportedly in the conversation, and Goldman Sachs analysts estimate a tenant pays roughly $50,000 a year per tower, which would put rent for 80,000 sites near $4 billion annually before equipment. In parallel, satellites fill the coverage gaps that towers cannot reach economically, which is how Starlink already texts ordinary phones for partner carriers.

The spectrum stack is the other half. On October 6 the FCC cleared SpaceX to deploy up to 15,000 next-generation satellites built to connect directly to phones. Days later, SpaceX announced the purchase of up to 14 MHz of paired 800 MHz nationwide spectrum from Grain Management in a deal the Wall Street Journal valued around $8 billion; low-band spectrum like this travels far and penetrates buildings, and SpaceX says most phones already support the band. Both deals still need final FCC approval, and SpaceX separately picked up three licenses in the 1,695-1,710 MHz band on October 21.

Why carriers are mobilizing at the FCC

The carriers’ trade association CTIA filed a letter with the FCC following October 20 meetings, warning that the agency’s buildout decisions have real consequences for consumers, and pushing to keep satellites off bands, 2.5 GHz and 3.45 GHz, that carry much of the carriers’ 5G traffic, per the compiled reporting. A separate FCC proposal would open 482 MHz of spectrum to satellite-to-phone use, with a commission vote set for October 29; CTIA wants roughly 290 MHz of that kept terrestrial and wants carriers to keep approval rights over satellite leases of their spectrum.

The economics explain the alarm. The October 23 report produced a second selloff in October, with T-Mobile sinking 5 percent premarket and AT&T and Verizon falling more than 4 percent, per 24/7 Wall St. and Forbes. Musk told analysts he sees a clear path to several hundred billion dollars a year in connectivity revenue, and Starlink Mobile already counts more than 22 million monthly users worldwide through partner carriers.

What it means for your phone bill

The history cuts both ways. In the four-carrier era, the Bureau of Labor Statistics wireless price index dropped 13 percent from December 2009 to September 2015 while overall consumer prices rose, and T-Mobile’s 2010s price disruption is widely credited with forcing the market’s hand. After the market shrank to three in 2020, researchers split on what happened: Finnish firm Rewheel concluded US prices stopped falling or fell more slowly, while economists Thomas Hazlett and Robert Crandall read the data as consistent with consumer gains. Recent history tilts toward pressure: BLS data show wireless prices rose 5.9 percent in August 2026, the largest one-month jump on record, tied partly to AT&T and T-Mobile increases, including AT&T hikes of up to $20 a month on some older plans.

A real fourth competitor arriving in 2028 would be the first structural pricing shock in years. SpaceX has published no pricing or coverage map, so the honest expectation is uncertainty rather than savings on a timetable. But entry matters mechanically: the incoming operator has to win switchers, and the obvious weapon is a cheaper unlimited plan that pools satellite areas where it is genuinely better with terrestrial bandwidth rented from towers.

The fight over the FCC’s October 29 vote

The immediate regulatory marker is the FCC’s October 29 open meeting, where the commission votes on updating its satellite-to-phone rules, including whether to make the additional 482 MHz available and on what power and lease protections. Chairman Brendan Carr has pitched the expansion as a way to eliminate dead zones, while CTIA argues mid-band satellite operations are technically unworkable without degrading 5G networks. A yes vote would open the plan to public comment rather than immediately authorizing service, so the rulemaking fight continues either way.

Carriers also have their own satellite plans, having launched a joint venture to pool spectrum for satellite providers, and T-Mobile still sells a Starlink-based texting service that customers of other carriers can add for $10 a month. The tangle means the ultimate fight is over who controls the customer relationship on carrier airwaves, which is why the lease-rights dispute may matter more than any single satellite approval.

What happens next

Watch the October 29 FCC vote first, then the comment cycle that follows, including any conditions on SpaceX’s pending spectrum approvals. Watch Verizon’s and T-Mobile’s third-quarter earnings responses, which arrived on October 26 and October 28 respectively, for executive guidance on competitive risk. The date on the calendar that matters most is 2028: SpaceX’s own CFO has scoped first-half 2028 for US service, which slipped from a late-2027 target, and every quarter of delay gives incumbents time to lock in customers before the fourth network exists.

The realistic read for consumers: nothing changes on your bill this year, and the first concrete test of the fourth-carrier promise is whether SpaceX closes its tower leases rather than just announcing talks.

Frequently Asked Questions

Why did AT&T and T-Mobile stocks fall on October 23?

Bloomberg reported that SpaceX is in talks to access at least 80,000 US cell sites as part of a Starlink Mobile buildout, which investors read as a credible competitive threat to the three-carrier market; AT&T and T-Mobile each fell nearly 8 percent that day.

SpaceX targets early 2028 for service on its own airwaves, per its October 20 earnings call, with the CFO having scoped first-half 2028 a few weeks earlier after a slip from a late-2027 goal. Regulatory approvals are still pending.

Could a SpaceX phone network lower US phone bills?

A genuine fourth carrier would be the first structural pricing shock since 2020, and parts of the four-carrier era saw the wireless price index fall. But SpaceX has published no pricing, so no savings are promised to date; watch spectrum approvals and tower-leasing progress for real evidence.

Sources:

Supreme Court Lets Immigration Court Closure Ban Stand

The Supreme Court declined on Tuesday, October 27, 2026, to block an agreement between Texas and the Justice Department that eliminated administrative closure, the procedure immigration judges used to temporarily pause deportation cases. In a brief unsigned order with no noted dissents, the court denied a motion by three cities and an immigrant legal-services group, leaving the rule struck down. Here is what the Supreme Court immigration action changes and who is affected.

Key Takeaways:

  • – On October 27, 2026, the Supreme Court refused to pause a consent judgment that vacated the administrative closure rule.
  • – Administrative closure let immigration judges temporarily shelve a case, for example while a person pursued asylum as a crime victim or witness.
  • – A 2024 rule created the tool; Texas sued in June 2026 and won same-day relief in Wichita Falls federal court.
  • – The new agreement commits the government not to adopt a similar rule in the future.
  • – Thousands of pending and closed cases are affected; advocates warn those cases now move back onto active dockets.

This article is informational only and is not legal advice; immigration cases are highly individual, and decisions belong with an experienced immigration attorney.

What administrative closure was and how it worked

Administrative closure was a docket-management tool that the Executive Office for Immigration Review, the Justice Department agency over immigration courts, codified in a 2024 rule. It let an immigration judge remove a case from the active calendar temporarily, not to terminate it, but to set it aside while something outside the court needed time, such as waiting for a US Citizenship and Immigration Services decision on relief an immigration judge could not grant directly. SCOTUSblog’s account of the dispute notes one common use: allowing a crime victim or witness to seek relief from USCIS, a separate agency, before the removal case resumed.

Immigration judges, state court administrators watching criminal dockets, and backlog analysts have all described closure as a pressure valve. Cases paused under it could later be recalled to the active calendar and decided on the merits. The rule’s elimination removes that valve, which affects both judges managing calendars and people whose defense strategies depended on waiting out an application elsewhere.

How Texas got the rule invalidated

The legal path was fast and unusual. In June 2026, Texas filed a federal suit in Wichita Falls, where the case landed before Chief US District Judge Reed O’Connor. Texas argued that EOIR lacked authority to adopt administrative closure because federal law requires an immigration judge to decide removability at the end of a proceeding. Just hours after filing, Texas and the DOJ jointly asked the judge for final judgment striking the rule and barring a similar future rule, and the judge granted it the same day, per SCOTUSblog.

Challengers from outside the case then intervened. In August, Baltimore, New Haven, Columbus, and the Centro Legal de la Raza legal-services group asked to defend the rule on appeal, arguing the district court’s consent judgment was the product of collusion between a state and a federal agency unwilling to defend its own regulation. The district judge denied their motion for lack of standing, the Fifth Circuit declined to block the judgment while the appeal proceeded, and on October 27 the Supreme Court denied their stay motion without comment. Solicitor General D. John Sauer argued that pausing the ruling would improperly transform a dispute over the challengers’ standing into a merits attack on the deal, and Texas said a hold would revive a rule the district court had declared unlawful.

Who is affected now that the Supreme Court immigration order stands

Three groups feel the change first. People with cases currently paused under the rule face the doubt cycle: their closures were a product of the old authority, and the term of the new agreement leaves the judicial path unclear for recalling and calendaring those matters, a question practitioners are racing to answer case by case. Judges have lost a disposition option that, according to its proponents, kept active dockets focused on prime cases. Cities that intervened say their concerns about housing, schools, and emergency budgets when residents face deportation now have no policy lawsuit to carry weight in court.

For immigration practitioners the directions are concrete. Cases on hold should be reviewed for their underlying relief status, because whatever USCIS application justified the pause continues on its own track until USCIS decides it. Meanwhile, defense strategies built on delay while third-party applications mature have lost a channel, moving the pressure to writ filings and USCIS timelines instead of the immigration court calendar.

Why this fight is bigger than one rule

The dispute raises a governance question beyond immigration court: what happens when an agency declines to defend its own regulation and agrees with a challenger to void it? Democracy Forward attorney Joshua Salzman, representing the challengers, warned that if a judgment procured through collusion can stand, any agency could use the playbook of advertising unwillingness to defend a disfavored rule and immediately conceding nationwide relief. The challengers argued that practice undermines the statutory framework that governs how federal agencies adopt and rescind rules. The Supreme Court chose not to address that argument now, and the underlying appeal in the Fifth Circuit continues, so the collusion question is deferred, not decided.

Practical lessons follow for how immigration rules can now be undone. The path that removed administrative closure, friendly litigation, a one-day judgment, and no defense on appeal, is available to any litigant aligned with the agency of the day, which is why immigration advocates describe the arrangement as precedent-setting beyond immigration law.

What happens next

Three threads are live. First, the Fifth Circuit appeal on the challengers’ participation continues regardless of the stay denial, and its outcome will decide whether outside parties can appeal judgments nobody defends. Second, watch how EOIR operational dockets handle previously closed cases, including any guidance to judges on recalling them, which will determine real-world exposure. Third, watch whether the abolished closure authority migrates elsewhere in the system, since USCIS wait times and court calendars both factor how people actually experience removal proceedings between now and the next policy revision.

For affected individuals, the immediate step is practical: keep every USCIS receipt, notice, and filing current while the closure question resolves, because the underlying application is the bridge that connects a paused case to whatever the system does next.

Frequently Asked Questions

What did the Supreme Court decide on October 27, 2026?

The court, in a brief unsigned order with no noted dissents, denied a request to pause the consent judgment that eliminated the administrative closure rule in immigration court, letting the ban stand while the underlying appeal continues.

What is administrative closure in immigration court?

It was a 2024 rule letting immigration judges temporarily remove a case from the active docket, for example while a person pursued USCIS relief such as an asylum claim as a crime victim, though the case itself remained open and could be recalled later.

What happens to cases that were administratively closed?

The rule’s elimination raises calendaring and authority questions that practitioners are working through case by case; keeping underlying USCIS applications and filings current remains the practical priority, and affected people should consult an immigration attorney.

Sources:

Army Opens Camp Atterbury and Muscatatuck for Commercial Drone Testing

The Army announced on Wednesday, October 28, 2026, that it designated Camp Atterbury Joint Maneuver Training Center and the Muscatatuck Training Center in Indiana as premier, permissive sites where commercial companies can test drone and counter-drone technology, acting Army Secretary Adam Telle’s office said. The move enlarges the Army’s Permissive Test Range Expansion Initiative and shortens a path that US drone startups have long called too slow. Here is what the Army drone testing expansion opens up and how companies can get access.

Key Takeaways:

  • – Camp Atterbury and Muscatatuck, both in Indiana, are the newest sites open for commercial drone and counter-drone testing.
  • – Camp Atterbury offers more than 34,000 acres with dedicated restricted airspace up to 40,000 feet; Muscatatuck is a 1,000-acre urban testing site with configurable infrastructure.
  • – Vendors request access through testrange.army.mil, and an ATEC concierge team schedules the test window.
  • – The initiative also includes Camp Grayling (Michigan), Dugway (Utah), West Cibola Range (Arizona), Camp Shelby (Mississippi), and AMTEC (Morocco).
  • – The push began under former Army Secretary Dan Driscoll, who said test access previously took 12 to 18 months.

What changed and why the Army drone testing push exists

The Army labeled the two Indiana installations premier, permissive sites available for commercial testing of drone and counter-drone systems, per the Army’s announcement and DefenseScoop’s October 28 report. The Permissive Test Range Expansion Initiative aims to fix a complaint nearly every defense-tech founder repeats: the gap between having working hardware and getting a government range to validate it. Dan Driscoll, before resigning as Army secretary, framed the problem bluntly. Sometimes it can take 12 to 18 months for a company that wants to test the thing that can make a soldier’s life better, he said in August; that, in his view, was not sufficient. The initiative’s answer is standing access: ready-to-book ranges with the safety infrastructure already cleared for uncrewed flights.

Timing matters for budget reasons too. Congress and the Pentagon have poured tens of billions into drones and counter-drone since the conflicts in Europe and the Middle East demonstrated that cheap massed drones and the tools to stop them now decide outcomes. Procurement pipelines cannot buy technology that has not been validated, and test access is the first turn of that valve.

What each site offers drone and counter-drone companies

The two Indiana sites complement each other deliberately. Camp Atterbury provides more than 34,000 acres of secure space with a dedicated restricted airspace corridor extending up to 40,000 feet, per the Army release, which is room for long-range flights and high-altitude sensor work without negotiating each flight with air traffic control. The Muscatatuck Training Center is a different instrument: a 1,000-acre developmental testing site with configurable urban infrastructure, allowing testing of drone and counter-drone navigation and tracking systems inside complex physical structures, per the release. That is where a drone that navigates sewers and stairwells gets proven, and where counter-drone tools get exercised against real urban clutter.

For companies, the unlock is scheduling rather than construction. Once a request is submitted through testrange.army.mil, a dedicated Army Test and Evaluation Command concierge team works with the vendor and the Indiana National Guard to coordinate testing schedules and requirements, per the release. The Army cautions that a submitted request does not guarantee the desired location or timeline because of capacity limits, but the concierge model means a US startup can plan a test campaign in weeks and months rather than waiting the better part of two years.

Why a US drone industry wants this now

The counter-drone market is young and competitive, filled with jamming, radar, gun- and net-based interceptors, and AI-enabled detection systems, and the Army has already run separate large procurement pushes to field internationally proven systems. Homegrown mid-tier companies say the bottleneck is validation: without credible military test records, they cannot win funding, insurance credibility, or programs of record. Making Army ranges commercially bookable converts that private hardware surplus into something the acquisition system can evaluate.

It also builds an industrial base ahead of potential demand. The Army’s test-range map now stretches from the Great Lakes to Utah and Arizona to Mississippi, with the Morocco-based AMTEC offering an overseas venue; locating premier sites in the Indiana National Guard’s footprint also puts testing near a Midwest manufacturing corridor that drone and sensor companies can serve by road. Expect local economies around these ranges to court drone suppliers the way Air Force towns court flight-test businesses.

How the initiative fits Pentagon acquisition strategy

The test-range push is one leg of a broader shift in how the military sources aerial capability, alongside multi-year production deals, streamlined procurement pathways for software-defined hardware, and direct awards to nontraditional vendors. The through-line is speed: officials concluded that the legacy test-and-evaluation calendar, built for billion-dollar missile programs, kills small-dollar drone innovation, so they are building a parallel path where commercial hardware can prove itself on government ranges quickly and be bought in quantity if it works.

There are standing caveats. Capacity limits are real, and a surge of applicants could still stretch scheduling; the concierge team manages expectations but does not promise dates. Security and export-control rules still apply to foreign vendors and to anything with classified components, and permissive does not mean unregulated. Companies should bring their own data-collection plans and legal clarity on what data the government will see.

What happens next

Watch three things through 2027. First, the first round of commercially tested systems graduating into procurement vehicles, something US drone founders have described as the missing proof point for private investment. Second, whether the initiative adds more sites, since its existing footprint spans six states plus Morocco and each new location multiplies the scheduling capacity for the industry. Third, Congress: sustained test access depends on continued funding for range operations and for the ATEC concierge function, and budget fights in 2027 will test whether the initiative becomes permanent.

For US drone and counter-UAS companies, the action item is concrete: register at testrange.army.mil, submit a scoping request, and start the conversation with the concierge team early, because as more vendors discover the pipeline, slots will tighten.

Frequently Asked Questions

Which sites are open for commercial drone testing?

The initiative includes Camp Atterbury and Muscatatuck in Indiana plus Camp Grayling (Michigan), Dugway Proving Ground (Utah), the West Cibola Range (Arizona), Camp Shelby (Mississippi), and AMTEC in Morocco, with the Indiana additions designated October 28, 2026.

How does a company get an Army test slot?

Submit a request through testrange.army.mil; the Army Test and Evaluation Command concierge team then works with the vendor and local Guard units to schedule testing, within capacity limits.

What can be tested at the new Indiana sites?

Drone and counter-drone systems of many kinds: Camp Atterbury’s 34,000 acres and 40,000-foot restricted airspace suit long-range flight and sensor testing, while Muscatatuck’s 1,000-acre configurable urban environment is built for navigation, tracking, and counter-drone work in complex structures.

Sources:

Lilly Retatrutide Trial Outperforms Ozempic in Diabetes Study

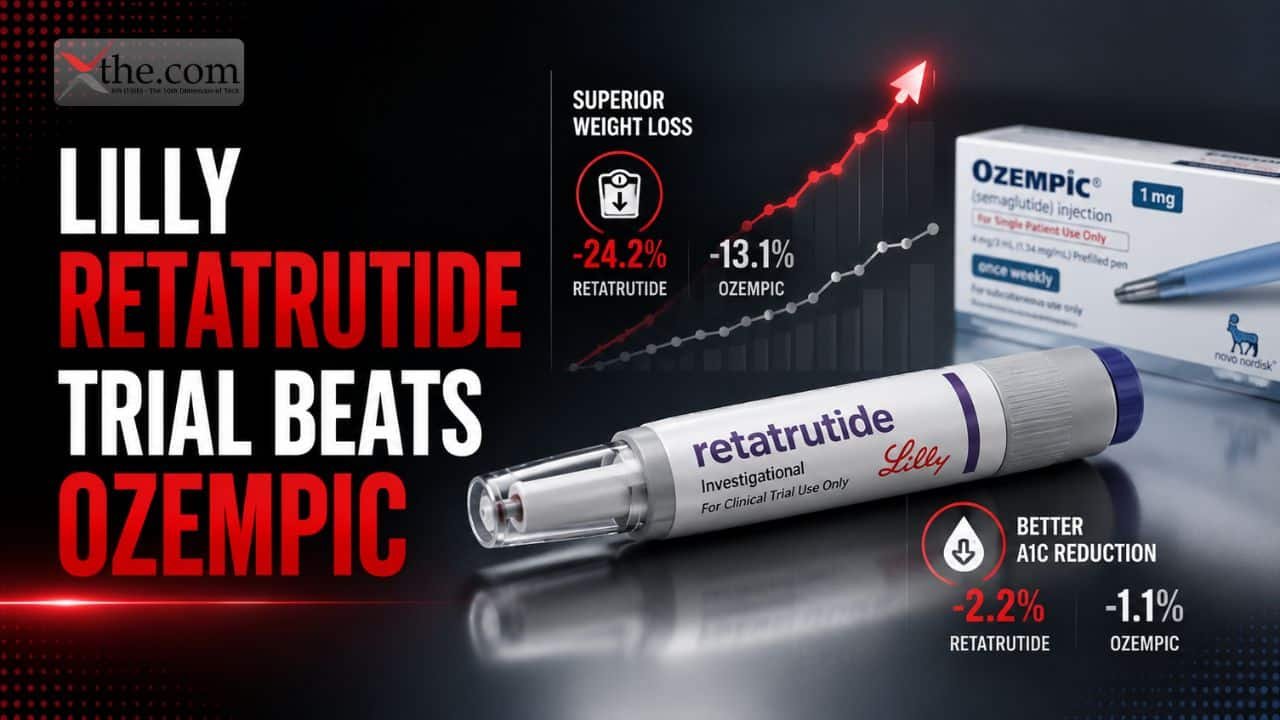
Eli Lilly said on October 28, 2026 that its once-weekly experimental drug retatrutide beat Ozempic head-to-head in a late-stage trial in adults with type 2 diabetes, delivering about double the A1C reduction and more than twice the weight loss of the Novo Nordisk drug at its highest approved dose. Retatrutide is still investigational and not FDA-approved, but the results pressure Lilly’s biggest rival in the US weight-loss and diabetes market. Here are the numbers and what they mean.

Key Takeaways:

  • – Over 80 weeks, retatrutide lowered A1C by an average of 2.2 points versus 1.8 points for Ozempic at its highest approved dose.
  • – Participants lost an average of 44.3 or 47.4 pounds on retatrutide, depending on dose, versus 20.9 pounds on Ozempic.
  • – Retatrutide targets three hormone receptors (GLP-1, GIP, and glucagon); approved incretin drugs target one or two.
  • – The drug remains experimental; Lilly will present more detailed results at a later scientific meeting.
  • – Head-to-head wins against semaglutide strengthen Lilly’s position in the US GLP-1 market.

These are topline results from one trial. This article is informational only and is not medical advice; treatment decisions belong with a clinician.

What the Lilly retatrutide trial measured

The trial enrolled adults with type 2 diabetes and compared retatrutide against Ozempic, the semaglutide injection Novo Nordisk sells for diabetes. The headline matchup matters because Ozempic is the incumbent that established injectable incretin therapy as a mass-market treatment, and beating it head-to-head is the standard a competitor must clear. Over 80 weeks, the once-weekly retatrutide injections lowered average A1C, the three-month measure of blood sugar control, by 2.2 percentage points against 1.8 for Ozempic, and produced weight loss of 44.3 to 47.4 pounds across the retatrutide doses studied versus 20.9 pounds for Ozempic, per Lilly’s announcement as reported by Reuters and MedCity News.

Access, data, and dates all matter, and the topline release leaves those questions for the full readout. Retatrutide, if all this is confirmed, would be the strongest signal yet that triple-agonist therapy is a step change in what metabolic treatment can deliver, and the trial numbers give Lilly the strongest conversation-starter it could ask for with both regulators and payers. Between headline averages and a prescription, however, sit the full readout, safety detail, an approval filing, a label, and an insurer decision.

Why a triple agonist matters

Retatrutide is a single molecule that activates three hormone receptors the body already uses to regulate appetite and blood sugar: GLP-1, GIP, and glucagon. Approved incretin drugs activate one or two. Adding the glucagon receptor is the differentiator researchers have watched for years, because glucagon signaling influences energy expenditure and liver fat in ways GLP-1 and GIP do not. The phase 3 numbers are the strongest signal yet that hitting all three translates into greater weight loss without losing blood-sugar control.

The competitive math is straightforward. Lilly already sells tirzepatide, a dual-receptor drug marketed for diabetes and obesity, and it dominates the category against Novo Nordisk’s semaglutide franchise. Retatrutide would extend the ladder one more rung, and a head-to-head win over the legacy standard in a diabetes trial gives Lilly data for both indications at once. Novo’s response path, next-generation encircles or oral formulations, remains to be seen, but today’s result deepens the lead Lilly has built since tirzepatide’s debut.

What it means for patients with type 2 diabetes

For people with type 2 diabetes in the US, the result is promising but not yet actionable. Retatrutide is not approved anywhere, so there is no prescription, no label, and no insurer coverage to discuss. Patients who ask their clinician about it this week will be told what the data warn: the drug worked in a 80-week trial, but the full safety picture, tolerability, and subgroup results are pending until Lilly presents complete findings at a scientific meeting.

What is actionable is the trajectory. If full results hold, approval filings for retatrutide would build on the same regulatory framework that brought tirzepatide to market, and a diabetes approval with weight-loss data would set up a labeling fight over the obesity indication. Patients currently doing well on established therapy have no reason to switch on hype; the clinical meaning of a head-to-edge advantage in averages depends on individual tolerance, cost, access, and goals that a prescriber weighs case by case.

The access and pricing angle

The economics of this market are defined by list pricing above a thousand dollars a month and employer and insurer hesitance over broad coverage, not by clinical differentiation alone. A more effective drug intensifies the cost question rather than settling it, because payers will face demand for the newest agent while already absorbing price pressure from the current generation. Expect the access conversation to dominate the rollout debate in 2027 and beyond, whoever holds the approval.

Competition helps prices at the margin, but head-to-head winners in this category have not sparked price wars to date because supply, not demand, has been the binding constraint. Retatrutide’s manufacturing ramp will therefore shape real-world access as much as the phase 3 result did, and Lilly’s capacity commitments will be the thing to watch once approval filings arrive.

What happens next

Watch for four datelines. First, Lilly’s full presentation of these diabetes results at a scientific meeting, which will fill in the safety and tolerability picture that the topline release omits. Second, retatrutide filings expected to draw on the existing incretin regulatory pathway, with the timing dependent on these full results. Third, the obesity-standalone program, where separate trials fiber into an approval case for the indication that has the largest US market. Fourth, any label or coverage decisions from major payers once an approval hands regulators and insurers the real-world price discussion.

Between now and then, the practical takeaway is patience. Triple-agonist data this strong suggests the next generation of metabolic therapy will be meaningfully better than today’s options, but the transition from trial numbers to a prescribable, affordable drug takes years, and patients should not stop or change existing therapy based on topline headlines.

Frequently Asked Questions

What did the retatrutide trial show?

In an 80-week phase 3 trial in adults with type 2 diabetes, once-weekly retatrutide lowered A1C by an average of 2.2 points versus 1.8 for Ozempic at its highest approved dose, and produced weight loss of 44.3 to 47.4 pounds across doses versus 20.9 pounds, per Lilly’s October 28, 2026 announcement.

When will retatrutide be available?

It is not approved yet. Lilly plans to present full results later, and approval filings would follow. Availability, coverage, and pricing depend on regulators and insurers after any approval.

Is retatrutide a triple agonist?

Yes. It activates GLP-1, GIP, and glucagon receptors, three hormone pathways involved in appetite and blood sugar regulation, while approved incretin drugs target one or two of them.

Sources:

Samsung Galaxy Buds On Hit the US in Early November at $229

Samsung will launch its first clip-on, open-ear wireless earbuds in the United States in early November for $229, per an October 28, 2026 announcement covered by Engadget. The Galaxy Buds On, which debuted in South Korea on October 27 at KRW 299,000 (roughly $220), skip the ear canal entirely, clipping onto the outer ear so you can hear your music and the world around you at the same time. Here is what the Samsung Galaxy Buds open-ear design changes for everyday listening and whether the $229 price makes sense.

Key Takeaways:

  • – Galaxy Buds On reach the US in early November 2026 at $229, per Engadget’s October 28 report.
  • – They are Samsung’s first clip-on, open-ear earbuds, leaving the ear canal open rather than sealing it.
  • – Battery life is up to 9.5 hours per charge, and controls include calls and head gestures.
  • – The earbuds first launched in South Korea on October 27, 2026.
  • – Open-ear designs suit runners, cyclists, office workers, and anyone who must stay aware of their surroundings.

What open-ear listening changes in practice

Most wireless earbuds work by inserting into or sealing around the ear canal. That seal is why premium earbuds sound full and why active noise cancellation works, but it also blocks the sounds you may actually need: traffic, announcements, a coworker, or your own footsteps. Open-ear earbuds flip the tradeoff. They sit outside the canal, usually hooked over or clipped onto the outer ear, and play sound into the open ear. You sacrifice some bass and isolation, and you gain situational awareness and comfort for long wear.

Samsung’s specific twist is the clip-on form. This shape is already popularized by other brands in the open-ear clip style that smaller brands popularized, and it has a real practical benefit: the bud stays put through head movement without pressing against the ear canal, which many users find more comfortable for all-day wear. Battery and controls round out the basics. At up to 9.5 hours of playback per charge, the Buds On beat the per-charge figures of most sealed premium earbuds, and Samsung says the buds support call handling and head-gesture controls, for example nodding to accept a call.

Who the $229 price makes sense for

Fit comes first. If you have tried in-ear earbuds and always found them painful or loosening, an open-ear clip-on design is a legitimate solution rather than a compromise. Runners and cyclists also have a safety argument: many states regulate riding with both ears sealed, and hearing traffic is a simple matter of personal risk. Office workers who need to catch when someone approaches their desk are an under-recognized audience for open-ear buds.

At $229, Samsung is pricing at the premium end of the category, above most basic open-ear options. What you are paying for is ecosystem fit: the Buds On work with Samsung’s app ecosystem, and buyers already invested in Galaxy devices, especially Galaxy Watch users who commonly use their phone less, will find pairing, switching, and settings familiar. If your priorities are bass depth and noise cancellation instead, sealed premium earbuds remain the better category at this price. If you want stable comfort and environmental awareness, the Buds On now compete as a fresh first-party Samsung option.

How Galaxy Buds On fit the earbud market

The open-ear segment is growing fast because comfort and situational awareness solve different problems than the flagship sealed-earbuds market. Samsung entering with a first-party option signals that the design has moved from independent-brand niche to mainstream, much like Samsung validating a new form factor historically pulled accessory makers into the fold ecosystem-wide. Competitors already sell cube-style clip-on buds at lower prices, so Samsung’s case rests on quality control, ecosystem integration, and service support that first-party hardware offers.

There is also a strategic layer. Samsung’s wearable lineup is designed to keep users inside the Galaxy ecosystem alongside Galaxy Watches and Galaxy phones. Earbuds are the most worn device on the body, and a second, more comfortable form factor gives Samsung another daily habit through which to sell subscriptions, health features, and assistant services over time.

What to check before buying

Three practical checks should anchor any purchase decision. First, fit: clip-on buds are one-size, unlike sealed buds with interchangeable tips, so try them in store if possible; a clip that is too loose is the most common complaint with this design. Second, sealed-earbud users should expect weaker bass and a more open sound, which some describe as less intimate. Third, battery math: 9.5 hours per charge compares favorably, but open-ear buds leak more sound at high volume because nothing seals the canal, and cranking levels to compensate cuts real battery life.

Shoppers can also compare against the feature set of their existing buds. If your current sealed pair already delivers noise cancellation and your commute is the main use case, the Buds On are a second category purchase for workouts and office days, not a replacement. If constant ear fatigue or environmental awareness is your pain point, this launch finally gives Samsung owners a native option instead of crossing to accessory brands.

What happens next

Watch for three things through November. First, the exact US release date and any launch-bundle offers, since Samsung typically sweetens day-one purchases with trade-in credits or accessory discounts. Second, independent reviews of the mic quality on calls, which has historically been the weak spot of open-ear designs because the microphone sits away from the canal. Third, price movement during Black Friday week: at $229 launch, a first meaningful discount to around $199 would be typical holiday behavior, and waiting for that window is a reasonable strategy if your need is not urgent.

The bigger picture is that earbud design is diversifying after a decade of in-ear monoculture. Samsung shipping a clip-on open-ear model at the premium tier makes that diversity a mainstream reality for US buyers, and expect every major brand to answer within the next year.

Frequently Asked Questions

When can I buy Galaxy Buds On in the US?

Samsung says the earbuds arrive in the US in early November 2026, per Engadget’s October 28 report, priced at $229. The buds first launched in South Korea on October 27, 2026.

What is different about clip-on open-ear earbuds?

They do not enter the ear canal. A clip holds the bud on your outer ear, so you hear your audio and surrounding sounds at the same time. Comfort and situational awareness improve; bass and noise isolation decrease compared with sealed earbuds.

How long does the battery last?

Up to 9.5 hours of playback per charge according to Samsung. Expect less at high volumes, and check the carrying-case charging spec for total endurance if you use them all day.

Sources:

DOJ Opens Nvidia Hugging Face Inquiry: What It Means for AI Competition

The Justice Department is asking whether Nvidia’s proposed $12.93 billion purchase of Hugging Face would give the chip giant too much control over how AI models reach developers, according to an exclusive Reuters report published October 28, 2026. The inquiry does not mean the deal is dead, but it puts the most important open-source AI platform on the antitrust map. Here is what the Nvidia Hugging Face review covers, why regulators care about model distribution, and what US developers and businesses should watch next.

Key Takeaways:

  • – The DOJ is examining how Nvidia’s $12.93 billion Hugging Face deal would affect competition, focusing on control of a key route through which AI models reach developers.
  • – Nvidia agreed to buy Hugging Face in early September 2026; the deal has not been formally blocked or approved.
  • – The inquiry is part of a broader review of Nvidia’s acquisitions, investments, and sales practices.
  • – An inquiry is not an accusation of wrongdoing, and Reuters notes it may not lead to legal action.
  • – Hugging Face hosts and distributes hundreds of thousands of open AI models used by US startups, universities, and Fortune 500 teams.

Why the Nvidia Hugging Face deal drew the DOJ’s attention

Hugging Face is not a chip company. It is the de facto public library of open AI models, datasets, and tools, where developers download everything from language models to image generators. That makes it infrastructure, and infrastructure is where antitrust enforcers pay the closest attention. The DOJ’s core question, as reported by Reuters and picked up by Yahoo Finance and AI Weekly, is whether one company could own both the dominant hardware for training AI and a central distribution channel for the models that run on it.

The inquiry fits a pattern. Nvidia’s chips dominate the data centers where most serious AI gets built, and its deals with cloud providers and model developers are already under regulatory scrutiny. Adding Hugging Face would extend that footprint from the supply side of AI, the hardware, to the demand side, the place where most of the world’s developers actually get their models. Regulators have historically treated that kind of vertical stacking, where a supplier owns a marketplace, as a competition risk because the owner can favor its own products, charge rivals more, or quietly change terms.

What the $12.93 billion acquisition actually buys

Nvidia announced in early September 2026 that it had agreed to acquire Hugging Face for $12.93 billion, per Reuters and reports that tracked the announcement. The price reflects more than revenue: it buys community goodwill, a standard model packaging format, and the default destination for teams publishing open models. For Nvidia, the strategic pitch is easy to see. If the company that makes the GPUs also owns the platform where models are shared, it can optimize every step of the pipeline and steer more workloads onto its own hardware.

For the developer community, the concerns are more concrete. Open projects thrive on neutrality. If a hardware vendor owns the library, questions follow quickly. Would models that run best on competing hardware get equal treatment in search results and featured placements? Would licensing terms shift to favor the owner’s ecosystem? Would the platform’s traditional openness, which let academics and startups publish freely, survive a corporate integration? The DOJ’s inquiry suggests those questions are not theoretical.

What the inquiry can and cannot do

An antitrust inquiry is a fact-finding step, not a courtroom verdict. Reuters specifically notes that the examination does not establish wrongdoing and may not lead to legal action. The realistic outcomes are several. The DOJ could close the inquiry with no action if it finds the competition concerns overstated. It could push for remedies, such as commitments that Hugging Face stays open and neutral, before clearing the deal. Or it could file suit to block the acquisition, which would move the fight to federal court and likely add a year or more of litigation.

Timing matters here too. The deal has not yet closed, so the companies still have room to negotiate conditions with regulators before finalization. Deals in concentrated tech markets routinely get restructured under this kind of pressure, either through divestitures, firewalls between business units, or public commitments to neutrality. The practical signal for the market is that the acquisition will not sail through quietly.

What US developers and businesses should watch

If your team relies on Hugging Face, the immediate takeaway is not to panic and migrate, but to reduce single-point-of-failure risk. Mirroring the models you depend on, pinning specific versions, and keeping a second distribution source in your deployment pipeline are cheap insurance regardless of how the deal ends. Startups that build products on top of the platform should watch for any change in terms of service or in how the platform prices compute, since those are the levers an owner could realistically pull.

The broader signal for the AI industry is that regulators are no longer focused only on chips and training runs. Distribution is now treated as a market. Whoever controls where models get published, discovered, and downloaded controls a chokepoint that can shape the entire ecosystem, and the DOJ appears prepared to police it the same way it polices app stores and cloud marketplaces.

What happens next

Expect three markers over the coming months. First, any formal second-step review or deeper investigation would appear in regulatory filings and reporting, which would extend the timeline and raise the odds of conditions on the deal. Second, watch Hugging Face’s own communications: platform owners under scrutiny often publish openness commitments and governance changes to preempt criticism. Third, watch Nvidia’s deal-completion timeline. If the companies push closing past announced targets or quietly amend the agreement, that is the clearest evidence that regulators extracted changes.

The stakes go beyond one deal. How regulators treat a hardware-and-platform combination like Nvidia and Hugging Face will set the template for the next generation of AI acquisitions, where model marketplaces, agent toolkits, and compute marketplaces are the prize. For US startups, the best case is a clear set of neutrality rules that keep the open ecosystem genuinely open. The worst case is a long legal fight that freezes investment in the platform while both sides litigate.

Frequently Asked Questions

Why is the DOJ investigating the Nvidia Hugging Face deal?

Reuters reported on October 28, 2026 that the Justice Department is examining how the proposed $12.93 billion acquisition would affect AI competition, including whether owning Hugging Face would give Nvidia control over an important route through which AI models reach developers.

Does the inquiry mean the deal will be blocked?

No. An inquiry is not a determination of wrongdoing, and it may not lead to legal action. Possible outcomes range from clearance to negotiated conditions to a court challenge to block the deal.

What should developers do while the review continues?

Teams that depend on Hugging Face can lower risk by mirroring the models they use, pinning versions, and keeping a backup distribution path. Watch for any changes in platform terms, search ranking of models, or compute pricing as the review progresses.

Sources: