New York, New York | July 10, 2026 

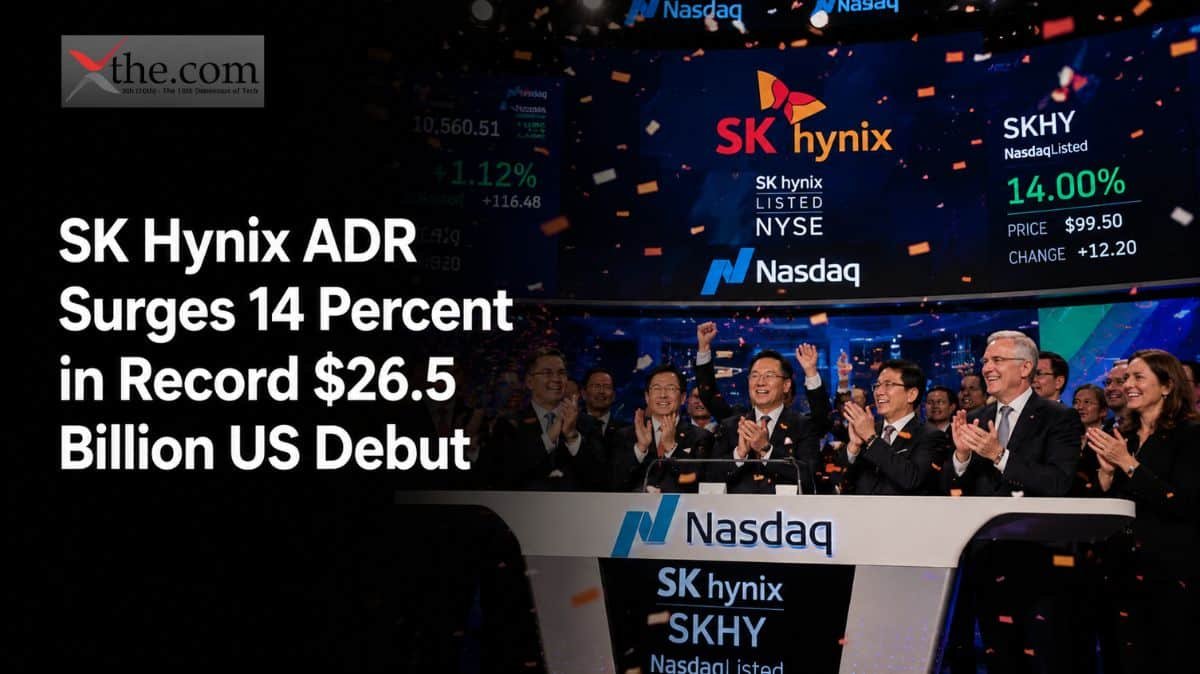
Just last month, most American retail investors couldn’t buy shares of this South Korean chipmaker. Now, SK Hynix has become one of the biggest new listings Wall Street has ever hosted. The SK Hynix ADR debut opened at $170, up 14% from the offering price. By midday, the numbers were remarkable: only one other company has ever raised more money from US investors in a single debut. 

SK Hynix is the world’s second-largest memory chipmaker and is widely seen as the top supplier of high-bandwidth memory chips used in nearly every advanced AI accelerator this year. Trading started Friday morning with a temporary symbol before switching to its permanent ticker. The occasion was commemorated with an opening bell ceremony at the Nasdaq MarketSite in Times Square, attended by SK Group Chairman Chey Tae-won, Executive Vice Chairman Chey Jae-won, and SK Hynix CEO Kwak Noh-Jung. After three decades of trading mainly on the Korea Exchange, SKHY’s Nasdaq debut on July 10 is a turning point for both the company and for how global markets value firms building AI infrastructure. 

A $26.5 Billion Statement 

The numbers highlight the scale of this listing. SK Hynix raised $26.5 billion by listing, pricing 177.9 million ADRs at $149 each, and demand was more than seven times the number of shares available, according to people familiar with the process. About $5 billion in ADRs went to key investors such as Baillie Gifford, Coatue Management, and Situational Awareness Partners, ensuring a strong base of long-term holders before public trading began. 

The SK Hynix ADR $149 price was itself the product of weeks of roadshow meetings in the US, Europe, and Asia, where executives argued that the company’s real earnings potential was held back by a structural discount. Investors seemed to agree. When trading opened at $170, it confirmed what bankers had been telling clients: the deal was priced to allow for a strong first-day gain, and the market took advantage. 

Looking at the bigger picture, only SpaceX’s offering last month raised more money in a single US share sale. SK Hynix’s deal topped Saudi Aramco’s $25.6 billion IPO from 2019, which had been the standard for foreign companies listing in the US for six years. This makes this the SK Hynix largest US foreign listing on record, a milestone likely to be studied in cross-border finance for years. 

Why Wall Street Showed Up 

Beyond the ceremony and pricing details, the main point is clear. SK Hynix holds about 60% of the global market for high-bandwidth memory, the chips that deliver data quickly to graphics processors from Nvidia and AMD. Every Nvidia H100 and Blackwell GPU shipped this year uses memory stacks made by SK Hynix or its main rival, Samsung. Apple is also a customer. This is not a niche product; it is the key component in the generative AI supply chain, and SK Hynix is at its core. 

This strong position explains why the HBM memory AI chip listing attracted so much interest from big investors. Data center operators are still expanding, and the memory needed for new AI workloads is growing even faster than the logic chips. CFO Kim Woo-Hyun has told investors that computing is moving toward agentic systems, software programs that handle multi-step tasks rather than single prompts. This change increases memory needs, not just maintaining them. If this trend continues, demand for SK Hynix’s main product will keep rising. 

SK Hynix’s shares on the Korea Exchange already show this optimism. They have risen more than 280% in the past year, even after dropping about 25% from a late June high. This jump pushed SK Hynix’s market value above $1 trillion, making it South Korea’s most valuable listed company, ahead of Samsung Electronics. Still, SK Hynix trades at a lower valuation than Micron Technology, its closest US-listed competitor. Analysts call this the “Korea discount,” and today’s Nasdaq listing aims to close that gap. 

The Mechanics Behind the Headline Number 

For those new to depositary structures, the SKHY 14 percent first-day gain deserves a bit of unpacking. An American Depositary Receipt is not a new type of stock. It is a certificate from a US bank that represents shares held in trust on the company’s home exchange. Each SK Hynix ADR equals one-tenth of a Korean common share. This setup makes the price more available for both retail and institutional US investors, so they don’t have to deal with won pricing or Seoul trading hours. 

This simple structure is what analysts say has finally removed the barrier that kept SK Hynix’s valuation low for years. Before Friday, American fund managers needed a Korean brokerage, currency hedging, and patience for overnight settlements to invest directly. Now, they can buy SK Hynix with a simple ticker search in any US brokerage account. The stock could also be added to indexes such as the Nasdaq-100 and the Philadelphia Semiconductor Index, which would require passive funds to buy shares regardless of short-term price movements. 

Media coverage has summed up the event simply: “SK Hynix ADR surges 14 percent on Nasdaq debut July 10, 2026” underscores both the result and the date that will be remembered in market history. Another phrase circulating among traders on Friday — “SKHY first day trading largest US foreign listing HBM AI chips” — explains why this deal was important beyond its size: it combined a record capital raise with the most sought-after product in global tech. 

Not every company in the AI supply chain had the same experience on Friday. TSMC’s June sales report, usually an important indicator for chip demand, was delayed to July 13 because Typhoon Bavi caused a production shutdown on July 10. This shows that even the biggest chipmakers can be affected by events beyond their control. 

What Comes Next 

SK Hynix will report its second-quarter earnings on July 29, less than three weeks after its debut. This short window gives the market little time to adjust to the new listing. Revenue is expected to rise sharply from the previous quarter, primarily driven by HBM shipments for AI infrastructure. If the results confirm the growth investors paid a premium for, the argument for closing the valuation gap with Micron becomes stronger. But if market mood turns negative before then, the stock that jumped 14% on its first day could lose some of those gains. 

No matter what happens next, Friday’s session did more than just move the share price. It gave US investors direct, dollar-based access to the company that makes the memory chips now central to the AI boom. Only one other foreign company has ever matched this scale on a US exchange.

Source: SK Hynix Rises Nearly 13% in Debut on Wall Street as Demand for Memory Chips Soars Amid AI Frenzy 
Houston, Texas | July 9, 2026 

NASA Recruits Volunteers for Yearlong Moon and Mars Simulation as Mars Mission Planning Accelerates 

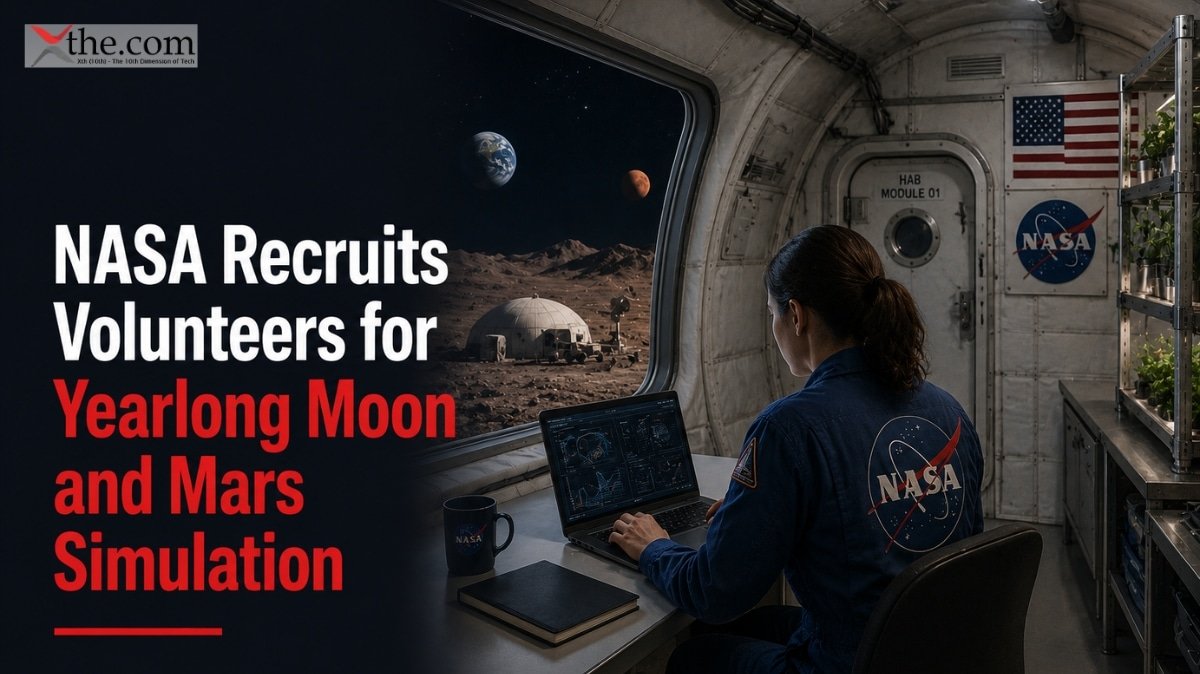
A trip to Mars will not fail because of rocket engines alone. It could fail because four people living together for months struggle with isolation, disrupted sleep, limited privacy, or delayed communication with Earth. That is why the NASA Moon Mars simulation 2026 has become one of the agency’s most important research efforts. Through the NASA volunteer yearlong simulation, the agency is asking ordinary people with extraordinary devotion to spend an entire year inside a carefully designed habitat, helping scientists answer questions that no laboratory experiment can completely replicate. 

The NASA space habitat experiment is another important step in preparing astronauts for deep-space missions, where there won’t be access to medical care, supply drops, or emergency evacuation. 

NASA Moon Mars simulation 2026 prepares for humanity’s next giant leap 

NASA’s new recruitment effort focuses on the Crew Health and Performance Exploration Analog, or CHAPEA. In the NASA CHAPEA Moon Mars simulation 2026, chosen volunteers will live for about a year inside a tightly controlled habitat at Johnson Space Center in Houston, Texas. 

Unlike regular astronaut training, these participants won’t go to space. Instead, they’ll live in conditions that are much like those on the Moon or Mars. Researchers will limit communication, resources, personal space, and flexibility to see how crews handle the special challenges of deep-space missions. 

This Mars mission preparation simulation lets scientists watch how people behave in ways that short experiments can’t show. Every meal, repair, experiment, emergency drill, and interaction gives important data for ensuing missions. 

Why NASA needs volunteers instead of astronauts 

Professional astronauts already train for long periods and spend months on the International Space Station. But NASA also wants to see how people from different careers handle long-term isolation. 

The NASA volunteer yearlong simulation helps NASA better understand how people outside the astronaut group perform. Engineers, scientists, healthcare workers, military veterans, and others may use different ways to cope and make decisions. 

Researchers track many factors during the mission, such as thinking skills, health, nutrition, stress, sleep, teamwork, leadership, and emotional strength. These results help guide how NASA picks astronauts, designs spacecraft, sets medical rules, and runs missions in the future. 

Inside the NASA space habitat experiment 

Life in the habitat is designed to be challenging and busy. 

Participants follow mission schedules, conduct scientific work, handle repairs, exercise daily, prepare meals with limited supplies, and deal with practice emergencies. Each task shows the kinds of challenges astronauts might face on real expeditions to the Moon or Mars. 

The habitat copies many parts of living in space. There isn’t much room, supplies are tightly controlled, and crew members can’t just leave if they feel stressed or miss home. 

Data transmission delays are built into mimic real Mars travel. On the International Space Station, astronauts talk to mission control right away, but Mars’ crews might wait minutes for a reply from Earth. This delay changes how they make choices in emergencies. 

Researchers also study how small teams handle disagreements for months at a time without outside help. 

What volunteers must give up for an entire year? 

Living in the habitat requires more than just physical strength. 

Participants have to be away from family, friends, vacations, holidays, and most of their normal life for about a year. The Internet, entertainment, and contact with loved ones are also very limited to match deep-space conditions. 

Volunteers also give up many small freedoms. They can’t go shopping, eat at restaurants, or take weekend trips. Each day is focused on mission plans, science goals, and team duties. 

The mental challenge is often harder than the physical one. 

Researchers know that boredom, repetitive routines, conflicts, and being stuck inside for long periods can gradually affect how people think and feel. Learning about these effects is a main goal of the NASA space habitat experiment. 

Who can apply for the NASA volunteer application in 2026? 

The NASA volunteer application 2026 is looking for healthy, motivated people who can work well under pressure. 

Applicants usually need education and experience similar to astronaut candidates, though the exact requirements depend on the CHAPEA mission. Good communication, emotional stability, teamwork, and problem-solving skills are all important in the selection process. 

Candidates undergo thorough medical checks, psychological tests, background checks, and several interviews before being selected. 

NASA wants people who stay steady under stress and can be a positive part of a close-knit team over the long term. 

Compensation and commitment are explained. 

Many people interested in applying want to know if volunteers get paid. 

NASA does pay volunteers, though the sum and compensation details depend on the mission and contracts. Participants aren’t giving up a year of their lives without support. The pay reflects the time and effort the research requires. 

The long-tail search phrase “NASA CHAPEA Mars analog simulation 2026 volunteer requirements pay compensation explained” captures one of the most common public questions surrounding the program. 

Applicants should know that the pay is for taking part in research, not for being an astronaut. The experience includes strict schedules, extensive monitoring, medical checks, and ongoing data collection throughout the mission. 

Artemis, Mars, and the commercial space race 

The science learned from the NASA CHAPEA Moon Mars simulation 2026 goes far beyond what happens inside the habitat. 

NASA plans to return astronauts to the Moon through the Artemis initiative before aiming for Mars in the 2030s. Choices about spacecraft engineering, crew size, food, medical gear, and mission timing all rely on solid data about how people perform. 

Comprehending human behavior is now just as important as rocket technology. 

Meanwhile, private space companies are working on ways to reach Mars. SpaceX’s Starship is the only spacecraft currently built primarily for long trips to Mars. The company hopes to launch its first uncrewed Mars mission in 2028, if everything remains on track. 

Before sending astronauts on these expeditions, NASA wants solid proof that crews can stay healthy, mentally strong, and able to work well during trips that last year, not just months. 

The Mars mission preparation simulation helps answer those questions before real lives are at stake. 

Why analog missions matter more than ever 

History shows that successful space missions require extensive testing before launching. 

Apollo astronauts practiced in mock spacecraft. International Space Station crews ran emergency drills many times before going to space. Mars expeditions need even stricter preparation because rescue won’t be possible. 

The long-tail keyword “NASA recruits volunteers yearlong Moon Mars simulation 2026 what it involves how to apply” indicates increasing public interest in these representative missions, which bridge the space between laboratory research and actual spaceflight. 

Scientists can’t test every situation during real missions for ethical reasons. Analog habitats allow them to study food systems, medical tools, communication, teamwork, and procedures in safe yet realistic settings. 

Each simulation helps reduce unknowns before people embark on one of the biggest journeys ever. 

A year on Earth could shape humanity’s future in space. 

The volunteers in NASA’s Houston habitat will stay on Earth, but what they learn can shape missions that travel hundreds of millions of miles away. Every talk, repair, tough choice, and teamwork moment helps make future space travel safer. 

As Artemis moves forward and private Mars plans grow, all these NASA simulations and volunteer programs are more than just research projects. They lay the careful scientific foundation needed before people can truly become an interplanetary species. 

Source: Sick of Earth? NASA is recruiting volunteers for a yearlong Moon and Mars simulation 

New York, New York | July 9, 2026 

The recent decline in technology shares has erased hundreds of billions of dollars in market value, leaving many investors wondering whether they should protect capital or put fresh money to work. That question has become even more relevant after the Philadelphia Semiconductor Index fell roughly 12% from its recent peak, despite continued strength in enterprise AI spending and cloud infrastructure investment. For investors searching for a tech stock selloff ETF opportunity, the current market weakness may represent one of the more compelling entry points of 2026. The case for an AI ETF buys dip July 2026 strategy depends less on predicting the market’s next move and more on identifying long-term structural trends that remain intact. A carefully selected semiconductor on ETF July 9 could offer diversified exposure while lowering the risks associated with owning individual technology stocks. 

Tech Stock Selloff ETF Opportunity: Why This Pullback Looks Different 

Tech market pullbacks can be unsettling because they tend to happen fast. Companies in semiconductors, AI software, and cloud infrastructure often see bigger price swings than the overall market. Still, history shows that some of the best long-term investments come after times of high volatility, not in market highs. 

The current selloff is mostly due to worries about high valuations, investors taking profits, and uncertainty about interest rates. However, demand for AI infrastructure stays strong. Big cloud companies are still spending billions on advanced computing, and businesses in healthcare, finance, manufacturing, and cybersecurity sectors are using AI more in their daily work. 

This difference is important. Short-term drops driven by investor sentiment are not the same as real problems in company performance. When looking at tech sell-off opportunities in Q3 2026, investors ought to assess whether earnings expectations remain solid rather than react only to lower stock prices. 

Why ETFs Offer a Smarter Approach Than Individual AI Stocks 

Artificial intelligence has led to some big winners, but it also brings a lot of ups and downs. One missed earnings report, a delayed product, or disappointing guidance can wipe out months of gains for a single company. 

Exchange-traded funds help reduce the risk of betting on a single company by allocating investments across many businesses. Instead of putting all your money into one chip maker or AI developer, you get exposure to the whole industry. 

For example, if you buy just one AI stock, your returns could suffer if the company faces management issues or tough competition. With an ETF, strong companies can help balance out weaker ones in the portfolio. 

This kind of diversification is especially helpful during market downturns, when investor emotions can amplify short-term price swings. 

Three ETFs That Stand Out During the July Pullback 

VanEck Semiconductor ETF (SMH) 

The VanEck Semiconductor ETF focuses heavily on leading chip manufacturers and equipment companies at the center of AI infrastructure development. 

SMH houses many of the largest companies that make advanced processors, memory, networking gear, and chip-making equipment. Because it focuses on these leaders, SMH usually has bigger ups and downs than wider tech funds. Investors who can handle more volatility might see bigger gains when semiconductor stocks bounce back. 

With the semiconductor ETF’s July 9 theme gaining attention following the recent correction, SMH remains one of the strongest options for investors seeking targeted exposure to AI infrastructure. 

iShares Semiconductor ETF (SOXX) 

SOXX offers greater diversification across semiconductor companies than SMH while still providing investors with good exposure to businesses that benefit from AI demand. 

This fund includes designers, manufacturers, equipment suppliers, and component makers from across the semiconductor industry. This broader mix can help smooth out some of the ups and downs while still allowing investors to benefit from lasting growth. 

With AI data centers growing around the world, the requirement for advanced chips goes far beyond just graphics processors. Networking components, memory, power management, and chip-making equipment all benefit from ongoing infrastructure spending. 

Global X Robotics & AI ETF (BOTZ) 

BOTZ takes a different path by investing in both artificial intelligence and industrial automation, including robotics. 

Instead of investing solely in semiconductor companies, BOTZ invests in businesses focused on automation, robotics, factory intelligence, and machine learning. This gives investors access to AI growth across many industries, not just chipmaking. 

Investors who want to participate in long-term automation trends may find BOTZ appealing, especially amid semiconductor price swings. 

Understanding the FTEC IYW tech ETF comparison July 9 

Broad technology ETFs are another option for investors who want to diversify beyond just semiconductors. 

The FTEC IYW tech ETF comparison July 9 centers on two important differences: cost and concentration. 

Fidelity’s FTEC usually has one of the lowest fees within tech ETFs, which is great for long-term investors who want to keep costs down. Lower fees can boost returns over the years, especially in retirement accounts. 

BlackRock’s IYW provides concentrated exposure to many of the largest tech companies. Investors who want more exposure to these giants might pick IYW, while those who prioritize low costs often choose FTEC. depends on an investor’s objectives, risk tolerance, and investment horizon. 

Dividend ETFs Serve a Different Purpose 

Although tech stocks are getting most of the attention right now, dividend-focused ETFs are worth considering if you want a more balanced portfolio. 

The NOBL HDV dividend ETF July 2026 discussion illustrates two distinct income strategies. 

NOBL invests in companies that have raised their dividends year after year for decades. These businesses usually have a steady cash flow and manage their money carefully. 

HDV, on the other hand, looks for companies that pay higher dividends and have solid financial conditions. 

If you want steady income and less ups and downs in your portfolio, you might combine dividend ETFs with tech ETFs, rather than seeing them as competing choices. 

Lower Costs Matter More Than Many Investors Realize 

Expense ratios don’t make up the news, but they have a big impact on how your investments perform over time. 

A tech ETF lower-cost 2026 strategy recognizes that even modest annual fee differences compound significantly over twenty or thirty years. Paying lower management fees allows investors to retain a greater share of market returns. 

This is especially important for people who invest regularly through retirement plans or brokerage accounts over many years. 

Dollar-Cost Averaging Works Best During Volatile Markets 

When markets drop, it’s tempting to wait for the perfect time to buy. But it’s almost impossible to pick the exact bottom every time. 

Dollar-cost averaging is a more disciplined way to invest. 

Instead of putting all your money in at once, you spread your investments over several weeks or months. For example, if you want to invest $12,000, you could contribute $2,000 per month for 6 months. 

If the market keeps dropping, your later investments will buy more ETF shares at lower prices. If the market bounces back sooner, your earlier investments still benefit from the recovery. 

This steady approach helps you sidestep emotional decisions and stick to your long-term investment plan, even when markets are volatile. 

What Investors Need to Watch Next 

Corporate earnings over the next few quarters will show whether spending on AI infrastructure continues to drive semiconductor demand. 

Cloud companies are still expanding their computing power; more industries are adopting AI, and governments around the world are focusing more on producing semiconductors domestically. 

These ongoing trends suggest that the recent market drop is more about adjusting prices than about real problems with the underlying businesses. 

Investors searching for a tech stock selloff in July 2026 create one ETF buying opportunity. What investors need to know is that successful investing rarely depends on perfectly timing the market. Building diversified positions gradually through high-quality ETFs often proves more effective than chasing individual technology winners after headlines turn positive again. 

Likewise, anyone asking which tech ETF to buy during the July 2026 selloff FTEC vs IYW NOBL HDV comparison guide should first determine whether the objective is growth, income, lower costs, or broader diversification. Those priorities ultimately matter more than choosing a single “best” ETF. 

Markets don’t usually reward certainty—they reward preparation. If AI investment keeps growing, investors who steadily bought diversified semiconductor and tech ETFs during unstable periods may find that today’s volatility leads to tomorrow’s gains.

Source: Tech Stock Sell-Off: 1 ETF to Load Up On Right Now 

Boise, Idaho | Dateline: July 9, 2026 

A stock that has climbed roughly 180% year-to-date rarely attracts bargain hunters after a correction. Yet Micron Technology’s recent 22% decline has shifted the conversation from chasing momentum to evaluating value. Investors now face a straightforward question: Is this simply a pause in one of the strongest artificial intelligence infrastructure stories, or the beginning of a wider slowdown in AI spending? That discussion intensified after the Micron-Anthropic deal in 2026 reinforced the company’s expanding position in AI memory, while analysts continued to defend the MU stock target of $1,100. For investors looking at the Micron AI memory buy dip, the timing could prove decisive. 

Micron Anthropic deal 2026 Strengthens AI Infrastructure Leadership. 

The announcement of the Micron Anthropic deal in 2026 signifies another milestone in Micron Technology’s strategy to become a key supplier of advanced artificial intelligence systems. Under the partnership, Micron will supply high-performance memory for training and inference of Anthropic’s Claude model. 

This agreement stands out because memory is now one of the main bottlenecks in AI computing. As language models get bigger and more widely used, developers need much more memory bandwidth along with stronger GPUs. High Bandwidth Memory (HBM) has become a key part of today’s AI servers. 

Instead of depending on the ups and downs of PC or smartphone demand, Micron is moving toward long-term deals with key AI customers. Earlier this year, it signed a strategic agreement with General Motors for automotive memory, indicating that its growth plans extend beyond cloud computing. 

These joint ventures help Micron expand its revenue and reinforce its position in two industries that are likely to see reliable demand for semiconductors in the next decade. 

Why Analysts Continue Supporting the MU stock target $1100 

Even after the recent drop, analysts at TradingKey continue keeping the MU stock target at $1100. 

Their optimism is based on solid factors, not just short-term trading excitement. 

Micron recently reported record quarterly revenue, mainly thanks to strong AI memory demand. More importantly, management said its HBM production is basically sold out through 2027. This gives investors more confidence in near-term revenue growth. 

Unlike past semiconductor cycles driven by short-term inventory needs, today’s AI infrastructure spending is backed by long-term investments from major cloud providers, enterprise software firms, government AI projects, and model developers like Anthropic. 

Investors evaluating the MU stock $1100 AI memory boom thesis therefore focus less on quarterly volatility and more on structural demand extending several years into the future. 

Why the Pullback Has Attracted Buy-the-Dip Investors 

All major semiconductor rallies go through corrections. 

Micron’s 22% drop has prompted investors to revisit its valuation after such a big run-up. 

The argument supporting the Micron 22 percent pullback buy dip centers on one simple observation: business fundamentals have remained considerably stronger than the stock’s recent performance. 

Revenue continues to expand. 

Margins remain elevated. 

HBM demand continues to be constrained by supply. 

Large AI customers continue signing long-term agreements. 

This situation is very different from past semiconductor downturns, when excess inventory usually leads to steep price cuts by memory makers. 

Supporters of the Micron AI memory buy dip argue that today’s correction resembles profit-taking after an extended rally rather than deteriorating fundamentals. 

History shows that top tech companies often see sharp drops even during long bull markets. Nvidia, Amazon, Apple, and Microsoft have all experienced similar declines but have continued to grow over time. 

Micron investors are hoping the same pattern happens again. 

The Critical Significance of the Micron Anthropic partnership supply 

The Micron Anthropic partnership supply agreement carries importance beyond immediate revenue. 

Anthropic is now one of the top developers of advanced AI models, competing with OpenAI, Google, Meta, and xAI. By working with Anthropic, Micron moves closer to the core of next-generation AI infrastructure. 

Memory performance is becoming more important for how well large language models handle billions of parameters during training and inference. 

GPUs get most of the focus from investors, but without enough memory bandwidth, AI accelerators can’t reach their full potential. 

That’s why memory suppliers are now seen as central players in the AI supply chain. 

The Micron Anthropic partnership supply agreement therefore reinforces Micron’s competitive posture while validating management’s emphasis on premium memory technologies rather than commodity products. 

The Bull Case: AI Memory Demand May Last Much Longer 

The strongest argument supporting the MU stock $1100 AI memory boom centers on structural demand rather than cyclical recovery. 

Artificial intelligence adoption continues to expand across healthcare, finance, manufacturing, cybersecurity, automotive technology, and enterprise software. 

Each deployment calls for extensive computing infrastructure. 

Each AI server requires advanced memory. 

Each new generation of AI models typically consumes even greater memory capacity than previous versions. 

More industry analysts now think demand for AI memory could stay high for the rest of the decade, rather than peaking after just one investment cycle. 

Micron’s management keeps saying that HBM production is sold out through 2027, indicating that customer demand exceeds its supply. 

This supply-demand gap helps keep prices strong and protects profit margins. 

If these trends continue, analysts say the current stock price may still be too low relative to Micron’s upcoming earnings potential, even after this year’s big gains. 

The Bear Case Investors Cannot Ignore 

Every investment idea comes with real risks. 

One worry is how much cloud companies will continue to spend on infrastructure. 

Meta’s push to build more of its own AI infrastructure has raised questions about whether its big investments could eventually lead to an oversupply in parts of the semiconductor market. 

If cloud providers slow spending after completing current AI projects, demand for cutting-edge memory could level off. 

Competition is still fierce. 

Samsung and SK Hynix are also investing heavily in HBM production. 

If supply eventually outpaces demand, prices could fall faster than some expect. 

Valuation is another important factor to consider. 

Even after the recent drop, Micron’s stock is still priced well above its historical averages, as investors expect strong AI-driven earnings growth. 

If revenue growth falls short, the stock could become even more volatile. 

These risks explain why the Micron recovery July 2026 narrative stays closely tied to execution rather than market mood alone. 

Can the Micron recovery July 2026 Continue? 

Micron’s recovery in July 2026 will mostly depend on whether management can turn AI excitement into long-term financial results. 

A few key indicators will be important to watch in the next few quarters. 

Revenue growth from AI customers should stay robust. 

HBM production utilization should remain near full capacity. 

Gross margins should continue benefiting from a premium product mix. 

Additional long-term customer agreements would further strengthen revenue visibility. 

If these numbers keep getting better, the recent drop could end up looking like a healthy pause in a longer-term upward trend. 

But if any of these indicators worsen, investors might reconsider whether the stock warrants its high valuation. 

Valuation Versus Momentum 

Momentum investing can often lead to emotional decisions. 

Fundamental investing means looking past price swings and focusing on how the business is actually performing. 

Micron’s recent drop has eased some of the pressure on its valuation, but hasn’t really changed its strong position in AI infrastructure. 

Record revenue, more enterprise partnerships, growth in automotive, and tight HBM supply all give real reasons for optimism. 

At the same time, investors should remember that semiconductor stocks rarely go up in a straight line. 

Drops of 20% or more are common, even in long bull markets. 

This perspective helps explain why analysts continue defending the MU stock target of $1100 despite recent volatility. 

Investment Outlook 

The Micron-Anthropic AI deal signals an $1100 stock target despite a 22 percent pullback in July 2026; the narrative ultimately reflects a broader shift in how investor view semiconductor companies. Instead of seeing memory as just a cyclical commodity, the market now views premium AI memory as a key infrastructure for the future of computing. 

For investors asking, should you buy Micron MU stock after a 22 percent dip, Anthropic deal, $1100 target analysis July 2026, the answer depends less on short-term price swings than on faith in sustained AI investment. If enterprise adoption, cloud expansion, and frontier model development persist, driving demand for cutting-edge memory, Micron’s recent correction may prove temporary. If AI infrastructure spending cools more quickly than expected, additional volatility remains possible. The next quarters will likely determine whether this pullback becomes remembered as a buying opportunity—or simply the first pause in a more selective phase of the AI investment cycle.

Source: Micron Technology (MU) Stock Forecast: AI Memory Boom Keeps Bulls Focused on $1,100 After Trendline Rebound 

Wilmington, Delaware | July 9, 2026 

About $27 billion disappeared from AstraZeneca’s market value within hours after a single data release on Thursday morning. This shows that even the strongest drug pipelines in European pharma are still vulnerable to the risks of Phase 3 trials. The AstraZeneca heart drug failure in 2026 came as a real shock, not only a minor setback, and its effects reached well beyond the company’s listings in London and New York. 

The drug in question is Wainua, known chemically as eplontersen, developed jointly with Ionis Pharmaceuticals. The AZN cardiac drug clinical trial, called CARDIO-TTRansform, tested whether adding Wainua to standard care could reduce cardiovascular death and recurrent heart events in patients with transthyretin-mediated amyloid cardiomyopathy, a progressive condition in which misfolded proteins accumulate in heart tissue and stiffen its walls. Over a 140-week observation period across more than 1,400 patients, the composite primary endpoint did not separate from placebo at a statistically significant level. In plain terms, the AstraZeneca drug flatlines clinical trial data told investors exactly what the headline suggests: no meaningful benefit, despite years of waiting and a projected multibillion-dollar opportunity. 

What the Trial Was Supposed to Prove 

ATTR-CM is not a rare disease. AstraZeneca estimates that between 300,000 and 500,000 people worldwide have it, though many are not diagnosed until their heart failure is already serious. Wainua works by preventing the liver from producing transthyretin, just like Alnylam’s competing drug, Amvuttra. Citi analysts had expected that Wainua could become a blockbuster in this area, but the failed trial wiped out those expectations almost immediately. 

The details of why the trial failed are important because they help explain Wall Street’s strong reaction. At the start, 57% of patients in each group were already taking another stabilizer drug, and about a quarter more started one during the study. Some analysts pointed out that this could have obscured any additional benefit from Wainua, since most patients were receiving two treatments at once. Sharon Barr, AstraZeneca’s head of biopharmaceutical research, admitted the trial missed its goal but said the data would still help researchers understand the disease better when more results are shared at the European Society of Cardiology Congress in August. 

The Market’s Verdict on July 9 

The biotech stocks July 9, 2026, trading session opened with AstraZeneca shares down roughly 8 to 10 percent in both London and New York, marking the stock’s steepest single-day decline in months and briefly making it the biggest loser on the FTSE 100. Ionis, which stood to collect royalties on any cardiomyopathy approval, fell even harder, with premarket declines exceeding 13 percent, widening to over 20 percent as the session progressed. The biotech sell-off on AZN’s July 9 episode wasn’t so much about broad sector fear as about a single, idiosyncratic clinical miss punishing the two companies most directly exposed to it. 

That distinction turned out to be vital. This was not a case where every biotech stock was dragged down together. Rather, the cardiac drug AstraZeneca Phase 3 failure caused a clear split: AstraZeneca and Ionis dropped sharply, while their competitors in the ATTR-CM field saw their shares rise just as much. Alnylam Pharmaceuticals, whose Amvuttra is now the only approved gene-silencing therapy for this type of heart disease, saw its shares jump by double digits. BridgeBio Pharma, which makes the oral stabilizer Attruby, also gained. Pfizer, whose Vyndamax already leads the ATTR-CM market with about $6 billion in annual sales, was seen as a winner, too, since another competitor was out of the running for now. 

Competitive Fallout: Who Gains What AstraZeneca Lost 

The AstraZeneca heart drug flatlines in a clinical trial miss, sending biotech stocks down. July 9, 2026, hides a more complex picture about market share. Before this, the ATTR-CM field was expected to have a fourth major competitor by 2027. Now, Alnylam basically has a monopoly among gene-silencing therapies for this heart condition, since Wainua’s failure removes the only similar drug from the near future. Stifel analysts said the situation is complicated for Alnylam, since the company also has a second-generation drug, nucresiran, moving through its own Phase 3 trial. So, Thursday’s news both removes a competitor and makes Alnylam’s following steps less urgent. 

Wainua is still on the market as a commercial product. It was first approved in December 2023 for treating polyneuropathy linked to hereditary transthyretin amyloidosis, a nerve condition not affected by the recent heart trial results. While this business is smaller than the heart drug opportunity AstraZeneca wanted, it still brings in revenue in over 20 countries. What was lost on Thursday was the hope for a multibillion-dollar expansion, not the drug’s whole commercial future. 

Reading the Biotech ETF Signal Correctly 

Here the data complicates the simplest version of the headline. The biotech ETF impact AZN miss did not play out as a sector-wide decline. Both the iShares Biotechnology ETF and the SPDR S&P Biotech ETF, which track AstraZeneca’s clinical outcomes alongside dozens of other pipeline-stage names, actually traded modestly higher on the session, with the SPDR fund up roughly 0.7 percent and the iShares fund essentially flat. That outcome shows how differently the two benchmarks are constructed: the iShares fund is market-cap weighted, giving its largest constituents outsized influence, while the SPDR fund is equal-weighted across roughly 145 holdings, which means a single company’s disappointment is diluted by the fortunes of many smaller names. In this instance, gains at Alnylam and BridgeBio offset the drag from AstraZeneca and Ionis almost entirely across both baskets. 

What This Means for Biotech Investors 

The AstraZeneca cardiac drug failure, July 2026 investor impact, biotech sector selloff analysis ultimately points to a lesson that seasoned biotech investors already know but occasionally forget during rally years: diversified sector exposure absorbs single-company shocks, even when individual holdings suffer real, painful losses. AstraZeneca’s own strategy, which leans on roughly 10 Phase 3 readouts expected before the end of 2026, including trials for the breast cancer drug camizestrant and the lung cancer therapy Datroway, means Thursday’s disappointment is unlikely to be the last binary event the stock faces this year. Investors following the company’s next catalysts would do well to remember that a single trial, however large or well-designed, only ever tells part of a much longer story about where cardiovascular medicine is heading next.

Source: Breakfast News: AstraZeneca’s Heart Drug Flatlines 

Washington DC  

Sixty-seven years old, three Olympic Games, and now a mugshot’s worth of infamy: that is the improbable arc of a man who spent his career navigating whitewater, not federal indictments. The David Hearn Reflecting Pool vandalism case has turned a quiet bike ride along the National Mall into a national referendum on prosecutorial discretion, monument security, and the price of curiosity in Washington, D.C. 

A Decorated Paddler Meets a Grand Jury 

David Hearn may not be widely known outside of canoeing, but in that sport, he is a legend. He competed for the United States in whitewater slalom at the 1992 Barcelona, 1996 Atlanta, and 2000 Sydney Olympics—a rare achievement among American paddlers. Hearn has spent most of his adult life in the Washington area, living most recently in Bethesda, Maryland, not far from the monument now at the center of his legal troubles. 

That biography is precisely why the Olympic canoeist felony charge against him has generated outsized attention. Federal and D.C. prosecutors do not often indict retired Olympians on property crimes, and the collision of celebrity, patriotism, and prosecutorial muscle has made this arraignment a story that extends well beyond the sports pages. 

What Happened at the Pool 

The case started on June 19, when Hearn stopped at the Lincoln Memorial Reflecting Pool during a 64-mile bike ride. He says he noticed the pool’s new blue coating peeling and turning green with algae, so he reached in to check out a loose piece, describing his actions as simple curiosity. However, National Park Service staff and U.S. Park Police claim he forcefully pulled up and removed about two square feet of the liner with both hands, a version Hearn’s lawyers call “concocted.” 

He was initially detained for roughly five hours on a misdemeanor charge, but on July 2, a grand jury escalated the matter, indicting him on a single felony count of destruction of property causing more than $1,000 in damage. That elevation from misdemeanor to felony is central to understanding the Lincoln Memorial pool vandalism 2026 controversy: under D.C. law, the dollar threshold for property damage determines whether a defendant faces a citation or a prison sentence, and prosecutors say Hearn’s alleged conduct cleared that bar. If convicted, he faces up to ten years behind bars. Court filings describing the Lincoln Memorial Reflecting Pool damage put the figure at roughly two square feet of removed sealant, a modest patch of material that nonetheless carries outsized legal consequences given the pool’s status as a protected national landmark. 

The Arraignment 

David Hearn pleaded not guilty; Washington, D.C., was the headline out of D.C. Superior Court on Thursday, where Hearn entered his plea through counsel during a packed initial appearance. Judge Carmen McLean released him on his own recognizance, declining a government request to bar him from the pool while the case proceeds. A status hearing has been set for August 5, giving both sides roughly four weeks to build their arguments before the next public checkpoint in the case. 

Hearn did not say much outside the courthouse, but the atmosphere was energetic. Supporters greeted him with chants of “Davey! Davey!”, showing their belief that the prosecution is too harsh. His lawyer, Norm Eisen, was even more direct, calling the case a political move to find someone to blame for the pool renovation’s problems and arguing that touching water in a public fountain should not be considered a crime. 

The Renovation Backdrop 

This situation did not happen in isolation. The Reflecting Pool, which runs about 2,000 feet between the Lincoln Memorial and the Washington Monument, was renovated this spring. The project’s cost grew from under $2 million to over $14 million and was supposed to be finished before the country’s 250th anniversary celebrations on the Fourth of July. Instead of the promised “American flag blue,” the new liner began peeling right away, and algae turned the water green, embarrassing organizers during the nationally televised Salute to America event. 

This embarrassment is an important background. U.S. Attorney Jeanine Pirro has described the alleged damage as a deliberate attack on a newly restored national landmark. She told reporters that damaging monuments is an insult to common history and that the law applies to everyone. Hearn is not the only one charged; prosecutors say at least six others were arrested on related misdemeanor charges connected to the pool project, showing how seriously officials are treating any perceived DC property vandalism in 2026 near the National Mall this year. 

A Case Built on Competing Narratives 

The main issues in the case are intent and the extent of the damage. Government documents mention that a caulk-and-foam sealant was cut with a sharp tool elsewhere along the pool, but officials say Hearn is not accused of using a blade. Hearn’s account, partly supported by a park worker who told him to let go of the material, suggests his actions were quick and impulsive, not planned sabotage. The difference between “forceful removal” and “brief curiosity” will likely be central if the case goes to trial. 

Other Olympic paddlers have supported Hearn’s version of events. Paul Flack, a former national team canoeist who has known Hearn since 1978, told reporters he understands the urge to touch peeling material. He explained that athletes with years of experience working with water surfaces and coatings often want to check the texture and quality themselves. While this is an unusual way to defend someone’s character, it shows how important Hearn’s long career in paddling is to the story. 

Why This Case Echoes Beyond D.C. 

The bigger issue is what this prosecution says about monument security during the 250th anniversary year. The Lincoln Memorial and its Reflecting Pool are among the most visited and photographed places in the country, so any problems with renovations get a lot of attention, no matter the cost. In most years, a felony charge for a visitor touching shallow water would be hard to imagine, but in 2026, with so much focus on the mall, it has become a major issue. 

For readers searching to understand the full sequence, the essential summary is this: Former US Olympian David Hearn pleads not guilty to felony property damage at the Lincoln Memorial pool. He was indicted after a June incident that he says was harmless curiosity, while prosecutors call it deliberate destruction. Those looking for the complete procedural history, from arrest to indictment to arraignment, will find that the David Hearn Olympic canoeist Reflecting Pool vandalism case what happened, charges explained, 2026 ultimately depends on a single, contested gesture at the edge of a national monument. 

What Comes Next 

The status hearing on August 5 will be the first real sign of how prosecutors plan to present their case and whether Hearn’s defense team can narrow the charge before trial. Given the scale of scrutiny already surrounding the renovation and the political undertones both sides have injected into the proceedings, this former US Olympian’s felony charge is unlikely to fade quietly from the headlines. Whatever the outcome, the episode has already changed how the National Park Service manages its most famous pool, turning a retired paddler’s curiosity into a test of how Washington enforces property laws at a landmark site.

Source: Former US Olympian David Hearn pleads not guilty in Reflecting Pool vandalism case 

Washington, DC.  

For 116 years, Washington’s skyline has been limited to 130 feet. But on July 9, 2026, a federal commission decided that a president’s monument was worth stretching it by 120 feet. The Trump triumphal arch Washington, DC, 2026 project cleared a critical procedural hurdle Thursday, when the National Capital Planning Commission’s arch review concluded with preliminary approval, despite almost three hours of public testimony urging them to reject it. 

The vote is not final. It delays the debate over the monument’s height, sightlines, and the example it sets until September, when the commission will make its final decision. Still, it shows that in this administration, monuments can move forward quickly and mostly according to the wishes of a small group close to the president. 

What the Commission Actually Approved 

Thursday’s meeting, part of the ongoing Trump DC arch review, focused on preliminary site and building plans rather than a final green light. Commission staff, in an 185-page report released before the meeting, recommended approving these early plans but pointed out that they directly conflict with the Height of Buildings Act of 1910, the law that has kept Washington’s skyline low and easy to recognize for over a century. 

The planned arch would be 250 feet tall, made up of a 166-foot mezzanine, a 24-foot observation deck, and a 60-foot Lady Liberty statue on top. This goes well over the Height Act’s 130-foot limit. Staff suggested a compromise: reduce the mezzanine to 130 feet and the observation deck to 20 feet, while technically complying with the law. The Interior Department has argued that the Height Act does not apply to federal buildings, but the commission disagrees. Commission Chairman Will Scharf, who is also Trump’s White House staff secretary, said he expects a strong debate on this issue before the September vote. 

The Design and Its Site 

The Trump 250-foot arch Washington, DC, Harrison Design proposal did not emerge from an open competition. Architecture studio Harrison Design has produced the renderings shown to the public and the National Park Service, which manages Memorial Circle. This is the traffic circle on the Virginia side of Arlington Memorial Bridge where the arch would be built. One popular rendering shows the arch lit up at night, with its opening framing Arlington House, the Custis-Lee mansion that overlooks Arlington National Cemetery. 

Preservationists are especially worried about this framing. Memorial Circle was designed almost a century ago to create a direct line of sight between the Lincoln Memorial and Arlington National Cemetery, symbolizing postwar reunification between North and South. Building an arch more than twice as tall as the 99-foot Lincoln Memorial in this spot would not just add a new landmark. It would change the view that the corridor was meant to protect. 

Public Testimony and the Cost of Speed 

The National Capital Planning Commission July 9 hearing drew opponents ranging from historians to military families. Cynthia Morrison, a Gold Star mother from North Carolina, told the commissioners that the view toward Arlington National Cemetery was personally meaningful because of her son’s service and the Tomb of the Unknown Soldier. She said that an arch dominating that view would affect something tied to memory, not just appearance. Her comments reflected a larger point made by historic preservation experts, who have said that a monument of this size should not be rushed or controlled by only a few people. 

This criticism matters because of who has been involved in developing the project. Design critic Catesby Leigh first suggested the arch idea in April 2025 on a conservative think tank’s website, using sketches from two sources: local architect Nicolas Charbonneau, whose firm Harrison Design later made the official renderings, and a group led by Rodney Mims Cook Jr., a developer Trump chose to lead the U.S. Commission of Fine Arts. Cook later voted as chairman of that commission to approve the arch’s design in May, without the usual open review or input from Congress that memorial projects often require. All other members of the Fine Arts Commission were also Trump appointees, and only one had formal training in architecture. Since then, a group of veterans and historians have sued the administration in federal court to stop construction because of its impact on the cemetery’s view. 

Skyline Precedent and the Arc de Triomphe Comparison 

Much of the public debate keeps returning to a single image: the Trump arch National Mall skyline silhouette before Washington’s famously flat horizon. The comparison Trump himself has invoked is Paris’s Arc de Triomphe, a 164-foot monument he has cited as his model and inspiration. His proposed structure would stand roughly 86 feet taller, more than 50 percent larger than the Parisian original, and would edge close to half the height of the Washington Monument, which rises about 555 feet. Supporters frame that scale as a fitting tribute to the country’s 250th anniversary; critics call it an aesthetic mismatch with a city whose entire built environment was shaped around restraint. 

The stakes go beyond one structure. Approval of a Trump DC monument 2026 at this height, achieved through a compressed assessment timeline and a commission stacked with the president’s allies, would set a working example for how future federal monuments in Washington are chosen and approved. This is the main concern behind Thursday’s testimony: not just whether the arch should be at Memorial Circle, but whether the rules that have formed Washington’s skyline for over a century can withstand pressure from the White House. 

Officially, the review is still ongoing. The record now shows what happened when the National Capital Planning Commission reviewed the Trump triumphal arch on July 9, 2026, and that the commission is willing to move the project forward even though it currently violates federal law. Whether the September vote sincerely solves this problem or just covers it up with a new mezzanine design will show whether Washington’s skyline law still has real meaning. 

What Comes Next 

The Trump triumphal arch Washington DC design controversy National Mall skyline commission vote 2026 now moves toward a September reckoning, when the commission is expected to weigh final site and building plans alongside outstanding questions on vehicular traffic around Memorial Circle, the arch’s granite exterior, and the Height Act compliance issue staff have previously flagged. Litigation from veterans’ groups adds a second track that could outlast the commission’s own calendar. Whatever the commission decides, the arch has already accomplished something rarer than construction: it has forced Washington to ask, in public and under oath, how much of its skyline one single administration can rewrite before the law that protects it stops being a law at all.

Source: National Capital Planning Commission considers Trump’s triumphal arch plan 

Kinshasa, DRC | Dateline: July 8–9, 2026 

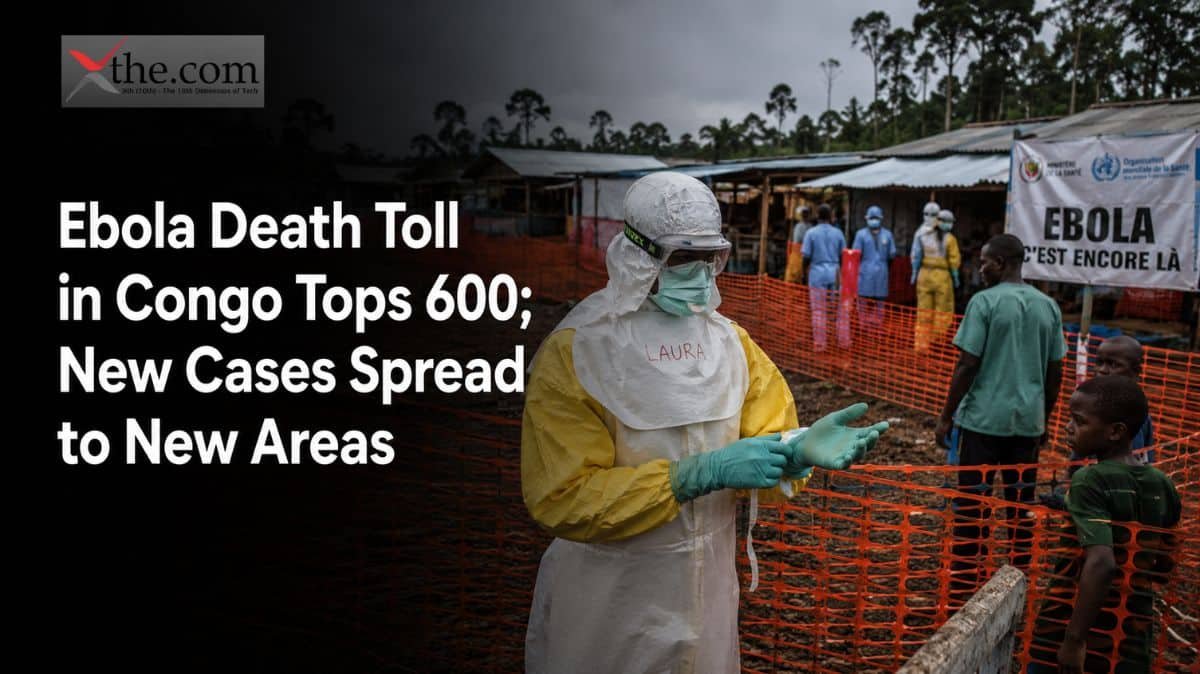
Six hundred people are dead, and the map of danger just grew larger. This is now a global health emergency Ebola 2026watchers cannot dismiss as a regional problem. The Ebola Congo death toll 600 milestone, confirmed by the Congolese health ministry this week, would be grim enough on its own. But the more alarming signal buried in the same government report is geographic: suspected infections have now surfaced in Tshopo and Haut-Uele, provinces that had recorded zero cases since the crisis began. The Ebola DRC 2026 outbreak has officially outrun its original containment zone, and the implications stretch from rural health posts in the Congo Basin to boardrooms at the world’s largest vaccine manufacturers. 

A Fast-Moving Outbreak Enters New Territory 

The Democratic Republic of Congo declared the outbreak on May 15, after the virus had already been circulating undetected for weeks in Ituri Province. By early July, confirmed cases nationwide had climbed past 1,750, and the Congo Ebola new provinces development — two suspected infections identified in Kisangani, the capital of Tshopo, marking the outbreak’s spread to a fourth province. One of these patients is linked to the Nia-Nia health zone in Ituri, but the other has no known connection. This worries epidemiologists even more than the rising death toll, as it points to community transmission that has not yet been tracked. 

This crisis is moving quickly. The Africa Centers for Disease Control and Prevention says it is the fastest-growing Ebola outbreak ever seen in Africa. Thirty-seven out of 104 health zones in the DRC now have confirmed cases. North Kivu has reported 149 cases and 88 deaths. South Kivu, though less affected, has already lost one of its three confirmed patients. Each new affected province adds to the challenges facing a health system already under strain. 

Why Bundibugyo Virus Changes the Calculus 

What makes this outbreak different is the virus behind it. Unlike the Zaire ebolavirus that caused the 2014–2016 West Africa epidemic and other recent outbreaks for which licensed vaccines are available, this one is caused by the Bundibugyo virus. This rarer species was last seen in large numbers over ten years ago, and there is currently no licensed vaccine or approved treatment for it. In past Bundibugyo outbreaks, the fatality rate has ranged from 30% to 50%. This outbreak is also happening in an area already affected by armed conflict in eastern Congo, where attacks on health facilities and a lack of funding have made contact tracing very difficult. 

Helping people in the newly affected areas is even harder. Tshopo and Haut-Uele are hundreds of kilometers from where the outbreak started. The roads frequently flood during the rainy season, and rivers are the only dependable way to travel. Vaccination campaigns and contact-tracing teams that took weeks to set up in Ituri now have to start over in places with little or no infrastructure. 

The Global Health Emergency Ebola 2026 Response 

The World Health Organization acted quickly. On May 17, the WHO Director-General declared the outbreak a Public Health Emergency of International Concern, the group’s highest alert level, after the Bundibugyo virus was found to have spread from the DRC to Uganda, where a Congolese man died in Kampala. This declaration triggered coordinated international funding and surveillance under the International Health Regulations, and it remains in force as the Congo Ebola 2026 WHO response effort scales with the outbreak’s geographic spread. The Africa CDC issued a parallel declaration, a Public Health Emergency of Continental Security, showing how seriously regional health officials view the cross-border threat. 

Funding has followed the emergency, though not always evenly. The United Kingdom pledged up to £20 million for affected communities. The U.S. State Department later announced $112 million in aid for protective equipment, screening, and diagnostics. However, cuts at American health agencies have made the U.S. less visible on the ground than in past outbreaks, according to independent observers. The European Union added €15 million. Gavi, the Vaccine Alliance, has committed $50 million through its First Response Fund, with some money set aside to protect health workers and up to $40 million to accelerate the development of a vaccine that does not yet exist. 

The Vaccine Gap Investors Need to Understand 

This is where the market situation becomes more complex, and clear information is more important than hope. Merck’s Ervebo and similar vaccines for the Zaire species are in the Gavi-funded emergency stockpile, but they target a different virus. Now, manufacturers and researchers are working quickly to determine whether any current vaccine candidates can protect against the Bundibugyo virus. Clinical trials for an experimental treatment started last week at the Evangelical Medical Center in Bunia. About 2,000 doses of the Ebola vaccine are already in the DRC, ready for trials if WHO experts deem it justified, but no company has a licensed vaccine for this strain yet. Gavi and UNICEF have asked manufacturers to show interest in developing Bundibugyo-specific vaccines, with early research funding from the Coalition for Epidemic Preparedness Innovations. For pharmaceutical investors and global health funders, there is a real opportunity here, but it is still in the development stage, not ready for stockpiling. 

Ebola DRC Spread Unaffected Areas: What Comes Next 

Anyone who has followed Ebola outbreaks in the Congo Basin knows that containment in one zone buys time, not victory, if surveillance in neighboring provinces lags. The larger pattern of Ebola DRC spread unaffected areas reporting is precisely what worries the WHO’s Emergency Committee, because each new health zone means responders must rebuild logistics chains from the ground up. Ebola Congo 600 deaths new provinces affected will likely continue unless contact tracing in Tshopo and Haut-Uele improves quickly. Health officials in Kinshasa have called for more case detection, safe burials, and community involvement—steps that worked against Zaire ebolavirus outbreaks but are now being used against a virus with much less experience behind it. 

The next month will show whether international funding turns into real action quickly enough to stop a virus that has already spread farther and faster than expected. “Ebola death toll Congo tops 600 July 2026 new cases suspected previously unaffected provinces” is this week’s headline. Whether this becomes the story of a contained crisis or a growing one now depends on choices made in provincial health offices, in Geneva, and in vaccine company boardrooms in the coming weeks. This makes the “Congo DRC Ebola outbreak 2026 600 deaths spread new areas WHO response investor healthcare impact” story one that global health funders and pharmaceutical leaders cannot afford to ignore.

Source: Ebola death toll in Congo tops 600. New cases also suspected in previously unaffected provinces 

Washington, D.C. | July 9, 2026 

A house that would have cost $432,700 a year ago now costs $440,600 — and fewer people can afford to buy it. That’s the paradox at the center of the US home prices’ record 2026 data released Thursday by the National Association of Realtors. The median home price hit an all-time high even as the number of homes actually changing hands continued to fall. This is not a market rewarding seller with a bidding frenzy. It is a market where scarcity, not demand, is writing the price tag. 

Existing Home Sales Slow While Prices Climb 

The NAR’s existing home sales July 9 data paint an uncomfortable picture for anyone hoping the housing market in July 2026 will be better. Existing home sales dropped 2.4% from May to a seasonally adjusted annual rate of 4.09 million units, which is well below the 4.21 million that economists at FactSet expected. Sales are up 2.8% from a year ago, but that small increase is minor compared to the past: annual sales have stayed near 4 million since 2023, while the long-range average is closer to 5.2 million. 

Meanwhile, the median sales price rose 1.8% year-over-year to $440,600, a record on data stretching back to 1999. It marked the 36th consecutive month of annual price gains. US existing home sales slow July 9 figures like these rarely arrive alongside record pricing, but 2026 is proving to be an exception, and the explanation has less to do with buyer enthusiasm than with a housing stock that refuses to grow. 

The Rate Shock Behind the Slowdown 

This week’s new worries for buyers started with global events. After President Trump announced the end of the fragile ceasefire with Iran, crude oil prices jumped, and investors quickly sold longer-term bonds. The yield on the 10-year Treasury notes, which lenders use to set mortgage rates, rose to about 4.57%, its biggest single-day increase in weeks. According to Freddie Mac, the average 30-year fixed mortgage rate was 6.49% for the week ending July 9, up from 6.43% the week before. Zillow reported a rate of 6.39%. Both rates are still lower than a year ago, but the trend is upward, just like oil prices. This is not what buyers wanted as summer continues. 

This is the essence of mortgage rates home sales slow as a market dynamic: it is not one force pushing buyers to the sidelines; it is two. Call it the home prices all-time high mortgage rates trap — a pincer that squeezes purchasing power from both directions, and no amount of patience solves either problem on its own. 

A Three-Way Squeeze on Would-Be Buyers 

Anyone looking to buy a home this month faces three main challenges. Prices are at record highs. Mortgage rates are near the top of their recent range. And even though inventory is a bit better than in 2022 and 2023, it is still very low. Many homeowners have 3% mortgages from the pandemic and do not want to sell and take on a much higher rate. Instead, some are choosing to rent out their homes, which reduces the number of homes for sale but adds to the rental market. 

Lawrence Yun, the chief economist at the National Association of Realtors, has been clear about the main problem. He says affordability remains a big barrier for people who want to buy a home, and the solution is to increase supply, not just adjust to demand. This corresponds to research from the Harvard Joint Center for Housing Studies, which found that the median single-family home now costs about five times the median household income, compared to about 3.2 times in the 1990s. Homes affordable to households earning $75,000 or less have dropped from nearly half of all listings in 2019 to less than a quarter today. 

First-Time Buyers Bear the Brunt 

First-time buyers are feeling the 2026 housing affordability crisis in 2026 more than anyone else. Analysts say these are the toughest conditions since at least the early 1980s, and the numbers back that up: first-time buyers now account for only about one in five home purchases nationwide, a record low. The average age of a first-time buyer is now close to 40, about ten years older than in the past. Each year spent renting rather than owning widens the wealth gap, since home equity is the primary means by which most American families build wealth. 

Where Investors Are Positioning 

Wall Street has already reacted to these changes. Homebuilder stocks have struggled because higher rates make new homes less affordable and reduce the number of buyers who can qualify for mortgages. On the other hand, residential REITs and property management companies are benefiting as more people rent for longer and as homeowners who cannot sell profitably become landlords. This split is becoming a lasting trend: investors are betting against homebuilders and in favor of landlords who collect rent from people who cannot yet afford to buy. 

What Buyers Need to Know Through Year-End 

For anyone trying to make sense of the US home prices hit an all-time high in July 2026 as existing home sales slow, mortgage rates rise, and the narrative dominating this week’s headlines, the practical takeaway is clear: don’t wait for a dramatic reversal. The Federal Reserve, under new Chair Kevin Warsh, has signaled it will likely hold rates steady through the rest of 2026, and inflation running above target limits how much room the central bank has to cut even if it wanted to. Realtor.com’s midyear forecast trimmed the full-year existing-home sales projection to just 4.1 million units, a scant 1% gain over 2025, while expecting price growth to actually lag inflation for the remainder of the year. 

That last point matters more than it sounds. Prices rising slower than inflation is, in real terms, a form of cooling — just not the kind that shows up in a headline about record nominal prices. For the US housing market, July 9, 2026: record prices, slowing sales, rising rates what buyers need to know. Conversation happening in living rooms and lender offices across the country: the honest answer is patience paired with realism: rates are unlikely to fall meaningfully before year-end, inventory will loosen only gradually, and the buyers who move now are effectively betting that waiting won’t actually make the math easier. 

The Road Ahead 

This market will not change quickly. The main reason for record prices is a long-term shortage of homes, caused by years of underbuilding, zoning rules that limit starter homes, and many owners who have no reason to sell. These are deep problems that cannot be fixed by a one rate cut or a single good sales report. Until more starter homes are built, expect to keep seeing the same story: prices rising, sales falling, and a growing gap between people who already own homes and those trying to buy their first. 

Source: U.S. home prices hit an all-time high as sales slow and mortgage rates rise 

Washington, D.C. | July 9, 2026 

Consumer borrowing did something it has not done since 2024: it shrank. Households pulled back by $0.2 billion in May, a sharp reversal from the $16.6 billion increase economists had penciled in, and that single data point landed one day after the FOMC minutes divided the Fed’s July 2026 narrative and seized hold of Wall Street. The Federal Reserve released the minutes from its June 16–17 meeting on Wednesday at 2:00 p.m. ET. The 14-page document confirmed what traders had suspected: the central bank is split in the direction of interest rates, and the disagreement is now a real issue. 

The committee voted unanimously, 12–0, to hold the federal funds rate steady at 3.50%-3.75%. That vote masked a much messier internal conversation. Some officials argued that the case for further tightening remained alive, citing inflation stubbornly above the Fed’s 2% target. Others countered that a softening labor market argued in favor of patience, if not an eventual cut. The result is a Federal Reserve inflation conflict that now defines the second half of 2026 for anyone trading rates, equities, or the dollar. 

A Fed That Cannot Agree on the Next Move. 

The minutes describe a committee split almost down the middle. A handful of participants said conditions justified raising rates at the June meeting itself, citing sticky core inflation and pass-through from tariffs and energy costs. They ultimately stood down and backed the hold. Others took the opposite view, warning that job growth has barely kept pace with the workforce and that further tightening risked tipping a cooling economy into contraction. Neither camp carried the room. The committee remains Fed rate hike divided heading into September, with no clear majority in either direction. 

Kevin Warsh, chairing his first FOMC gathering as Fed chairman, described the session afterward as a “family fight” that nonetheless produced a unanimous vote. Warsh’s first FOMC meeting minutes release also represented a shift in the Fed’s communication style. The post-meeting statement was cut to roughly a third of its usual length, and the minutes noted that most participants saw advantages in a shorter, less predictive public message. Investors accustomed to parsing every adjective in a Fed statement will need to adjust; forward guidance, for now, has been deliberately dialed back. 

The Neutral, Wait-and-See Posture 

Strip away the drama, and the document reveals something closer to institutional caution than institutional conviction. The FOMC minutes neutral wait-and-see Fed posture was evident throughout, with officials repeatedly framing their outlook in conditional terms rather than committing to a path. Participants generally agreed that economic activity remains solid, that productivity growth and capital investment are strong, and that unemployment has changed little. Where they diverged was what happens next, and that divergence is precisely why markets reacted the way they did. 

After the release, bond yields rose slightly while stock futures fell, showing real uncertainty rather than a clear bet by traders. Jeffrey Roach, chief economist at LPL Financial, pointed out that the minutes showed real ambiguity between the different groups. This is unusual for a central bank that usually aims for explicit communication. 

Inflation Risk Becomes the Core Contradiction 

The most consequential passage in the minutes concerns inflation expectations. Officials judged that price pressures would likely remain elevated in the near term before easing as the effects of tariffs, energy costs, and disruptions tied to the closure of the Strait of Hormuz gradually faded. Critically, the committee concluded that Fed upside inflation risks still outweigh the risks of undershooting the target. That single judgment is doing enormous work in the document, because it is the link connecting every hawkish argument inside the room. 

Spending on artificial intelligence infrastructure added a new complication. Participants noted that continuing demand for AI data centers will likely keep technology prices and electricity costs high. Warsh has said publicly that AI will eventually lower inflation as productivity improves, but this puts him at odds with colleagues who are more concerned about short-term price increases from energy-hungry data centers. 

FOMC June minutes: Fed divided on inflation risk; core conflict; some officials see rate hike needed in 2026 

This phrase sums up the main tension in the release. Some officials clearly said there was a case for raising rates in June, even though they ultimately supported a pause. They argued that if inflation is not addressed, it will become harder to control over time. Others were just as clear in warning that raising rates too soon, especially with a weakening job market, could cause lasting harm. Both sides looked at the same data but reached different conclusions, which is why the debate over a Fed rate hike versus cut in 2026 is now the key monetary policy question of the year. 

What the Data Since the Meeting Adds to the Picture 

Two new data points this week make things more complicated. Wholesale inventories rose by 0.1% in May, a small but positive sign that businesses are not rapidly reducing their stock ahead of a slowdown. Consumer credit, however, was more concerning. It fell by $0.2 billion in May, even though growth of about $16.6 billion was expected. This suggests households are borrowing less just as the Fed is debating if the economy can handle higher rates. Credit card balances fell at an annual rate of about 4.7%, while car and student loans kept growing. 

Adding geopolitics to economic data makes things even more uncertain. Oil prices jumped sharply on Thursday after new tensions in the Iran conflict cast doubt on the recent ceasefire that had calmed energy markets. For a Fed already concerned about rising inflation from energy costs, a new spike in oil prices is not a minor issue. It directly affects the same inflation debate that divided the committee in June. 

What FOMC minutes July 8, 2026, hawkish neutral Fed shift means for stock bond investors 

For investors trying to decide how to position themselves, the reality is that the Fed has removed one source of certainty without providing another. The shorter statements mean there is less advance guidance before each meeting. The divided minutes mean that every new inflation number, jobs report, and oil price change now have a bigger impact on the committee’s decisions. Stock markets, which expected a calm summer, may need to adjust to a Fed whose next moves are truly uncertain. 

The Road to September 

None of these has a simple solution. The Fed’s changes to communication suggest officials want more flexibility and less need to share their thinking in advance. This may help the committee work better internally, but it means markets have to do more of their own forecasting with less guidance than before. Every data release between now and September, from the July 14 CPI report to any new developments in the Strait of Hormuz, will show which side inside the Fed is gaining influence. The minutes did not resolve the debate; they just made it official.

Source: FOMC Minutes: Fed Shifts to Neutral Wait-and-See Stance, a Few Officials See Need to Raise Rates, Upside Inflation Risks Become Core Conflict