Washington, D.C. | July 15, 2026 

Grocery bills stopped climbing in June. Gas pumps stopped hurting. And for the first time in five months, the key number that affects mortgage rates, credit card interest, and the Federal Reserve’s decisions finally improved. The Bureau of Labor Statistics reported on Tuesday that June CPI 3.5 percent marked the softest annual inflation reading since January, a full 70 basis point below May’s scorched-earth 4.2% print. The result: inflation falls below 4 percent for the first time since the energy shock rattled markets earlier this year, and it did so by a wide enough margin that Wall Street’s models are already being rewritten. 

The main number was not the only surprise. News that the CPI beat estimates in July 2026 quickly spread across financial media, since economists surveyed by Dow Jones and LSEG expected an annual rate between 3.8% and 3.9%. The actual result of 3.5% was about 30 to 40 basis points lower than expected, depending on the survey. This difference is important because it gives the Federal Reserve more flexibility, instead of feeling pressured by stubbornly high prices. 

The Monthly Number That Rewrote the Narrative 

Annual inflation tells you where prices stand relative to a year ago. The monthly figure tells you what is happening right now, and June’s monthly reading did something markets had not seen since the early days of the pandemic. CPI June -0.4% month-on-month was the headline figure, a sharp reversal from May’s 0.5% monthly gain and the largest single-month decline since April 2020. Economists forecast a modest 0.1% to 0.2% monthly dip. Instead, the index fell twice that fast. 

The reason for the drop was clear. Energy prices, which had jumped earlier in the spring amid concerns about the Middle East, fell sharply in June. The energy index dropped 5.7% for the month, the biggest decline since April 2020, and gasoline prices alone fell 9.7%. This big drop in energy is more than made up for small increases in shelter (up 0.1%) and food (up 0.2%). For families, this meant that filling up the gas tank cost much less in June than in May, and this savings quickly showed up in the overall data. 

Why 30 Basis Points Matters More Than It Sounds 

A 30-basis-point miss might sound like a rounding error to anyone outside a trading desk, but in the world of interest rate futures, it is the difference between a Federal Reserve on offense and one on defense. A CPI gap of 30 basis points below the estimate is the kind of gap that moves bond yields within seconds of the release, and Tuesday was no exception. Treasury yields fell sharply after the report, and futures markets for the Fed’s September meeting shifted more toward keeping rates steady. The CME Group’s FedWatch tool showed the chance of a rate hike dropping from over 75% before the report to about 63% after the report, highlighting how much traders react to a single surprising data point. 

Core Inflation Tells an Even Cooler Story 

If you remove the often-changing food and energy prices, the numbers look even better. Core CPI was 2.59%, the lowest since February. This is the measure the Fed pays most attention to because it ignores short-term swings in gas and food prices. Economists expected core inflation to remain around 2.8% to 2.9% year-over-year, but it fell to its lowest level since February. This suggests that real price pressures, not just energy changes, are starting to ease. 

From May to June, core prices did not change, even though experts expected a 0.2% increase. Shelter costs, which are usually slow to change, rose only 0.1%, while transportation services fell 0.3%. These numbers do not suggest that inflation is becoming a long-term problem. Instead, they give policymakers a reason to relax a bit. 

LPL Financial Reads the Fine Print 

Not everyone is ready to celebrate, and that caution is important. Jeffrey Roach, chief economist at LPL Financial, gave one of the most closely watched responses to Tuesday’s release, and his framing expresses the tension running across markets this week. The LPL Financial inflation outlook credits the improvement largely to the sharp pullback in energy prices rather than a broad-based cooling across the economy, and Roach flagged that oil’s recent climb back above $82 a barrel could reverse the trend as soon as next month’s report. Still, his read on the Fed’s near-term posture was unambiguous: “After today’s benign core inflation release, it appears less likely that the FOMC will raise rates over the next few meetings.” 

This warning is important because the same factors that lowered energy prices in June, like a temporary ceasefire between the U.S. and Iran, are already under pressure. On the day the CPI report came out, Brent crude oil rose to a one-month high above $86 a barrel after new concerns about a possible military blockade in the Strait of Hormuz. Goldman Sachs analysts warned that if the conflict gets worse again, the risk of higher inflation could return quickly. In simple terms, this is likely just a short break, not a permanent fix. 

What It Means for Borrowers, Investors, and the Fed 

If you were looking up June CPI falls 3.5%, beats estimates by 30 bps, and inflation eases on Tuesday, here’s what matters: The Federal Reserve, which has kept its main rate between 3.50% and 3.75% for four meetings in a row, now has more flexibility for its next decision. Lower-than-expected inflation does not mean a rate cut is certain, but it makes a rate hike much less likely and gives policymakers more time to review new data before making a move. 

Stock futures rose quickly after Tuesday’s report, and Treasury yields dropped as traders adjusted their expectations for the Fed’s next move. If this softer trend continues through July and August, mortgage rates, credit card interest rates, and auto loan costs—which all follow Treasury yields to some extent—could also decline. If you are following the phrase CPI June 2026 core 2.59% Fed rate hike hold September outlook, keep an eye on two things: whether rising oil prices affect the July CPI report, and whether Fed officials, including new Chairman Kevin Warsh, are willing to wait for more than one month of good data before making changes. 

A Reprieve, not a Resolution 

June’s inflation report finally gave the economy some good news after months of tough data. Whether this leads to lasting relief or is just a one-time result from a pause in the Iran conflict relies on factors the Fed cannot control. Oil prices, stability in the Strait of Hormuz, and how quickly shelter costs rise will all have a bigger impact on July’s report than any single policy decision in Washington. For now, families get a small break on gas and groceries, and the Federal Reserve gets the chance to wait and see.

Source: CPI fell More Than Expected 
New York, New York | July 13, 2026 

Wall Street rarely rewards companies that raise prices during a soft consumer spending cycle. Yet Apple continues to challenge that assumption. As inflation pressures, component shortages, and prudent consumer demand weigh the wider electronics market, analysts increasingly believe Apple’s premium positioning gives it an advantage that few competitors can match. That belief sits at the center of Citi’s Apple price target of $365, a new bullish outlook that argues Apple’s pricing strategy remains one of its strongest competitive assets. 

Citi’s latest research notes also upgraded AAPL stock upgrade Monday, reinforcing growing confidence that Apple’s pricing power in 2026 remains intact despite macroeconomic uncertainty and higher production costs. 

Citi Apple price target $365 Exhibits Confidence in Apple’s Premium Strategy 

Citi raised its Apple price target from $315 to $365 per share, which is about 16% higher than Friday’s closing price. Citi is now the second big Wall Street firm this week to raise its outlook for Apple, following JPMorgan’s increase to $345. 

The latest projection, described as Citi AAPL $365 from $315, with 16 percent upside, reflects a broader investment thesis rather than an expectation of a single product launch. Analysts increasingly believe Apple’s ecosystem, customer loyalty, and expanding Services businesses allow the company to handle economic slowdowns more effectively than rivals. 

Citi analyst Asiya Merchant said Apple stands out because it can raise prices without losing much demand. While other electronics companies often cut profits to keep sales up, Apple has kept its margins strong thanks to careful pricing and a strong brand. 

Merchant also pointed out that Apple’s customers care more about how well their devices work together, software support, and long-term value than about short-term price changes. 

Apple’s Pricing Power Continues to Surprise Wall Street 

The clearest sign of Apple’s pricing power in 2026 came in late June, when the company raised prices on several Mac and iPad models. 

These price hikes ranged from about 15% to over 50%, depending on the model. Instead of worrying about lower demand, most investors saw the increases as a necessary response to higher memory costs driven by increased spending on artificial intelligence infrastructure. 

This trend supports the investment case for Apple’s market share memory price hike. Industry-wide DRAM shortages have significantly increased component costs, yet Apple appears positioned to pass much of those expenses directly to consumers. 

When component prices go up, most hardware makers have to choose between taking a hit to profits and raising prices, which could cost them customers. Apple, though, has shown that many of its customers are still willing to pay higher prices. 

This advantage is especially important when supply chains are disrupted. 

AAPL stock upgrade Monday Highlights Analyst Consensus 

The recent AAPL stock upgrade on Monday shows that more analysts are agreeing, not just one firm. 

In the past few weeks, several investment banks have pointed out the same trends. 

Analysts identify several structural advantages: 

  • Apple’s unmatched brand loyalty. 
  • A growing installed device base. 
  • High-margin Services revenue. 
  • Premium product positioning. 
  • Strong cash generation. 

All these factors help make Apple’s earnings more stable than those of many other tech companies. 

With Citi’s new target and JPMorgan’s earlier upgrade, it looks like big investors expect Apple to do better than other hardware makers in the coming months. 

Why Apple loyal customer pricing analyst Monday Matters 

Apple’s brand loyalty is one of its biggest strengths, even if it doesn’t show up on the balance sheet. 

The latest research surrounding Apple loyal customer pricing analyst Monday argues that customer retention allows Apple to maintain pricing discipline during difficult economic circumstances. 

Consider a hypothetical example. 

Someone who uses an iPhone, Apple Watch, AirPods, MacBook, iCloud, Apple Music, and Apple Pay faces real challenges if they switch brands. Changing one device can cause problems with how everything works together. 

This ecosystem gives Apple more flexibility in determining prices. 

People might postpone buying gadgets from other brands, but many still upgrade their Apple devices to keep their digital experience smooth. 

This loyalty helps Apple keep its prices steady, while other companies often have to offer discounts. 

Services Revenue Strengthens the Investment Case 

Most Apple’s revenue still comes from hardware, but its Services business is changing the company’s finances. 

Services revenue has grown by about 15% each year, giving Apple a steadier income that doesn’t depend on iPhone upgrades. 

Services like Apple Music, iCloud+, Apple TV+, AppleCare, Apple Pay, App Store fees, and financial products bring in steady income with much higher profit margins than hardware. 

Having a mix of services and products makes Apple’s earnings less likely to swing wildly. 

For investors looking at Apple’s pricing power in 2026, Services are just as important, since subscriptions bring steady income even if hardware sales change. 

Wall Street now sees Apple as more than just a smartphone maker. It’s viewed as a company with a whole ecosystem and several steady sources of income. 

AI Features Could Become Apple’s Next Growth Driver 

Another reason for Citi’s positive outlook is Apple’s plan for artificial intelligence. 

After its announcements at WWDC, Apple is adding AI features to the iPhone, iPad, Mac, and Vision platforms. 

Instead of just focusing on AI chatbots, Apple is putting more effort into on-device intelligence, privacy, and making sure AI works smoothly with its operating systems. 

Investors will watch upcoming software updates to see if these AI features lead people to upgrade their devices more often. 

If Apple’s AI features make users more productive without hurting privacy, analysts think more people will want to upgrade during the next hardware cycle. 

This could boost Apple’s long-term earnings, not just its current pricing outlook. 

Comprehending the Long-Term Bullish Thesis 

The case for investing in Apple is about more than just higher device prices. 

Supporters think Apple’s strengths build on each other. 

Higher prices support margins. 

Healthy margins, finance research, and development. 

Innovation builds customer loyalty. 

Customer loyalty supports future pricing flexibility. 

Recurring Services revenue provides steadiness throughout the cycle. 

All these factors come together to make Apple’s business model especially strong, even when the economy changes. 

This thinking appears throughout Citi: raises Apple price target to $365 from $315 pricing power memory hike, where pricing flexibility offsets higher component costs while preserving profitability. 

Likewise, the research notes titled Citi Apple AAPL upgrade Monday July 11, 2026, Asiya Merchant analyst note emphasizes that Apple’s premium positioning allows selective price increases without materially weakening demand. 

Risks Investors Should Monitor 

Even with all optimism, Apple still faces some real risks. 

If the economy gets worse, people might cut back on spending even more than expected. 

Continuing supply chain problems could keep raising production costs. 

Regulators are still monitoring Apple’s App Store and online marketplace practices in several countries, which remains a concern. 

Competition from Android makers is also getting tougher, especially in countries where people are more price sensitive. 

Artificial intelligence is another factor. Apple needs to show that its AI investments actually drive increased customer demand, not just minor software upgrades. 

Still, many analysts think these risks are manageable because Apple’s strong finances, global brands, and ecosystems provide significant protection. 

Outlook for Apple Shares 

Now, investors are focusing on Apple’s impending earnings, new AI software releases, and the holiday shopping season. 

If Services revenue continues to grow in the double digits and Apple maintains its premium pricing, Wall Street may raise its profit forecasts again. 

Strong profit margins, steady subscription income, growing AI features, and loyal customers all help keep Apple’s stock price high. Citi’s new target shows that Apple has a rare ability in tech: it can charge more and still keep demand strong. If the next earnings report supports this, Apple’s pricing strategy could be as valuable to investors as its newest products. 

Source: Veteran Bank Tweaks Apple Stock Price Target Ahead of Phone 18 Launch 

Biddeford, Maine | July 13, 2026 

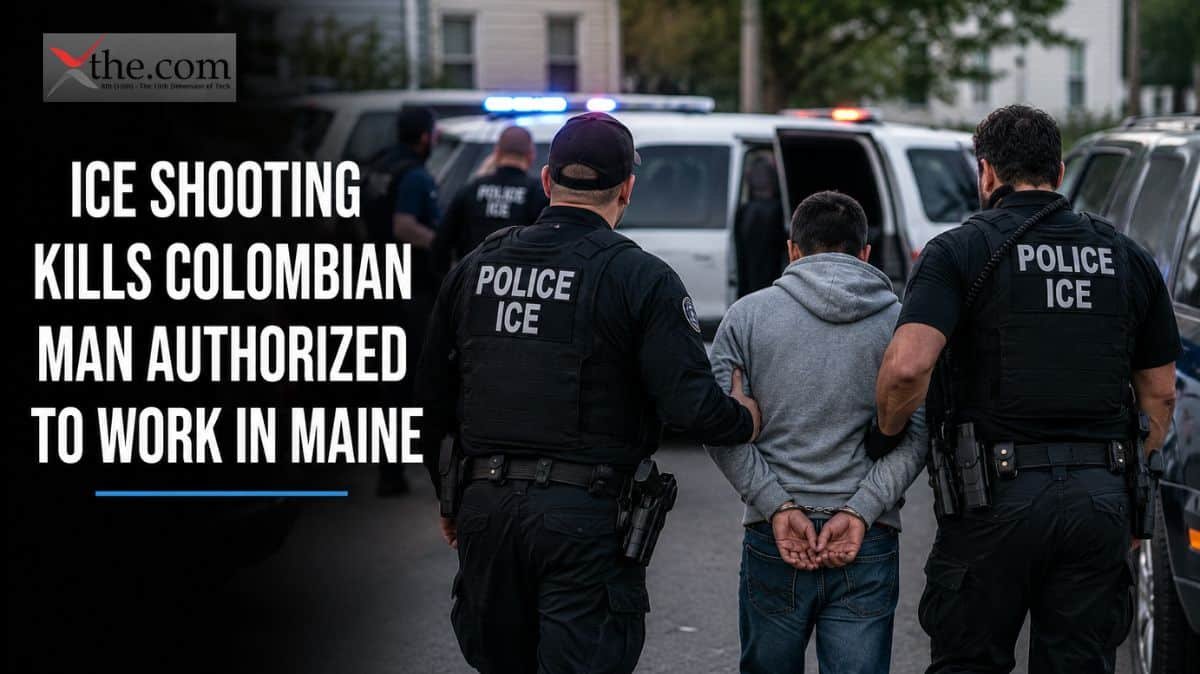
Just a few seconds can shift a national conversation. In Biddeford, Maine, a deadly encounter with federal immigration officers has triggered issues about accountability, use of force, and how legally authorized immigrant workers are treated. Elected officials and civil rights groups are now carefully watching this case, making it one of the year’s most high-profile immigration enforcement incidents. 

The ICE shooting in Maine in 2026, described by witnesses and advocacy groups as a deeply troubling encounter, has placed federal immigration enforcement actions under renewed examination. The Biddeford ICE killing has also heightened calls for transparency, which have grown after immigrant advocates said the victim was a Colombian national legally allowed to work in the United States. Reports identifying the victim as a Colombian man ICE shot in Maine have spread rapidly across national media, leading to demands for an independent federal investigation. 

ICE Shooting in Maine 2026 Raises Issues About Compliance Methods 

According to the Biddeford Police Department, officers responded Monday morning to an incident near the intersection involved in the ICE Biddeford Maine Pool Hill streets shooting. Local police secured the scene and directed all questions regarding the investigation to U.S. Immigration and Customs Enforcement (ICE), indicating that federal personnel were responsible for the operation. 

Photos from the Portland Press Herald show a Kia sedan with four bullet holes in its windshield, showing how intense the confrontation had been. Authorities have not yet shared a thorough timeline of what happened right before officers fired their weapons. 

The shortage of immediate official details has raised public concern. When federal officers use deadly force, transparency is almost as important as the facts. In the absence of clear explanations, speculation can spread, so timely updates are important for maintaining citizen confidence. 

Victim Identified as Authorized Worker 

Immigrant advocacy organizations have identified the victim as a 26-year-old Colombian citizen who had legal authorization to work in the United States. 

The Maine Immigrant Rights Coalition Colombian worker statement said the individual possessed valid work authorization and had been issued a Social Security number. Project Relief Maine echoed that assessment, stating through social media that the victim had permission to work legally in the country. 

These statements have shifted public conversation about the case. Now, instead of only looking at immigration enforcement, critics are asking if federal officers could tell the difference between undocumented people and immigrants who are legally working in the U.S. 

As a result, the phrase ‘ICE shooting authorized worker Social Security’ has become a key part of the debate. It shows broader concerns about how immigration enforcement intersects with the federal systems that handle work authorization. 

The Incident That Sparked National Attention 

Although investigators have not yet released a comprehensive sequence of events, the fatal shooting reportedly occurred during an ICE operation in Biddeford. 

The Maine ICE incident in July immediately attracted attention from state lawmakers, immigrant rights groups, and Democratic governors nationwide. Many have asked the Department of Homeland Security’s Office of Inspector General and the Department of Justice to do independent reviews in addition to ICE’s own investigation. 

Advocates say that citizen trust needs more than just an internal review when deadly force leads to someone’s death. 

The reported legal status of the victim distinguishes this case from many previous immigration enforcement controversies. 

Advocacy groups say the victim had work authorization recognized by federal authorities. This means he had finished parts of the immigration process that allowed legal employment and had the documents needed to get a Social Security number. 

The long-tail search phrase ICE shooting kills Colombian authorized work visa Maine Biddeford July 2026 captures the central issue dominating public discussion: whether immigration officers appropriately handled an encounter involving someone legally permitted to live and work in the United States. 

Another frequently searched phrase, Maine ICE shooting 26-year-old Colombian worker Social Security number killed, reflects widespread interest in understanding how such an encounter might occur despite documented work authorization. 

Federal authorities have not said if officers knew the person’s immigration status before the shooting or if they learned it only afterward. 

What Rules Govern ICE’s Use of Deadly Force? 

Federal law enforcement officers operate under established use-of-force policies developed to balance officer safety with constitutional protections. 

ICE personnel generally receive training requiring officers to employ objectively reasonable force based on the circumstances they confront. Deadly force is authorized only when officers reasonably believe they face an imminent threat of death or serious bodily injury to themselves or another person. 

Investigators typically examine a number of factors, including whether officers attempted verbal commands, whether less-lethal alternatives were available, the immediacy of any perceived threat, available body-camera or surveillance footage, witness testimony, forensic evidence, and communication among responding officers. 

These reviews often include several agencies and can take weeks or months before final results are shared. 

Political Fallout Intensifies 

The Biddeford ICE killing has quickly grown from a local criminal case into a national political issue. 

Civil rights organizations contend that every fatal federal enforcement action deserves independent oversight. Immigration advocates contend that incidents involving documented workers require particularly careful examination because they may expose weaknesses in communication between immigration databases, field operations, and officer decision-making. 

Several elected officials have asked for more clarity about how operations are planned, how information is gathered, and how incidents are reported afterward. 

Supporters of federal immigration enforcement say investigators should gather all the facts before judging officer’s actions. They point out that use-of-force decisions are made in seconds under stress and should be reviewed with all the evidence, not just early public accounts. 

Why This Case Matters Beyond Maine 

The ICE shooting in Maine 2026 touches multiple policy debates simultaneously. 

Immigration enforcement remains one of the most debated issues in the U.S. Cases involving people with legal work authorization raise additional legal questions, since they challenge ideas about who can be targeted by enforcement. 

The reported status of the Colombian man ICE shot in Maine has therefore intensified discussions about information sharing among federal agencies responsible for immigration documentation, employment verification, and enforcement. 

Experts say that mistakes involving legally authorized workers can weaken trust in federal systems designed to distinguish between different immigration categories. 

Law enforcement professionals also point out that legal immigration status does not always decide how officers react in fast-changing situations. Investigations need to determine exactly what officers saw, what they knew, and whether their actions complied with the law and agency rules. 

Investigation Expected to Continue 

Federal investigators are now under strong public pressure to answer some key questions. 

What initiated the encounter? Did officers identify themselves? What level of threat did they perceive? Were body cameras operating? Were de-escalation measures attempted? What role, if any, did the victim’s employment authorization play during the encounter? 

How those questions are answered will likely decide if the ICE Biddeford, Maine, Pool Hill Street shooting is seen as justified, a failure in operations, or a cause for bigger changes in immigration enforcement. 

The results could also shape future talks about officer training, transparency, independent oversight, and how officers handle encounters with people legally allowed to work in the U.S. 

The Maine ICE incident in July has already turned into more than just a local tragedy. It has become a national test of how federal authorities investigate the use of deadly force, share information with the public, and balance immigration enforcement with constitutional rights. As investigators collect evidence and officials respond to public concern, the results will likely shape future discussions about accountability, citizen trust, and the rules governing federal law enforcement across the country.

Source: Man fatally shot by ICE officer in Maine wasn’t the target of arrest warrant, senator’s spokesman says 

Toronto, Canada | July 12, 2026 

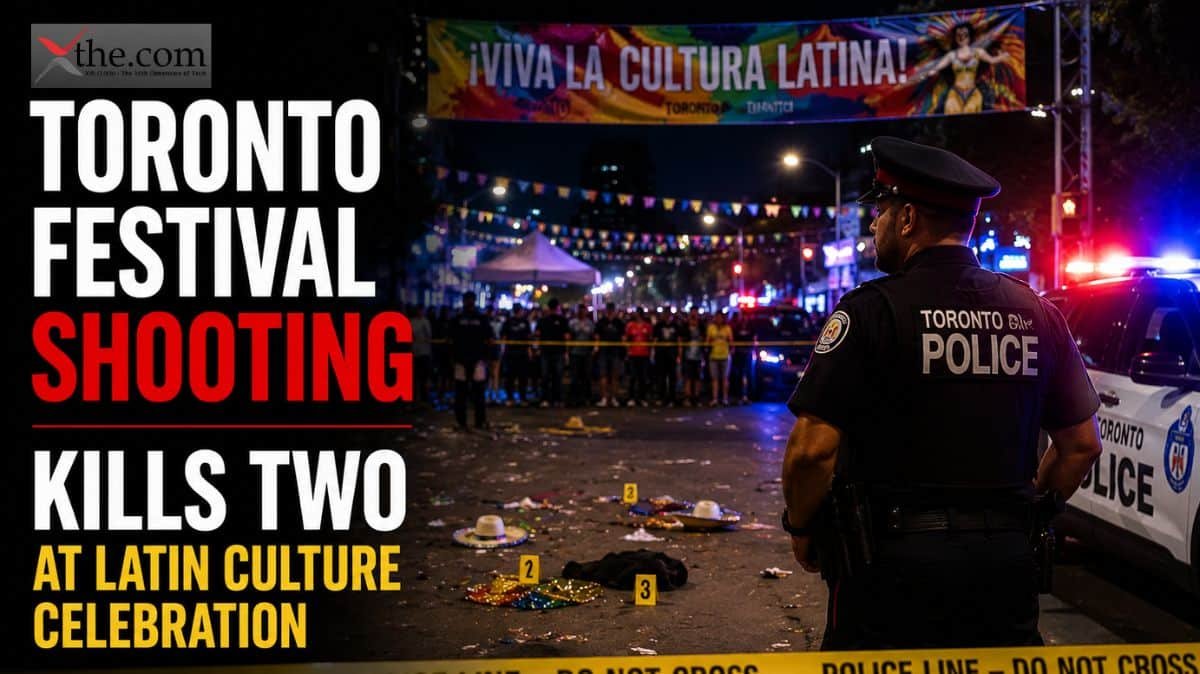
What started as a summer festival celebrating music, dance, and community quickly turned tragic. Families ran for safety, performers left the stage, and emergency crews rushed in as alarm spread through one of Toronto’s biggest cultural events. The Toronto festival shooting has brought up tough questions about public safety, cross-border gun trafficking, and how to keep large gatherings safe in Canada’s largest city. The Salsa St. Clair shooting in Toronto, now one of the city’s deadliest festival attacks this year, also marks another grim chapter in the Toronto mass shooting on July 11, deeply touching both residents and the Latin community. 

Toronto Festival Shooting 2026 Leaves Two Dead and Several Injured. 

Authorities confirmed that two people were killed and at least four others suffered injuries after shots were fired Saturday night during the annual Salsa on St. Clair Festival in Toronto. 

Every year, tens of thousands of people come together at this event to celebrate Latin American culture with live music, dance, and traditional food. Witnesses said the night was full of joy until gunshots suddenly broke out, forcing thousands to run for safety. 

Police officers who were already at the event responded right away, with tactical teams and paramedics arriving soon after. Emergency crews established a safe area while investigators searched for evidence and interviewed witnesses. 

People now refer to the tragedy as the Salsa on St. Clair Toronto shooting, two dead, pointing to the devastating impact on a festival that has been one of Toronto’s main multicultural celebrations for years. 

Timeline of the Shooting 

Investigators believe the shooting occurred during one of the busiest periods of the evening, when crowds packed the main festival corridor. 

According to witnesses, several gunshots were fired quickly one after another. At first, people thought the sounds were fireworks but panic soon rushed through the crowd. 

Officers immediately instructed people to seek cover while emergency medical teams treated victims at the scene, then transported the injured to nearby hospitals. 

Authorities have not yet confirmed the exact number of rounds fired or publicly identified all victims pending notification of family members. 

Police are still gathering videos from local businesses, city cameras, and festivalgoers’ phones to piece together what happened. 

The case is also being investigated as the Toronto festival gunfire on July 11, with multiple injuries, as police look into whether more people were hurt while escaping the crowded event. 

The Investigation Concentrates on the Suspect and Possible Motive. 

Toronto Police have not released complete details regarding the suspect or suspects involved. 

Police are still trying to find out if the attack was directed at someone specific or if bystanders were caught in random gunfire. Detectives are talking to many witnesses, while crime lab teams examine shell casings, ballistic evidence, and nearby video footage. 

Officials have urged members of the public who attended the festival to provide photographs, videos, or eyewitness information that could help identify everyone involved. 

The investigation is ongoing, and police have asked the public not to speculate as they review the evidence. 

The response from Canada festival violence Toronto police has emphasized transparency during the investigation while reassuring residents that significant investigative resources have been assigned to the case. 

Toronto Faces Another Test Amid Mounting Gun Violence. 

This shooting happened during a year when Toronto has faced repeated gun violence. 

Canada’s firearm homicide rates are still much lower than those in the United States, but Toronto officials say that several high-profile shootings in 2026 have put more pressure on police resources. 

Community leaders have often asked for better violence prevention programs and smarter policing approaches. Police say that fighting organized crime, illegal gun trafficking, and repeat offenders needs teamwork between city, provincial, and federal agencies. 

The shooting at the Latin festival in Toronto has triggered more debate about whether extra security should be standard at big outdoor events. 

People are also worried about public safety. Many now want to see more police at events, but they also hope for community programs that can stop violence before it happens. 

Cross-Border Firearm Trafficking Returns to the Spotlight. 

Investigators are also trying to find out where the gun or guns used in the shooting came from. 

Canadian police say that many crime guns found in big investigations come from illegal trafficking networks linked to the United States. Smugglers use the long Canada-U.S. border to move handguns and other firearms through organized crime groups. 

If tests show the gun was trafficked, the investigation could grow to include federal agencies that handle organized crime and border security. 

Officials say that stopping illegal gun trafficking needs Canadian and American authorities to share information and work together on enforcement against cross-border crime groups. 

Investigators have not confirmed where the weapon came from in this case, but cross-border trafficking is always a major focus after big shootings in Canadian cities. 

Latin Community Mourns a Celebration-Turned-Tragedy. 

The emotional toll reaches far beyond just those who were hurt. 

For Toronto’s Latin American community, Salsa on St. Clair is much more than a music festival. It’s a yearly observance of heritage, identity, business, and family traditions. 

Community groups shared their sadness but urged people not to let violence overshadow an event meant to celebrate culture and inclusion. 

Many vendors, performers, and volunteers said they were in shock as the joyful celebration turned into panic within moments. 

Religious leaders and community advocates have planned vigils to honor the victims and are giving support to witnesses, families, and first responders dealing with trauma. 

This tragedy has also sparked new discussions about how to keep people safe while preserving the welcoming spirit that makes Toronto’s multicultural festivals famous worldwide. 

Security implications for future public events 

City officials are now under more pressure to review security plans for big outdoor events. 

Future festivals might have increased surveillance, additional entry checkpoints, more visible police presence, improved emergency communication, and closer teamwork between organizers and emergency crews. 

Security experts state that no public event can be completely safe. Good planning means using several layers of security, including gathering information, maintaining visible deterrents, ensuring a quick emergency response, and keeping the community informed. 

After the Toronto shooting, festival organizers across Canada will likely review their emergency plans, especially for big summer events. 

What authorities know so far 

Investigators continue working to establish every detail surrounding the attack. 

Authorities have confirmed two deaths and at least four injuries. Detectives are still looking at forensic evidence, talking to witnesses, checking video footage, and tracing the gun used. Officials have not yet shared full details about the suspect or motive, since the investigation is still ongoing. 

People now refer to the tragedy with expressions such as “Toronto Salsa on St Clair festival shooting kills two July 11 2026” and “Toronto festival Latin culture shooting two dead four injured police respond. This shows how much public attention the event has received and the strong effect it has had on one of Canada’s most famous multicultural festivals. 

A city searching for answers 

Toronto has built an international reputation as one of North America’s most diverse and welcoming cities, and its public festivals serve as symbols of that identity. The Toronto festival shooting 2026 challenges this reputation and draws attention to the need for better violence prevention, smarter information sharing, and strong community partnerships. As investigators try to find out exactly what happened at the Salsa St. Clair shooting in Toronto, the city must likewise confront broader questions surrounding illegal firearms, public safety, and trust. How Toronto responds after the Toronto mass shooting on July 11 may influence not just future festival security, but also Canada’s overall approach to stopping gun violence while keeping its public spaces open and welcoming.

Source: 2 dead, 6 injured at Toronto festival after pair of gunmen shoot at each other 

New York, New York  

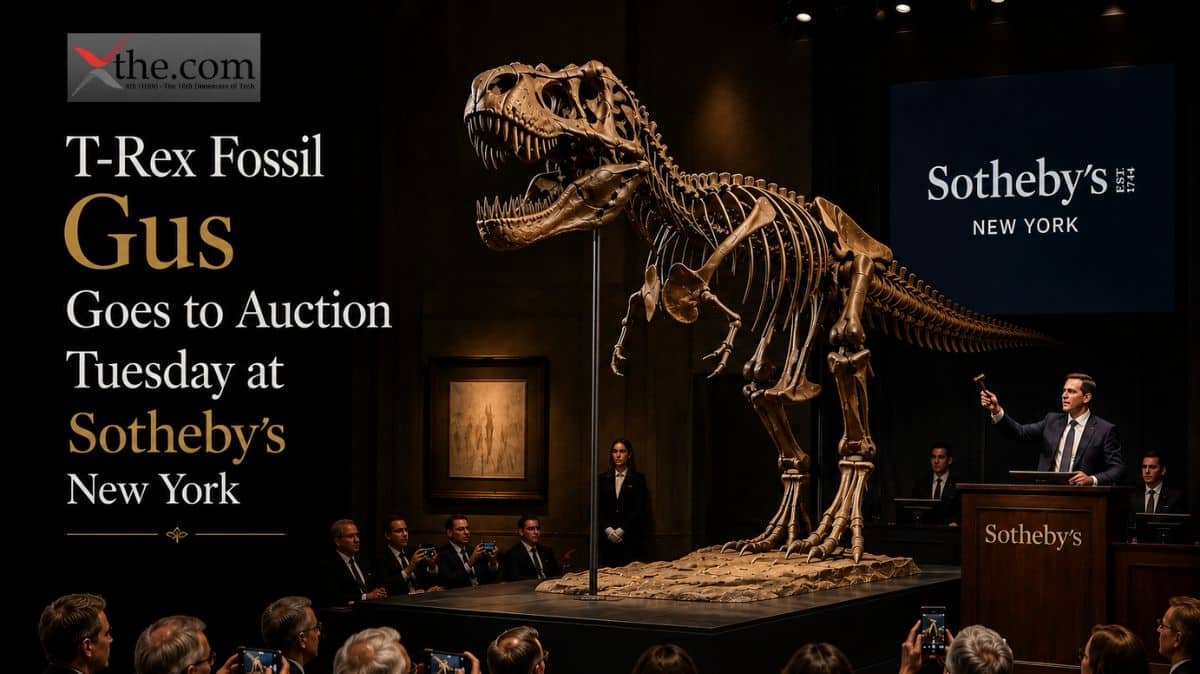
A dinosaur skeleton can sell for as much as a luxury penthouse, but the biggest loss might not show up on any auction bill. When important fossils end up in private collections, scientists can miss out on years of research. This issue is at the heart of the T-Rex Gus auction at Sotheby’s in 2026, where one of the largest Tyrannosaurus rex skeletons will be sold in New York. The T-Rex fossil July 2026 sale also shows how dinosaur-bone auction events have evolved into multimillion-dollar events that attract billionaires, museums, and investors from around the world. (KRDO) 

T-Rex Gus auction Sotheby’s 2026 Draws Global Attention. 

For Sotheby’s, bringing in Gus is more than just another big natural history sale. It shows how prehistoric fossils are now seen as valuable collectibles, much like famous art or rare gems. 

Gus, as the Tyrannosaurus rex is called, lived about 67 million years ago in the Late Cretaceous Period. The skeleton is about 38 feet long and stands over 12 feet tall when assembled, making it one of the largest T. rex skeletons ever found. Sotheby’s says the fossil is about 61% complete by bone count, a rare level of preservation that enhances its scientific and commercial value. The skeleton was found in South Dakota’s Hell Creek Formation, a site famous for its T. rex fossils. (Sothebys.com) 

The fossil is named after Gary “Gus” Licking, a rancher from South Dakota who spotted it by chance on his land. Although Licking passed away before the excavation was finished, his name is now linked to one of the most valuable finds in paleontology. (KRDO) 

The Gus Tyrannosaurus rex Sotheby’s Tuesday sale arrives after weeks of public exhibition at Sotheby’s New York galleries, giving visitors a chance to see the mounted skeleton before bidding began. 

A Fossil with an Extraordinary Price Tag 

Sotheby’s expects Gus to sell for between $20 million and $30 million. Even before live bidding started, someone had already offered about $19 million, showing strong interest in the market. If the final price goes higher, Gus could become one of the most valuable dinosaur fossils ever sold in public. (Sothebys.com) 

This high price estimate is why so many collectors, investors, and science fans are searching for expressions like “T-Rex fossil Gus Sotheby’s auction Tuesday July 2026 price expected” as they follow the auction. 

In contrast to smaller fossil sales that usually draw local museums, the sale of Gus is a global event. Experts expect tech entrepreneurs, international collectors, private museums, and family offices to join the bidding for this museum-quality fossil. Wealth funds interested in cultural collections are also likely to bid, showing that dinosaur skeletons are now seen as investments, much like fine art. 

Why Dinosaur Fossils Have Become Luxury Assets 

Very few Tyrannosaurus rex skeletons are complete enough to sell for more than $10 million. 

This rarity has completely changed the market. 

The big shift happened in 2020, when another famous T. rex called Stan sold for $31.8 million. Four years later, a Stegosaurus named Apex broke records by selling for $44.6 million. These sales show that top fossil auctions are now global luxury events, not just small scientific deals. (Wikipedia) 

Each record-breaking sale has made investors more confident. 

Collectors now see rare fossils as one-of-a-kind assets. Unlike paintings which artists can make throughout their lives, a 67-million-year-old T. rex can never be replaced. With so few available, high demand, and rising cultural status, prices keep going up. 

This trend explains why dinosaur-bone auction headlines now appear in financial publications alongside reports on art markets and luxury collectibles. 

Scientific Research Meets Commercial Demand 

Despite commercial enthusiasm, the T-Rex fossil auction controversy has heightened every multimillion-dollar sale. 

Many paleontologists believe that fossils with great research value should be in museums, not private collections. When a collector buys a fossil, scientists often lose their chance to study it, take new images, or examine its features again as technology improves. 

This issue goes beyond simply academic interest. 

Today’s paleontologists use advanced CT scans, chemical tests, microscopic bone studies, and digital reconstructions that can lead to new discoveries long after a fossil is found. If scientists lose access, future research opportunities may be lost too. (KRDO) 

This concern has fueled ongoing debate over dinosaur fossil private sale scientific access, with many researchers advocating stronger regulations governing the sale of scientifically significant specimens. 

Others argue that without private money, many fossils would never be found, preserved, or properly prepared. Digging up fossils can take years and cost millions, which public institutions often can’t afford. 

This creates a tough balance between protecting scientific knowledge and respecting private property rights, especially when fossils are found on private land, as Gus’s were. 

The Expanding Debate Over Private Ownership 

The debate about Gus goes well beyond just one auction. It raises bigger questions about who should own parts of Earth’s natural history and who should gain their research value. 

People who support private ownership say the fossil market has saved many specimens that might have been lost or destroyed before scientists found them. Commercial fossil hunters often spend a lot on finding, excavating, transporting, and restoring fossils. Without their investment, many fossils might never make it to museums, universities, or public displays. 

Critics say that very rare fossils are different. A nearly complete Tyrannosaurus rex skeleton can teach us about anatomy, movement, growth, disease, injuries, and evolution in ways that are hard to replace. If an important fossil ends up in a private collection with limited access, scientists might miss opportunities to answer new questions as technology advances. 

This disagreement has shaped the T-Rex fossil auction controversy, which has accompanied nearly every big dinosaur auction in the last ten years. 

Why Provenance Matters 

Unlike many fossils sold with little background, Gus has a clear and well-documented history. The skeleton was found in the Hell Creek Formation in South Dakota, a site known for some of the world’s most important Late Cretaceous fossils. Experts carefully excavated and prepared Gus, which helps to prove its authenticity and scientific value. 

For buyers, a fossil’s history directly affects its value. Complete records, proof of ownership, and expert care make people more confident that the specimen is real and important. 

For scientists, a fossil’s background is just as important. Knowing the exact rock layer, nearby sediment, and other fossils helps researchers’ piece together ancient habitats and learn how Tyrannosaurus rex lived, hunted, and changed over time. 

A Market Defined by Record-Breaking Sales 

The commercial fossil market has changed a lot since Stan the Tyrannosaurus rex sold for $31.8 million in 2020. That sale showed that dinosaur fossils are now seen as luxury items, drawing the same kind of competition as fine art auctions. 

Since then, auction houses have expanded their natural history offerings, seeing that wealthy collectors want unique, museum-quality pieces. The Sotheby’s July 15 T-Rex auction shows this trend, with bidders from around the world now viewing rare fossils as cultural investments rather than just collectibles. International business leaders, private museums, and family offices now compete alongside traditional natural history collectors. Some buyers loan purchased fossils to museums for public display, while others retain them within private collections. 

One of the biggest questions is whether Gus will end up in a public institution or stay hidden in a private collection. 

The Scientific Stakes 

The phrase “Tyrannosaurus rex Gus fossil auction private sale scientific debate” sums up the main issue facing paleontology today. 

Every major fossil sale forces researchers to balance different priorities. 

On one hand, landowners and commercial diggers have a real right to earn money from finds on their property. Those financial rewards often lead to careful excavation and preservation that might not otherwise occur. 

On the other hand, scientists are committed to open research. Museum collections allow many generations of researchers to study fossils with increasingly sophisticated tools. New methods like CT scans, isotope analysis, AI reconstruction, and bone studies keep revealing things scientists couldn’t have found just ten years ago. 

A fossil kept in a private collection might stay in great shape, but its value to science could be much more limited. 

This tension explains why discussions related to dinosaur fossil private sale scientific access continue to intensify as auction prices climb. 

Could Gus Set Another Benchmark? 

Experts expect strong international bidding, but it’s unclear whether Gus will break previous records. Sotheby’s says the fossil is one of the most valuable ever offered, and early interest shows there will be tough competition. 

People searching for “T-Rex fossil Gus Sotheby’s auction Tuesday July 2026 price expected” show how much excitement there is. Investors, museum staff, teachers, and dinosaur fans are all watching to see if a new record will change what people expect from the fossil market. 

No matter what the final price is, the T-Rex fossil July 2026 sale has already made an impact. It has sparked renewed public interest in paleontology and raised tough questions about ownership, preservation, and scientific responsibility. 

Looking Beyond the Auction 

The T-Rex Gus auction at Sotheby’s in 2026 is about more than just selling an ancient predator. It shows how natural history is now linked with global finance, private collecting, and cultural status. Each new record sale boosts the commercial value of rare fossils, but every private purchase also raises worries about long-term access for science. 

The real challenge facing policymakers, museums, collectors, and researchers isn’t just about who can buy these amazing fossils. It’s about finding ways to encourage investigation while ensuring important fossils remain available for future generations to study. Gus may soon have a new owner, but the questions from this auction will keep shaping paleontology long after the sale is over.

Source: A T. rex found in South Dakota could smash auction records — and possibly disappear forever 

Los Gatos, California  

Two of the world’s most closely watched tech companies will report earnings on the same afternoon this week, and their stories are closely linked. Netflix’s Q2 earnings for July 2026 land Thursday, July 16, just hours before Taiwan Semiconductor Manufacturing Company shares its own results. This schedule makes July 16 the most AI-focused earnings day of the year. TSMC makes the chips that power AI models, while Netflix shows what happens when those models are used in a media business earning tens of billions of dollars in annual revenue. Investors watching NFLX earnings Thursday are no longer simply asking how many people signed up last quarter. They want to know how artificial intelligence is changing Netflix’s production costs, advertising strategies, and subscriber retention. 

Netflix will announce its results after the market closes at about 1:01 p.m. Pacific time, followed by a live video interview with co-CEOs Ted Sarandos and Greg Peters, and CFO Spence Neumann. Wall Street has set up a demanding bar. Analysts project revenue near $12.57 billion for the quarter, roughly 13.5% higher than a year earlier, alongside earnings per share of approximately $0.79, up from $0.66 in the same period last year. Those numbers alone would make for a routine earnings preview. What makes this print different is the scale of Netflix’s AI content spending for 2026, shown underneath the topline figures. 

The AI Production Story Behind the Numbers 

Over the past two quarters, Netflix has moved artificial intelligence from a side project to a key part of its production process. The company’s reported $600 million partnership with InterPositive Technologies, which specializes in AI-assisted post-production, is one of Netflix’s biggest deals, second only to its $700 million purchase of the Roald Dahl Story Company. InterPositive’s tools do not create new footage. Instead, they help editors fix continuity mistakes, remove unwanted objects, and smooth out scenes that would otherwise need reshoots. This difference is important for investors who want to see real cost savings, not just hype around generative AI. 

Netflix has also released VOID, its internal tool for physics-aware object removal in video, as an open source under an Apache 2.0 license. The company creates over 1,000 hours of original content annually, and even small per-hour reductions in visual-effects labor compound quickly at that volume. Netflix AI production content tools now touch scripting analysis, shot planning, visual-effects simulation, and the recommendation engine that forms what over 300 million households see when they use the app. Management expects content amortization to grow about 10% year over year in 2026, with most of the increase occurring in the first half of the year, unlike in 2025, when growth was focused in the fall. 

Subscriber Growth Without a Headline Number 

Here is where analysts face a genuine complication. Netflix stopped disclosing quarterly subscriber counts after the first quarter of 2026, a decision that shifts the market’s attention toward revenue per member and engagement hours instead of a single membership figure. Even without a hard number, Netflix Q2 2026 subscriber growth remains the quarter’s most-watched storyline, because it determines whether the password-sharing crackdown that boosted 2024 and 2025 results has fully played out. Paid memberships ended the first quarter above 325 million, and Netflix’s own estimates put penetration at under 45% of its addressable global household base, leaving room to grow even in mature markets like the United States and Canada. 

This quarter, retention data is more important than new sign-ups. Investors want to see whether households that joined during the password crackdown are keeping their subscriptions at full price or switching to the cheaper ad-supported plan as budgets tighten. This issue ties directly into the second financial trend analysts are watching on Thursday. 

Advertising Becomes the Real Growth Engine 

Netflix ad-supported tier revenue has moved from a small experiment to a major goal with clear targets. Netflix expects advertising revenue to reach about $3 billion for all of 2026, which is double last year’s total. Management credits this expansion to more programmatic ad sales and a larger advertiser base. The company also wants the average revenue per member on the ad-supported tier to eventually match the ad-free plan, which will require selling enough ads to cover the growing number of subscribers on the lower-priced tier. 

All of these changes are happening in a wider context. Netflix has kept its annual revenue forecast between $50.7 billion and $51.7 billion and has raised its free cash flow guidance for 2026 to about $12.5 billion, up from an earlier estimate of around $11 billion. The company is also sticking to its 31.5% operating margin target for the year, even as content amortization peaks this quarter and then slows later in 2026. 

The Iran Wildcard and the Streaming-Versus-Cinema Debate 

Geopolitical uncertainty often leads people to spend more time at home, benefiting streaming platforms like Netflix. When major world events change viewing habits, Netflix usually sees a boost as people choose the living room over the theater or office. Recent tensions around Iran have followed this trend, and some analysts have reported an increase in at-home viewing linked to global anxiety, even if it does not show up directly in the earnings report. This situation emphasizes a bigger debate in the entertainment industry. As AI helps create and deliver content more quickly and personally, streaming services gain an edge over movie theaters, which rely on large audiences showing up at the same time. Netflix’s algorithm can connect niche content, like documentaries or foreign-language series, with viewers that theaters cannot reach profitably. 

What Thursday’s Print Will Actually Settle 

Anyone building an NFLX Thursday July 16 earnings preview heading into the report should watch three figures closely: the advertising revenue run rate against that $3 billion annual target, the operating margin trajectory as content amortization peaks, and any forward commentary on how AI production tools are affecting the cost of the second-half content slate. Investors searching for a single Netflix Q2 earnings Thursday, July 16, 2026, AI content subscriber growth narrative will likely find one — but it may be a somewhat nuanced story than either the bulls or the bears currently expect, with cost discipline on the production side offsetting a fully mature password-sharing tailwind. 

Thursday’s release will not settle the debate over how much of Netflix’s future growth comes from artificial intelligence versus old-fashioned hit-making. What it will do is give investors their clearest read yet on whether the company can keep expanding margins while spending record sums on both content and the AI tools changing how that content gets made. An NFLX Q2 2026 ad-supported tier revenue AI production tools investor preview built purely on Wall Street’s consensus numbers misses the more interesting question underneath them: whether Netflix’s AI bet becomes the template every other studio in Hollywood eventually copies, or a costly experiment the company quietly scales back the moment content costs stop falling. Thursday afternoon will start to answer that question, even if the full picture takes several more quarters to come into focus. 

Source: Netflix Q2 Preview: Why Its $3 Billion Ad Bet Needs More Inventory 

Hsinchu, Taiwan — Dateline | July 14, 2026 

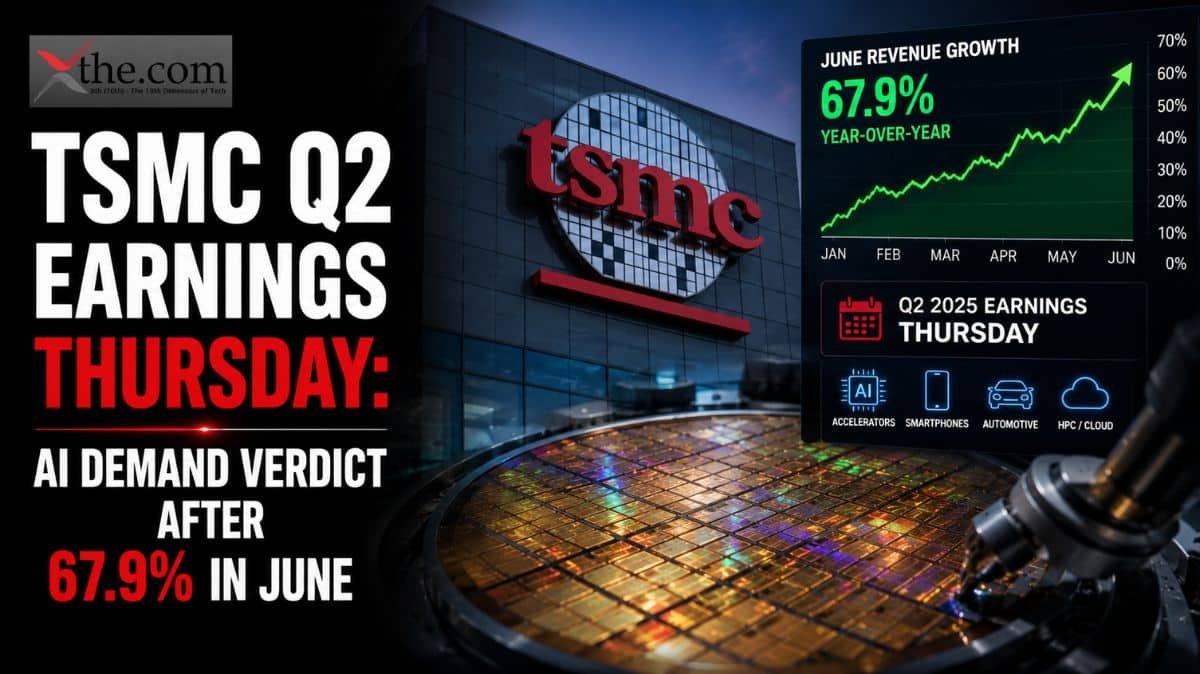
A 67.9 percent jump in monthly revenue is unusual, but that is exactly where Taiwan Semiconductor Manufacturing Company stands ahead of Thursday. TSMC’s Q2 earnings on July 16 are now the most consequential print of the week for chip investors, and the question is no longer about whether the AI buildout is real. It is how much longer TSMC’s order books can keep proving it. The TSM Q2 2026 results arrive with the company’s June revenue report already in hand, and the number inside it — a 67.9 percent year-on-year surge to NT$442.68 billion — has reset expectations for what “strong” even means in the foundry business. 

TSMC usually does not release full quarterly results in advance, but its monthly revenue updates serve as a running scoreboard. April, May, and June each set new records, and the second quarter ended at about NT$1.27 trillion, matching management’s guidance of $39.0 billion to $40.2 billion from April. Revenue for the first half of 2026 reached NT$2.4 trillion, up 35.6 percent from the same period last year. These are not small gains. They make Wall Street wonder if its forecasts have been too cautious. 

Why Thursday’s Call Holds More Significance Than Usual 

TSMC’s Q2 earnings conference on July 16 will be held at 2:00 p.m. in Taipei, which is 2:00 a.m. Eastern Time on Thursday. It is not an ideal time for U.S. analysts, but they will be tuning in. Every semiconductor desk, AI infrastructure fund, and most hyperscalers relying on TSMC’s advanced chips will be listening for one thing: CEO C.C. Wei’s comments on whether the current pace of AI chip orders can sustain into 2027 or is just a temporary surge from a few big model-training projects. 

The stakes go beyond TSMC’s own stock. As the manufacturer behind the most advanced logic chips for Nvidia, Apple, AMD, and a growing list of custom AI silicon designers, TSMC functions as the TSMC AI supply chain bellwether for the entire technology sector. When its capacity is booked solid, it tells investors that AI infrastructure spending has not yet hit a ceiling. When utilization softens, even slightly, the ripple reaches memory makers, packaging suppliers, and the cloud giants whose capital budgets depend on chip availability. 

The Guidance Question 

Management already increased its full-year 2026 revenue growth forecast to over 30 percent in U.S. dollars during the April call, up from the mid-twenties. Now, the question is whether that number moves again. TSMC guidance raises capex July 16. Speculation has intensified after TSMC said it plans to spend near the top of its $52 billion to $56 billion capital expenditure range for the year. Just a year ago, that would have seemed bold. Executives have called AI-related demand for high-end computing chips ‘extremely robust,’ saying the growth is driven in part by a shift toward more demanding agentic AI systems. 

Citi’s semiconductor team has staked out one of the more bullish positions ahead of the print. Citi analyst Ms. Chen recently raised her price target on TSMC’s Taiwan-listed shares to T$3,800 from T$2,875, while maintaining a Buy rating and placing the stock on a 30-day upside-catalyst watch. That move shows the broader idea behind TSMC Citi price target raise July 2026 coverage: expectations that TSMC will not only beat its own revenue guidance but extend its annual outlook once more, supported by continued 2-nanometer and 3-nanometer pricing strength. 

What the Numbers Need to Show 

Investors looking at Thursday’s results will focus on four key numbers in addition to revenue. Gross margin, expected to be between 65.5 and 67.5 percent, will indicate whether TSMC is passing higher costs and overseas expenses to customers without hurting profits. Analysts also want to see whether full-year revenue growth guidance, now above 30 percent, will rise further. Comments on capital spending will reveal if TSMC plans to spend at the top of its announced range. Updates on N2 process capacity and CoWoS advanced packaging—now seen as the biggest bottleneck in AI chip production—will show how quickly customers like Nvidia can get the chips they need. 

There are still risks. TSMC’s stock price already reflects high margins and high factory use, so it could react strongly to even a small drop in demand. Foundry revenue also trails customer orders by one to three quarters, depending on the chip type, so any slowdown in spending by big cloud companies would likely appear later in the year, not in Thursday’s results. Risks also include challenges with overseas expansion, especially the Arizona project, and the chance that higher chip prices could eventually hurt consumer electronics profits. These are factors that optimistic investors sometimes overlook. 

Options markets are already pricing in a wide post-earnings swing, a signal that traders expect Thursday’s numbers to move the stock meaningfully in either direction rather than simply confirm a consensus view that has grown increasingly bullish over the past month. Still, the search terms circulating across trading desks this week tell their own story. Queries framed around “TSMC Q2 earnings July 16 AI demand verdict guidance raise expected” and “TSMC quarterly results Thursday biggest signal AI chip spending 2026” reflect an investor base that has largely stopped asking whether AI demand is real and started asking how much higher the ceiling goes. TSMC’s own June numbers did more to answer that question than any analyst note could. 

The Forward-Looking Read 

Thursday’s earnings conference will not end the debate about how long the AI spending boom will last, but it will give the clearest update so far. If TSMC beats income expectations and raises its guidance again, it would indicate that capacity, not demand, remains the main constraint on AI infrastructure. This would keep TSMC’s pricing power and margins strong. On the other hand, if management sounds cautious about 2027 orders, it would be the first sign that the outlook is becoming less certain. Either way, the rest of the chip industry will be watching Hsinchu closely before markets open Thursday.

Source: TSMC’s June sales drive revenue surge of 68% ahead of earnings report 

Houston, Texas | July 14, 2026 

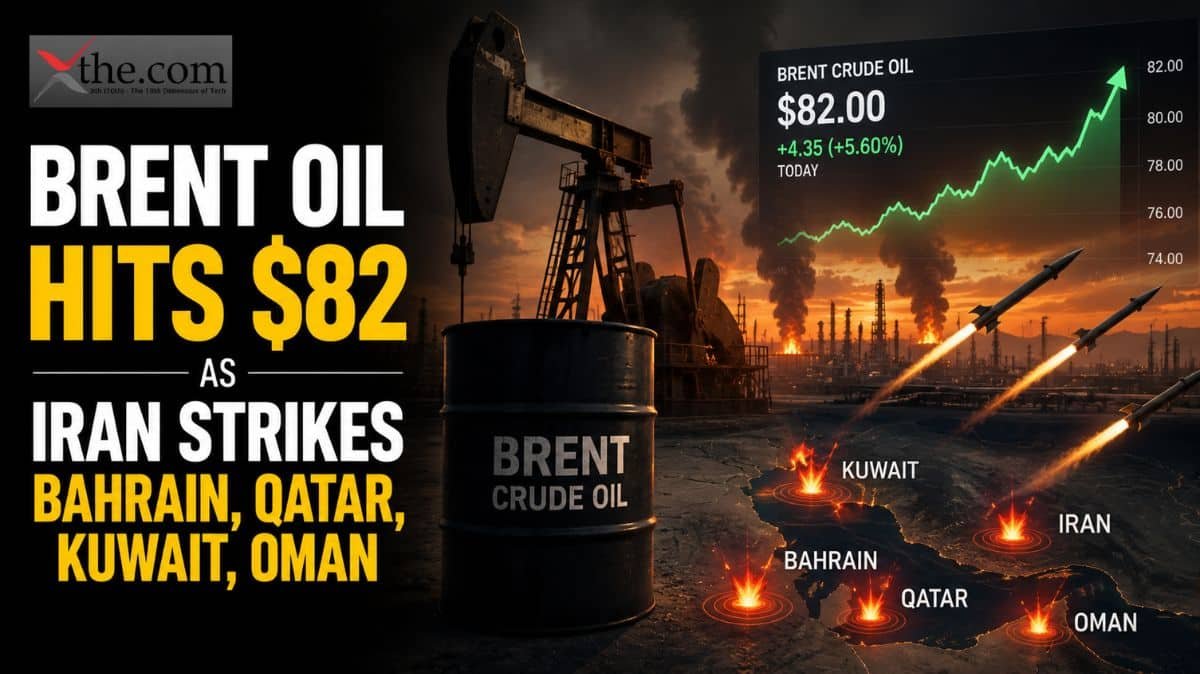
A missile hit a Kuwaiti offshore drilling platform early Sunday morning. Six hours later, traders in Houston saw crude oil make its biggest single-day jump of the summer. By Monday’s close, Brent crude at $82 Iran strikes had become the headline number driving every energy desk conversation from Houston to Singapore. Iran’s decision to widen its retaliatory campaign beyond Israeli and American targets, hitting four Gulf states in one weekend, has changed the risk premium for every barrel of crude traded this week. 

Iran’s Weekend Escalation Reaches Four New Fronts 

Tehran’s answer to a third straight night of American bombing near the Strait of Hormuz went beyond military sites. Over the weekend, Iran hit Bahrain, Qatar, Kuwait, and Oman in a coordinated attack that clearly widened the conflict. Missiles and drones struck Manama, Doha, Kuwait City, and Musandam within hours. Air raid sirens sounded in Bahrain for the third time in a week, and Kuwaiti air defense crews stopped incoming fire over the capital. The attacks seemed planned, not random: Iran targeted places with an American military presence, not just neighboring countries. 

Energy analysts covering the region describe this as the moment the conflict stopped being a bilateral dispute. Iran expands strikes on Gulf states’ weekend operations after weeks of exchanges confined largely to Iranian and Israeli soil, and that expansion changes the calculus for every shipping company routing tanker through the Gulf. 

Qatar’s Exposure Raises the Stakes 

Qatar is at the center of this escalation for reasons beyond its location. It hosts the US Central Command’s forward headquarters, which made it the target Iran had mostly avoided until now. Doha’s efforts to mediate had protected it from direct attacks, but that protection is now gone. Qatari officials confirmed the interception of threats near the capital, and the country’s long-standing role as a bridge between Washington and Tehran now seems much more fragile. 

The Oil Math: How Crude Priced in the Weekend 

Crude futures opened Monday already pricing in weekend headlines, and the move accelerated through the session. WTI crude at $73.85: Iran conflict pricing reflected a market recalibrating to supply risk in real time, while the international benchmark told an even sharper story. Brent $79.41: Iran Hormuz trading levels held through the morning session before a single presidential announcement pushed the benchmark decisively higher. 

Overall, it was one of the most volatile trading days of the year, with oil 3.4 percent surge Monday activity putting crude on track for its biggest single-day gain since the ceasefire ended. By the close, the $82 oil price on July 14 was the number of traders quoted everywhere. The price jumped in bursts; each linked to a new headline from the Gulf. 

Trump’s Tariff Adds Fuel 

Brent’s jump above $82 was triggered by news from Washington, not Tehran. On Monday, President Trump said the US would bring back its naval blockade of Iranian shipping through the Strait of Hormuz and add a 20 percent charge on all other cargo passing through. He described this as payment for the security the US Navy now provides, saying America would be the strait’s “guardian.” This announcement came just hours after the weekend strikes and gave the market another reason to push crude prices higher: not just supply risks from fighting, but a new cost added to every barrel moving through this key route. 

Gulf States Respond 

Bahrain, Kuwait, and Oman acted fast after the strikes ended. Each country put its air defenses on high alert and held emergency meetings with its foreign ministry to plan a joint response. Bahrain, where the US Navy’s Fifth Fleet is based, strongly condemned the attacks, calling them systematic instead of isolated. Kuwait’s defense ministry said it had intercepted several incoming threats. Oman, which had just hosted Iran’s foreign minister for security talks days before the strikes, also condemned the attack in strong terms. 

The international fallout makes an already tough mediation process even harder. Qatar and Oman have both acted as back-channel go-betweens for Washington and Tehran. Now, with both countries hit by direct strikes from the sides they are trying to bring together, it will be much harder for them to maintain that role. 

How Much Higher Can Oil Go? 

It’s important to remember the bigger picture. Earlier this year, Brent peaked at nearly $120 per barrel during the conflict. Compared to that, the current $82 still leaves plenty of room for prices to rise if the Strait of Hormuz is fully closed rather than just partly disrupted, as traders now expect. About a fifth of the world’s oil and liquefied natural gas passes through the strait every day, so any lasting shutdown would quickly affect refining margins, shipping insurance, and fuel prices within days. 

Trading desks are using short headlines in market chat rooms this week: “Brent oil $82 Iran strikes Gulf states Bahrain Qatar Kuwait Oman July 14” sums up the scale of the move for those reading wire alerts. Another headline, “WTI crude surges 3.4 percent Iran expands retaliation Gulf states July 2026,” is also making the rounds among traders watching the domestic benchmark’s reaction. 

What happens next will depend more on whether Doha, Muscat, and Manama can keep any diplomatic routes open while under attack than on oil markets themselves. If mediation fails completely, the market’s current pricing for a limited disruption may prove too cautious. Energy traders in Houston are already updating their risk models for that scenario, and the next few days of Gulf state meetings will likely decide if $82 is the top or just the start.

Source: Oil prices jump following the latest fighting in the Middle East, while AI stocks sink 

Washington, D.C. 

Bond traders were up early today. At 10:00 a.m. Eastern, Fed Chair Warsh first testimony before the House Financial Services Committee. It happens on the same day as the June Consumer Price Index release and right after second-quarter bank earnings. Three catalysts, one morning, zero precedent. This is Warsh’s congressional testimony on July 14, and it is the first extended, on-the-record look by lawmakers and markets to see how the new Fed chair thinks. 

Kevin Warsh became Fed chair on May 22, taking over from Jerome Powell after a mostly party-line confirmation. He led the June Fed meeting, kept rates steady, and said little except that he would fight inflation. That caution is why today is important. The law requires the Fed chair to testify before Congress twice a year, so this is the first time Warsh’s monetary policy for 2026 will be discussed in detail, not just in a short press conference but through hours of direct questions. 

Why the House Comes Before the Senate 

Here is where the record needs a correction. Some early previews of today’s hearing described Warsh appearing before the Senate Banking Committee. That is not accurate. Today’s session, July 14, is on the House Financial Services Committee. The companion’s appearance, Warsh’s semi-annual testimony before the Senate Banking Committee, follows on July 15 at 10:00 a.m., completing the twice-a-year cycle Congress requires every Fed chair. Readers tracking both hearings should expect two distinct transcripts, two different committee rosters, and potentially two different lines of questioning, even if the underlying Monetary Policy Report is identical. 

This difference is important for anyone who is watching the market. House members usually focus more on housing costs and how tariffs affect consumer prices. Senate Banking members often ask about financial soundness and the Fed’s balance sheet. If a trader pays attention to the wrong committee’s questions, they could misread the market signals. 

A Governor Who Already Knows the Room 

Warsh is familiar with this setting. He served as a Fed governor from 2006 to 2011 and often testified before Congress during the financial crisis. People who worked with him say he is careful with his words, preferring expressions such as “price stability” and “credibility” instead of giving forward guidance. Just 12 days ago, he told an audience in Portugal that he would not provide forward guidance, since the Fed meets again in 4 weeks. Expect him to focus on the big picture today and avoid giving particular details. 

Inflation, Iran, and the Data Landing on His Desk 

This is an unusual situation. The June CPI data, released this morning, is expected to show headline inflation dropping to about 3.8% year over year, down from 4.2% in May. Core inflation should stay near 2.8%. Economists say this improvement is mostly due to lower energy prices, which are linked to easing tensions in the Middle East. This explains the connection between Warsh, inflation, and Iran rate hikes. Lower oil prices bring down headline inflation, reducing pressure on the Fed to raise rates soon. 

Markets are not fully convinced that a hike is off the table. Futures pricing has hovered around a one-in-four chance of a rate increase at the Fed’s next meeting, with the balance of expectations favoring a hold. That sets up the Fed’s July 28 29 rate decision with Warsh as the next hard deadline. Nothing announced today binds the committee’s hand at that meeting, but Warsh’s tone in front of the House this morning, and again before the Senate tomorrow, will shape how aggressively traders reprice the odds heading into the final week of July. 

What Changes with a New Chair 

It is worth pausing on how unusual this moment is structurally. This is the first Warsh testimony for Powell replacement territory in the truest sense: Congress has not heard a semi-annual monetary policy report from anyone other than Powell in years. Committee staff on both sides have devoted weeks preparing questions specifically intended to probe whether Warsh’s framework diverges meaningfully from his predecessor’s, particularly on the pace of any future easing and on how the Fed weighs newer variables, including the inflationary effect of surging AI infrastructure investment, a topic that entered FOMC discussions for the first time at the June meeting. 

Corporate disclosures have made things more interesting. Warsh owns digital assets, including Bitcoin, which he has called an important asset class. During his confirmation hearing, he told senators that digital assets are becoming a key part of the financial system. At least one lawmaker is likely to ask how his personal holdings relate to his role in regulating these assets, even if the discussion is short. 

Reading the Transcript in Real Time 

For anyone trying to parse “Warsh first congressional testimony July 14, 2026, Fed Chair monetary policy Iran” as it happens, the useful signal is not any single soundbite but the cumulative weight of word choice across both days. Does Warsh repeat “price stability” more often than “maximum employment”? Does he characterize the Iran-driven energy relief as durable or temporary? Those small tells tend to move front-end Treasury yields faster than any explicit rate of guidance should, precisely because Warsh has made clear he intends to give none. 

Anyone assembling a research note before the 10:00 a.m. start should treat “What to expect Warsh testimony rate hike signals inflation Iran July 2026” as a live document. The Monetary Policy Report, released before the hearing, sets the official record. But today’s real value comes from the unscripted questions and answers after the prepared remarks. One unplanned comment from a chair with five years of experience in this role can move markets more than the report itself. 

The next two days will not settle the debate about what happens to rates after July 29. But they will show Congress and the markets whether the new Fed chair will communicate like Powell did, or if he plans to set up his own style as someone who has been both a witness and now the chair in these hearings.

Source: Fed Chairman Kevin Warsh on tap to make his first appearance before Congress 

New York, New York 

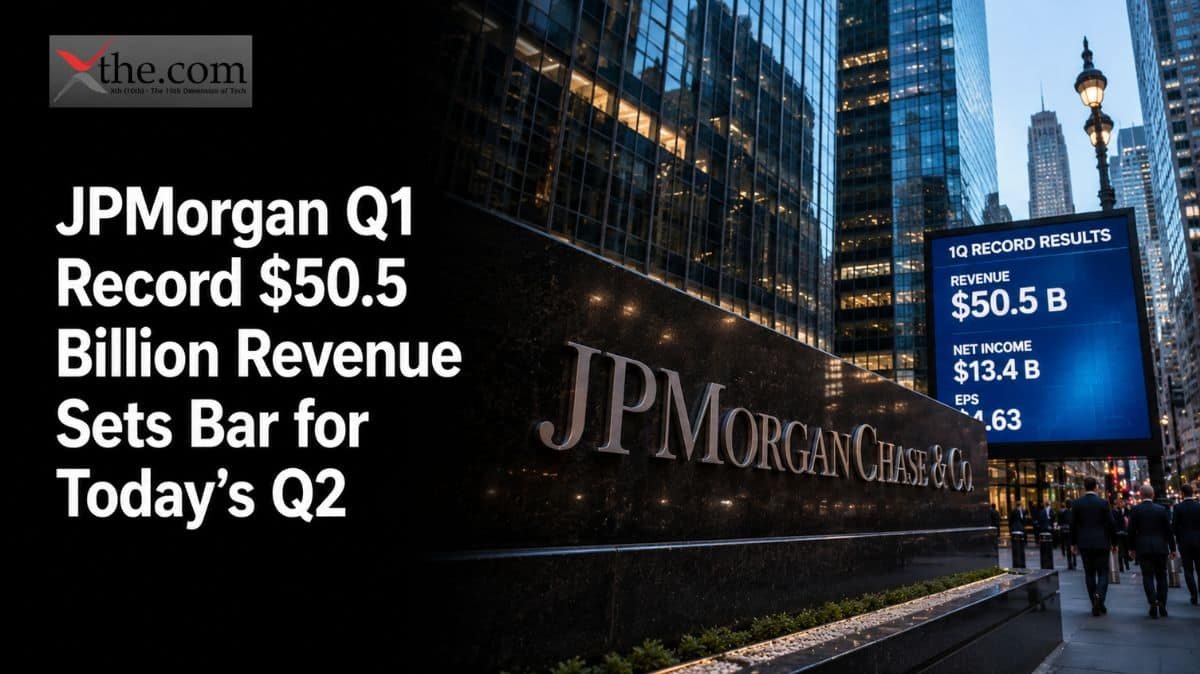
One quarter changed expectations across the banking sector. When JPMorgan Chase reported $50.54 billion in managed revenue for the first quarter, it beat estimates by more than $2 billion and prompted analysts to revise their models for the rest of the year. Now the reckoning has arrived. JPMorgan Q2’s earnings on July 14 land before the opening bell, and the question looming over trading desks is simple: can the bank match a quarter that even its executives called exceptional? The JPMorgan Q1 record revenue figure set a high standard, and today’s results will show if that was a one-time peak or the start of a new trend. 

The $50.54 Billion Baseline 

Numbers don’t consistently tell the whole story, but JPMorgan’s first quarter came close to speaking for itself. JPMorgan’s Q1 $50.54 billion record revenue was up 10% year over year, alongside net income at $16.5 billion and earnings per share of $5.94, beating Wall Street’s $5.45 estimate. All major business lines contributed. The Commercial and Investment Bank saw revenue grow by 19%, and return on tangible common equity hit 23%, a level most regional banks can only hope to reach after years of growth. 

FICC Led the Charge 

Fixed income trading rarely grabs headlines outside of earnings season, but this quarter it did the heavy lifting. JPM FICC 21 percent Q1 growth pushed that desk’s revenue to roughly $7.08 billion, the strongest showing in years. Institutional clients spent the quarter hedging against tariff whiplash, rate uncertainty, and a jittery Treasury market, and JPMorgan’s trading floor captured a large share of that activity. Combined with equities trading, total Markets revenue hit a record $11.6 billion, nearly $2 billion above the previous high. 

Investment Banking Roared Back 

After two slow years, dealmaking finally picked up again. JPMorgan’s investment banking 28 percent, raising fees to $2.88 billion, mostly from advisory work and equity capital markets. Companies that had put off acquisitions in 2024 and 2025 started making deals again, and JPMorgan’s bankers benefited. This was the strongest sign yet that the M&A slowdown was over. 

Net Interest Income Held Its Ground 

The bank’s oldest and steadiest business also delivered. JPMorgan’s net interest income was $25.5 billion for the quarter, up 9% from last year, even as the Federal Reserve’s rate outlook became less clear. Average loans increased by 11% to $1.5 trillion, and deposits grew by 7% to $2.6 trillion, giving the bank a larger base for earning spread income. CFO Jeremy Barnum slightly lowered the full-year net interest income forecast, from about $104.5 billion to $103 billion, briefly unsettling the stock during an otherwise strong quarter. 

What Wall Street Wants from JPM Stock Q2 Results 

Analyst models heading into today diverge on magnitude but agree on direction. Consensus estimates place second-quarter earnings per share between $5.44 and $5.61, and revenue around $48.6 to $49 billion. That’s lower than the first quarter’s results but still a solid year-over-year gain. JPM stock Q2 results will be less on whether JPMorgan beats expectations and more on the tenor of the report. Options suggest the stock could move 4.4% on the day of the release, which is a bigger swing than usual for a stock near its 52-week high. Investors who have bought JPM shares this year—up about 18.6% over the past year—are not likely to tolerate much disappointment at these prices. 

The outlook for net interest margin is key. If the Fed keeps suggesting lower rates, JPMorgan’s spread income could shrink even if loan volumes rise. Another cut to full-year net interest income guidance, after the April reduction, would probably unsettle the stock, no matter how strong trading revenue is. If guidance holds steady or goes up, it could restart the rally that slowed after the first quarter. 

The Hormuz Wildcard 

Geopolitics usually doesn’t affect bank earnings reports this directly, but the shipping problems in the Strait of Hormuz are now too big to ignore. The conflict with Iran affects JPMorgan in two ways. It creates the kind of market volatility that boosts trading revenue, especially in energy and currency markets, as in the first quarter. But it also creates risks for JPMorgan’s energy-related loans, since higher costs and shipping delays can put pressure on borrowers who were in good standing not long ago. 

Jamie Dimon has been warning about a complicated risk environment for several quarters, and today’s call will likely include new comments on how the bank sees credit quality in this context. Investors should pay attention to whether Dimon describes the Hormuz-related volatility as a positive for trading, a negative for credit, or both. His outlook frequently influences how the whole banking sector trades that day. 

What to Watch When JPMorgan Reports Today 

Three things are more important than whether JPMorgan beats expectations. First, watch the full-year net interest income guidance—a second cut would show that rates are hurting more than management admitted before. Second, look at the net interest margin, which reveals if the spread of business is getting tighter or looser. Third, look for any specific numbers on credit reserves in energy or shipping-related loans, since that’s where the Hormuz disruption would first appear in the bank’s finances. 

Anyone searching for “JPMorgan Q2 earnings July 14, 2026, what to expect to record Q1 $50.5 billion” really wants to know if the bank’s strong balance sheet—a term Dimon often uses—can withstand both trading gains and credit risks coming from the same event. The first quarter showed it could. Today’s results will be revealed if that continues. 

A Preview Worth Watching Live 

For traders wanting to follow the release as it happens, “JPMorgan Chase Q2 2026 results FICC NII investment banking preview today” is one of the top search terms this morning, and it’s easy to see why. JPMorgan’s earnings start the whole bank reporting season, with Goldman Sachs, Bank of America, Wells Fargo, and Citigroup all reporting on the same day. The June Consumer Price Index report also comes out that morning, adding big-picture economic data to company results. 

What happens between 7:00 a.m. and the market open will shape investors’ view of bank earnings for the rest of the quarter. If JPMorgan’s trading desks took advantage of Hormuz-driven volatility and credit quality stayed strong, the stock will probably keep rising in 2026. But if net interest income guidance drops again or credit costs go above the $2.5 billion set aside in the first quarter, expect a tougher day for the stock. Either way, the record JPMorgan set in the first quarter is no longer only a benchmark—it’s now the standard the bank has to meet.

Source: JPMorgan Chase (JPM) Q2 Earnings Report Preview: What To Look For