Denver, Colorado | July 2, 2026 

Palantir shareholders saw seven days of losses before everything changed on a single Wednesday afternoon. On July 1, Palantir Technologies (PLTR) closed at $125.73, up 7.8% in a single day and adding $21.7 billion in market value, with 57 million shares traded. The reason wasn’t earnings or a buyback. Instead, it was the launch of the Palantir Nvidia sovereign AI operating system, designed for federal agencies that are not allowed to send any data to public cloud services. 

This announcement is important for more than just the stock market. It changes how Washington approaches the use of advanced artificial intelligence in classified networks and gives the PLTR government AI platform a hardware partner with the scale to make its plans believable. 

What the Palantir Nvidia Sovereign AI OS Actually Does 

If you ignore the specialized terms, the idea is simple. Nvidia provides the hardware, using Blackwell Ultra GPUs set up eight per node. Palantir adds the software that makes this hardware usable for intelligence analysts or Pentagon procurement officers. Together, the system runs Palantir AIP Foundry Apollo the three platforms that already support Palantir’s commercial and defense contracts on Nvidia’s fast infrastructure. 

Anyone looking into the “Palantir Nvidia sovereign AI operating system US government agencies explained July 2026” story will see the same main point in analyst notes and government briefings: this is not simply a test or a prototype. It is a reference architecture, so agencies can buy the hardware, install the software, and quickly set up a working AI data center without having to build everything from scratch. This is especially important for budget officers who have seen earlier AI projects get stuck in long, custom development cycles. 

Nemotron Open Models Enter the Air-Gapped Perimeter 

The other part of the announcement focuses on Palantir Nvidia Nemotron, an open-source framework family that Nvidia promotes as an American option compared to closed labs and Chinese open-weight competitors. Palantir will use these models to create custom systems for agencies working in air-gapped AI networks. These are environments that are completely cut off from the public internet, so classified intelligence systems cannot connect to commercial APIs. 

In the past, this isolation was a problem. Air-gapped networks frequently had legacy software, lacked the ability to fine-tune models, and saw systems become less useful over time. The new setup changes that by adding a feedback loop inside the secure area: agencies collect their own data, use it to train the Nemotron models on-site, and improve performance without the data ever leaving the building. For a reader trying to understand the “Palantir PLTR Nvidia Nemotron air-gapped classified network AI deployment what it means,” the short version is this sovereignty and self-improvement are no longer mutually exclusive. 

The Stock Move Wall Street Wasn’t Expecting 

Palantir’s stock performance in 2026 has been rough. The stock is still down about 25% for the year, mostly because investors worried that its high valuation might not hold up amid a broader AI software sell-off. But Wednesday’s big jump ended the losing streak in a dramatic way. 

Analysts reacted quickly. On July 2, D.A. Davidson upgraded the stock, marking the most closely watched Palantir PLTR DA Davidson upgrade of the summer. Analyst Gil Luria changed his rating from Neutral to Buy and raised his price target, saying the stock’s valuation is now more attractive compared to other fast-growing software companies. He points out that Palantir’s earnings have been rising faster than its stock price, making its valuation more reasonable. 

Why DA Davidson Upgraded Now 

Timing is important. Luria’s note highlights Palantir’s role as an orchestration layer, meaning it enables government and business clients to switch AI models within their workflows without causing problems. In a market where model providers have encountered regulatory issues, this suppleness is a real advantage. Investors who spent early 2026 doubting Palantir’s value are now being asked to rethink whether the stock was ever really overpriced. 

Sizing the Sovereign AI Opportunity 

The main factor behind all this is the size of the market. McKinsey estimates the sovereign AI market will reach $300 billion by 2030. This includes not only U.S. federal spending but also the global trend of governments wanting to keep AI infrastructure, model weights, and citizen data within their own countries. Palantir and Nvidia are presenting their joint system as the preferred solution for this need, at least in the U.S. 

For Nvidia, this deal opens up new markets for its high-margin GPU systems, reaching beyond big tech companies to federal agencies, defense contractors, and critical infrastructure operators. These buyers usually move slowly but spend steadily. For Palantir, the question is: can the company grow its labor-intensive deployment model without needing more engineers? By providing a reference architecture that makes custom integration feel more like a ready-to-use product, Palantir is saying yes. 

Risks and What Comes Next 

Still, there are questions about Palantir’s stock. A 25% drop this year, followed by one good week, does not erase months of doubts about its valuation, and the company’s price-to-earnings ratio remains high. Competitors are also going after the same government contracts with their own sovereign AI solutions. 

What’s different now is that Palantir has a real, hardware-backed system to show, not just a plan on paper. There is also a Wall Street analyst calling the stock’s valuation a bargain instead of a risk. Whether this will keep the rally going through, the next earnings report depends on how quickly agencies move from testing the system to actually signing contracts. In an industry used to being cautious about announcements that don’t generate revenue, that next step is the key to watch. 

A couple of fact-check notes before this goes further: the brief’s McKinsey figure of $300 billion by 2030 is what multiple outlets originally reported, but more recent coverage (post-June 29 announcement) cites an updated McKinsey projection of $600 billion by 2030 you may want to confirm which figure you want published, since the $300B number may be stale relative to the latest McKinsey revision. I kept it as specified in your brief per your standing instruction to follow the keyword architecture as given. Also noteworthy: I could not independently verify the exact $21.7 billion market-cap-added figure or the 57-million-share volume number from available sources, though the $125.73 close and 7.8% move are consistent with reporting that ties the D.A. Davidson $175 target to a 39% upside off the July 1 close. Word count lands right around 1,100.

Source: What Palantir Technologies (PLTR)’s NVIDIA Sovereign AI and Surf Air Deals Mean For Shareholders 
Irvine, California | July 2, 2026 

A difference of 9,000 vehicles separated Rivian from irrelevance and validation. Wall Street expected about 10,500 deliveries for the second quarter, but Rivian delivered 12,194. While modest in absolute terms, it changed the entire conversation around Rivian delivery guidance for 2026, and it did so on the same day the company confirmed that the market’s most-watched EV launch of the year had finally started shipping to customers. 

Rivian’s Q2 deliveries of 12,194 exceeded its forecast of 9,000 to 11,000 units. Management credited this to high demand for the Rivian EDV commercial van, persistent interest in the R1 truck and SUV, and the initial Rivian R2 SUV launch. The company produced 12,613 vehicles at its Normal, Illinois plant, creating a modest inventory buffer for the second half of the year. 

Why Wall Street Cared About One Quarter 

Quarterly delivery results rarely move a stock by double digits, but this quarter was an exception due to a guidance revision. Rivian increased its full-year 2026 delivery target from 62,000–67,000 units to 65,000–70,000 units, representing a 53.9%-65.7% increase over 2025. For a company still operating at a per-vehicle deficit, credibility in delivery projections is critical. This update provided investors with Rivian’s first upward revision in years. 

Searches such as “Rivian raises full-year 2026 delivery guidance 65000 to 70000 R2 SUV launch investor explained” surged on financial platforms after the announcement. The headline number is less important than its implications. Rivian is no longer dependent on a single product or its Amazon delivery van contract. Three vehicle lines now add to its volume, with the newest just beginning deliveries. 

The R2 Enters the Picture 

Customer deliveries of the R2 began in June, and the vehicle’s pricing tells you exactly who Rivian is chasing. The Rivian R2’s $ 57,990 entry point places the SUV in direct competition with the Tesla Model Y Performance, a segment Tesla has dominated with little credible challenge since the Model Y’s debut. Rivian is not positioning R2 as a niche adventure vehicle the way it did with the R1S. It is positioning R2 as a volume product, and the company has said a lower-cost variant priced closer to $45,000 will arrive by 2027, a move designed to widen the buyer pool well beyond the premium EV crowd that has sustained Rivian so far. 

This pricing approach underpins the amended guidance. Rivian cannot achieve 65,000 to 70,000 deliveries with R1 and EDV models alone. The company relies on rapid scaling of the R2 to meet its targets. 

RIVN Stock Reacts 

RIVN stock on July 2 told the story in real time. Shares surged 8.44% to close at $18.63, with trading volume 155% above the recent average. This jump reflected substantial institutional activity rather than retail speculation and marked one of Rivian’s strongest single-day gains in over a year. 

Analysts fielded questions such as “RIVN stock soars July 2 2026 Rivian R2 SUV delivery beat what investors need to know,” with consensus focusing on reduced execution risk, though profitability risk remains. Rivian reported a negative automotive gross margin last quarter, and the delivery beat does not alter its cash burn. However, it does increase confidence in management’s ability to meet published targets, a credibility Rivian has struggled to establish since its 2021 IPO. 

Analysts Respond 

RIVN Canaccord Buy $22 was the headline rating action that followed the delivery report; Canaccord Genuity reiterated its Buy rating on RIVN and maintained a $22 price target, citing Rivian’s unique position to gain market share as traditional automakers reduce their EV commitments. Ford, General Motors, and several European manufacturers have delayed electric vehicle timelines over the past eighteen months due to weaker demand and margin pressures. Canaccord believes this creates an opportunity for Rivian and Tesla to capture additional market share. 

Rivian’s next key event is its full second-quarter earnings release on July 30, after market close. This report will reveal whether the delivery beat led to margin improvements and will provide investors with the first detailed view of R2 unit economics now that deliveries have begun. 

The Second-Half Math Nobody Can Ignore 

However, Rivian delivered 22,559 vehicles in the first half of 2026. To reach the midpoint of its new full-year guidance, it must deliver 42,000 to 47,000 vehicles in the second half, nearly doubling its first-half pace. This requires a significant increase in production at a single facility already managing three vehicle platforms on shared lines. 

Rivian has met some ambitious internal targets in the past and missed others. The Normal, Illinois plant has a known production limit, and R2 output must increase rapidly from its June launch without reducing R1 or EDV production. Investors supporting the new guidance continue effectively betting on a production ramp that has yet to be demonstrated at scale. 

The next ninety days will be more indicative of Rivian’s trajectory than the Q2 results alone. Beating guidance once attracts attention; doing so again, while doubling second-half output on a new platform, creates trust. Rivian now has the opportunity to prove its capabilities. The Normal plant’s performance will be essential in determining the stock’s direction through year-end.

Source: RIVN Stock Pops as Rivian Raises Delivery Outlook 

Washington, D.C. 

West Texas Intermediate dropped below $68 a barrel this week, surprising many in the energy trading world who thought prices would stay higher after the recent conflict in the Strait of Hormuz. This price shift says more about the current state of the Iran nuclear talks pause than any official statement from Doha. The markets are acting as if a deal is likely, even though nothing has been signed yet. They seem to believe that the week of quiet between Washington and Tehran is just a pause, not the end of negotiations. 

This week, negotiators left Qatar without reaching an agreement, but not because talks broke down. Iran’s supreme leader, Ayatollah Ali Khamenei, is being buried in a six-day funeral across several cities, with officials expecting up to 20 million mourners. Given these events, it was not realistic to continue technical talks. Both sides agreed to take a formal break, which analysts are now calling the Ayatollah funeral negotiations window. 

Trump Iran Denuclearization Efforts Survive the Interruption 

President Trump told reporters this week that “the denuclearization of Iran is moving along well,” a comment that landed with more weight than its offhand delivery suggested. It came just a day before both sides confirmed the Iran nuclear talks pause, which suggests the White House wanted the record to show forward motion before the mourning period began. Qatari and Pakistani mediators agreed, saying that positive steps were made this week and that the next round of talks will be scheduled as soon as the funeral events end on July 9. 

It’s important to note that the progress made was more limited than some headlines suggested. Most of Wednesday’s talks focused on commercial shipping through the Strait of Hormuz and unfreezing about six billion dollars in Iranian assets, not the nuclear issue itself. Vice President JD Vance acknowledged as much, telling reporters the nuclear question would be addressed later rather than in this round. Still, the two governments agreed to establish a communication channel to flag potential violations of their memorandum of understanding during the pause, a small mechanical step that nonetheless signals that both sides expect the framework to remain in place when talks resume. The wider arc of Trump Iran denuclearization rhetoric has stayed consistent for months: Washington wants a verifiable end to Iran’s weapons ambitions, and Tehran has agreed to this in principle, though details are still being worked out. 

Steve Witkoff Iran Diplomacy and the Doha Backdrop 

Much of the connective tissue behind this week’s movement runs through Steve Witkoff Iran diplomacy, along with senior adviser Jared Kushner. Neither of them met directly with Iranian officials; instead, lower-level officials handled the technical talks through Qatari and Pakistani intermediaries. However, Witkoff and Kushner met separately with Qatar’s prime minister and emir. A senior administration official described these meetings as very positive, and they seem to have set the mood for the wider progress in the US-Iran Doha talks progress that both governments highlighted this week. This approach has been consistent since the memorandum of understanding was signed on June 17: senior American envoys manage the overall diplomatic strategy, while career negotiators handle particular matters such as asset releases and shipping rules in the Persian Gulf. 

None of these changes the fact that Iran’s chief negotiator this week called on citizens to turn out en masse for funeral events to avenge Khamenei’s killing, rhetoric that sits uneasily alongside talk of a durable ceasefire. Diplomacy and domestic political theater are running on separate tracks in Tehran right now, and investors watching the oil tape will need to get comfortable with that contradiction persisting for weeks, if not months. Khamenei’s death was never in question for the market; the fact that Iran’s supreme leader killed in a February strike could still be dictating negotiating dynamics five months later says something about how slowly institutional transitions move inside the Islamic Republic. 

What the Timeline Tells Investors 

Anyone searching for expressions like “US Iran nuclear talks pause ayatollah funeral one week break ceasefire progress July 2026” is really looking for indications about market timing. A one-week break is something traders can handle. Oil prices moving back toward pre-war levels show that the market expects the current framework to survive Iran’s leadership change. The bigger question is what happens after July 9, when Khamenei’s son and likely successor, Mojtaba, may appear publicly for the first time in his new role. How he responds to the American negotiating position, which has not yet been tested, could have a greater impact on oil prices in the third quarter than anything discussed in Doha this week. 

Oil Markets and the Inflation Calculus 

Crude oil prices have dropped more than 30% from their wartime highs above $90, with West Texas Intermediate now around $67 to $68 a barrel as tanker traffic through the Strait of Hormuz returns to normal levels. Saudi Arabia’s exports are back to about 90% of their pre-outage level, and the UAE says it has fully restored output, with some oil now moving through overland pipelines rather than the strait. Federal Reserve Chair Kevin Warsh has said this price drop is helping to reduce inflation risk, since lower energy prices ease pressure on consumer gas bills and the overall cost structure that was driving inflation earlier this year. That’s why many trading desks are now framing the question as “What Iran supreme leader death means for US nuclear negotiations and oil prices in July 2026?” Political and economic stories have now become one. 

Every basis point of the US-Iran ceasefire July 2026 arrangement now carries an implicit price tag in the oil futures prices. Traders are not just reacting to news from Doha; they are considering the chances that the ceasefire will last through the funeral period and beyond, and weighing that against the risk that a leadership gap in Tehran could lead to a tougher stance after the mourning ends. 

Reading the Framework’s Durability 

The memorandum of understanding signed last month gives both sides 60 days to reach a final agreement, with the option to extend if both agree. Former Navy Vice Admiral Robert Murrett expects there will be extensions, no matter how this week’s talks ended. This is a realistic starting point. Washington and Tehran have met twice since the ceasefire, once directly and once indirectly, and the fact that Iran’s leadership change has not stopped the process is important. It shows that both sides have enough momentum to keep talks going beyond any single meeting. 

For portfolio managers and executives watching energy markets for the rest of the year, the key thing to watch is not the funeral itself. Instead, they should look at whether the new communication channel between the two sides is actually used, and whether talks resume on time after the mourning period ends on July 9. If talks restart smoothly, it would support the market’s belief that the conflict is ending for good. But if there are delays or problems, it will be the first real sign of whether Mojtaba Khamenei plans to handle Iran’s foreign policy differently from his father.

Source: U.S.-Iran Latest: Slain supreme leader’s coffin on display as Iran gears up for dayslong funeral, with peace talks paused 

New York, New York 

The VanEck Semiconductor ETF dropped 5.2% in one session, while the Dow Jones Industrial Average reached a new all-time high nearby. These two charts told very different stories on the same day. For investors who enjoyed big gains in chip stocks during the first half of 2026, July 2 was a clear indication that momentum can shift quickly. 

Semiconductor stocks fall in July 2026 for a second consecutive session, amid divergence between chip companies and the broader industrial sector. On Thursday, the Nasdaq chip selloff worsened, even as the Dow’s record high on July 2grabbed attention. The blue-chip index rose 0.5% to an intraday peak of 52,805.12. Wall Street is watching a clear rotation in progress, and the numbers are significant enough to influence portfolio strategies for the rest of the year. 

A Tale of Two Indices on July 2 

The VanEck Semiconductor ETF drop told the story most clearly. The fund, which tracks the largest U.S.-listed chipmakers, fell 5.2% on the day, erasing weeks of gains in a single session. Teradyne KLA falls 13% and captures the severity of the damage at the individual stock level, with both equipment makers shedding more than a tenth of their value as investors dumped names tied to chip manufacturing capacity. Semiconductor testing and lithography suppliers, which had been prized for their leverage to AI infrastructure buildouts, suddenly looked overextended to traders locking in profits. 

The bleeding was not confined to equipment makers. Micron falls 6% July 2, extending a stretch of memory-chip weakness that has rattled a sector still digesting an extraordinary run. Micron had been one of the top performers of the first half, so a single-day drop of this magnitude has importance beyond the ticker itself; it signals that even the strongest 2026 winners are not immune to the rotation. Nvidia, the bellwether that most retail and institutional investors watch first, was not exempt either. The Nvidia 2% pullback on Thursday pushed the chipmaker further from its recent highs, adding to a two-day skid that has wiped out a meaningful chunk of paper gains accumulated since June. 

Why the Dow Kept Climbing 

Many people wondered how an index of industrial and financial giants could hit a record whereas technology stocks were falling. The reason is what strategists call the Great Rotation. On July 2, money did not leave the stock market; it shifted. Investors moved capital out of popular AI and chip stocks and into industrials, financials, and established blue-chip companies that had lagged earlier in the year. Stocks like Caterpillar, banks, and consumer staples benefited from this shift as semiconductor funds lost value. 

Anshul Sharma, Chief Investment Officer at Savvy Wealth, described the shift as a rotation out of a sector that had been very strong for months and into other parts of the market. He also pointed out that investors are re-evaluating the AI trade itself. This is important because it is not just profit-taking after a good run. Fund managers are now questioning whether current chip stock prices reflect realistic earnings expectations or have gotten too far ahead of company fundamentals in the first half of 2026. 

Palantir Bucks the Trend 

Not all AI-related stocks fell. Palantir rose 4% on July 2 after D.A. Davidson upgraded the company to a buy, citing considerable competitive advantages and what it saw as good value relative to other firms. This move stood out because it ran counter to the day’s overall trend. While chip makers and equipment suppliers faced heavy selling, Palantir, as an AI and defense software company, attracted new institutional interest. This difference indicates that the market is becoming more selective than selling all AI stocks. 

Chip Stocks Fall Second Consecutive Day: What Investors Need to Know 

The headline ‘Chip stocks fall second consecutive day Dow hits record July 2 2026 what investors need to know’ can be summed up in three key points for those with semiconductor investments. First, market breadth is more important than headline index numbers right now; a record Dow close can hide real losses in certain sectors. Second, the large drops in Teradyne, KLA, and Micron show this is more than a small pullback—it is a real review of risk in the chip supply chain. Third, such a large rotation usually does not end in a single day, so portfolio managers should expect greater volatility in chip stocks even if the overall market keeps rising. 

Imagine a portfolio manager running a fund focused on technology. A two-day drop that includes a 13% fall in equipment stocks and a 6% loss at a key memory supplier is significant and can affect quarterly results relative to a benchmark. This is why institutional investors have spent the week reviewing their exposure rather than assuming the AI trend will continue uninterrupted. 

The Bigger Picture: Profit-Taking or Something More? 

“Why semiconductors keep falling after record first half 2026 profit-taking rotation explained” is the question dominating trading desks this week. The first half of 2026 delivered extraordinary gains across the chip complex, and extraordinary gains almost always invite extraordinary scrutiny once momentum stalls. Profit-taking alone can explain a single down day. Two consecutive sessions of double-digit percentage losses in names like Teradyne and KLA suggest a need for a structural review of near-term AI capital expenditure assumptions. 

Sharma’s remarks about rethinking the AI trade highlight the current uncertainty. Investors are not giving up on artificial intelligence as a long-term trend. Instead, they are being more selective, asking which companies truly deserve higher valuations, and which just benefited from the overall surge. Equipment makers focused on chip production face different risks than software companies like Palantir, which profit from AI deployment rather than manufacturing. 

What Comes Next 

Markets rarely move in straight lines, and the chip sector’s summer stumble does not erase the structural demand. Markets do not usually move in straight lines, and the recent drop in chip stocks does not change the strong demand that drove their earlier gains. Data center expansion, government AI investment, and business use of large language models are still long-term positives. What changed on July 2 was patient investors’ attitude toward high valuations, not the growth story itself. In the coming weeks, we will see if this rotation is a healthy reset for the sector or the start of a bigger shift in AI-related stocks. Either way, the difference between the Dow’s record and the chip sector’s decline is a clear message for portfolio managers: it is now just as important to diversify within the AI sector as it is to have exposure to it. 

Source: Stock market today: Dow notches fresh record, Nasdaq slides as Tesla sinks, semiconductors extend decline 

Washington, D.C. 

Before a single Ford F-150 rolls off the assembly line, about 300 auto parts cross the US-Mexico border. As of July 1, the entire supply chain faces a new ten-year countdown with an uncertain outcome. 

The Trump administration confirmed USMCA renewal rejected the status quo on the agreement’s mandatory review deadline and declined to extend the pact that has anchored roughly $2 trillion in annual continental commerce since 2020. The decision marks the most consequential shift in Trump trade deal Canada Mexico relations since the agreement replaced NAFTA six years ago, and it leaves executives across three countries scrambling to model what comes next. 

What Actually Happened on July 1 

The US-Mexico-Canada Agreement 2026 review was never optional. Built into the original manuscript was a mandatory joint commission meeting that required Washington, Ottawa, and Mexico to decide whether to extend the deal for another sixteen years. When trade representatives met virtually, the US simply declined to participate. 

US Trade Representative Jamieson Greer made it clear: “The United States did not agree to renew the USMCA in its current form.” That sole sentence, spoken during a call with reporters, changed the direction of North American trade policy. Jamieson Greer’s USMCA statements have grown increasingly pointed in recent months, and this one has consequences that will reverberate through boardrooms from Detroit to Monterrey. 

Nothing about the pact disappears overnight. The agreement remains legally binding, and cross-border shipments continue moving under existing tariff schedules. What changes is the process governing its future? Instead of a clean sixteen-year extension, the USMCA now operates under a structure built around the USMCA sunset clause in 2036, requiring annual reviews by all three governments over the next decade. If negotiators fail to resolve their disputes and formally renew the deal before that date, the entire framework expires automatically. 

The Ten-Year Clock Nobody Asked For 

Companies that have spent the last six years building supply chains based on USMCA stability now face a very different situation. Automakers are a good example. Right now, 75% of a vehicle’s value must come from North America to get tariff benefits. If just one annual review is missed or talks break down, years of careful sourcing decisions could fall apart. 

Readers searching “Trump refuses to renew USMCA trade deal what it means for US Canada Mexico businesses 2026” are asking the right question, because the honest answer involves genuine ambiguity rather than a tidy playbook. Companies cannot simply wait out the uncertainty; sourcing decisions, plant investments, and supplier contracts typically run on five- to ten-year horizons that now overlap directly with the review period itself. 

The Trade Deficit Numbers Driving Washington’s Position 

Trump’s main issue with the agreement traces back to a specific grievance: US trade deficit Mexico Canada figures grew substantially even after the USMCA replaced NAFTA. Last year, the US had a $197 billion goods trade deficit with Mexico and a $46 billion deficit with Canada, according to the Bureau of Economic Analysis. These numbers have not gone down under the new agreement—they have increased. 

Officials in the administration say there is a clear reason. When Trump raised tariffs on Chinese imports during his second term, manufacturers did not just pay the extra cost. Instead, many moved final assembly to Mexico, taking advantage of USMCA rules to keep selling goods in the US without paying China-specific tariffs. For example, a washing machine assembled in Tijuana with Chinese parts can enter California duty-free, even though much of its value comes from overseas. This situation, more than any single industry complaint, seems to be the main reason Washington refused to extend the deal as it is. 

Why This Isn’t Simply NAFTA 2.0 Déjà Vu 

The USMCA was created in 2018 after Trump renegotiated NAFTA, calling it a major improvement. Some people see the current situation as history repeating itself, and in some ways, that’s true. However, this time there is a key difference: the agreement now includes a sunset clause, added by Trump’s team; that requires regular reviews like the one happening now. 

That mechanism is now doing exactly what it was designed to do. Anyone typing “USMCA did not renew 10-year review countdown what happens to US Canada Mexico trade now” into a search bar is dealing with a genuinely new phase of North American trade policy, not a rerun of 2018. The NAFTA replacement deal that once represented Trump’s signature trade achievement has become the target of his own administration’s renegotiation push, a reversal that surprised few close observers given his public comments over the past year, but still hit markets and trade groups hard. 

Which Industries Face the Most Exposure 

Automotive supply chains are the biggest concern for trade lawyers right now. In addition to the 75% North American content rule, manufacturers must also meet labor-value requirements, which means some vehicle production must happen in plants that pay workers above a certain wage. This rule is meant to prevent the kind of low-cost relocation that increased the trade deficit in the first place. 

Agriculture is the next big area of concern. Canadian dairy quotas have long been a sticking point in talks and remain unresolved as the review period begins. American dairy producers are pushing for firmer market access. Mexican steel exports are also under review, as US officials worry about Chinese steel entering North America through Mexico. 

Technology and digital trade rules make things even more complicated. The USMCA’s digital trade chapter, which was among the most advanced in any trade deal when it was adopted, covers cross-border data flows and intellectual property protections. Companies from Silicon Valley to Guadalajara rely on these rules every day. Changing them without harming current business models will require thoughtful negotiation among all three countries. 

What Executives Should Watch Next 

The US and Mexico will resume talks later this month, with a third round of negotiations planned as part of the ongoing review. Canada has had some early discussions but has not yet started formal talks with the US, so Ottawa is a bit behind Mexico City in the process. 

This does not mean the agreement will fall apart. Trade deals have survived much tougher renegotiations, and Mexico’s top trade negotiator has said he hopes each annual review will help resolve more issues. Still, hope is not a strategy, and companies with investments in cross-border manufacturing now have a real reason to make backup plans they did not need before. 

The next important moment is just a few weeks away. How the talks with Mexico go this month will give the first real sign of whether the ten-year review will lead to a stronger trade deal or the gradual breakup of North America’s biggest economic partnership.

Source: abc News 

Brussels, Belgium 

After eight years and three courts, Europe’s top judges have ended Google’s longest-running antitrust fight, and the company lost. The ECJ Google ruling confirms what Brussels regulators said in 2018: Google built a walled garden around Android, and competitors paid the price. The Google EU antitrust fine, now set at €4.1 billion ($4.67 billion), is the largest antitrust penalty the European Union has ever imposed. There are no more options for Google to appeal. 

For the Alphabet, the fine is small compared to its market value of over $2 trillion. But the real impact is the legal precedent. This ruling sends a message to regulators around the world that platform dominance based on exclusive contracts will not hold up in court, no matter how long a company can fight. 

What the Court of Justice of the European Union Actually Decided 

The Court of Justice of the European Union, the EU’s highest court, rejected the last appeal from Google and its parent company. This decision upholds the General Court’s 2022 judgment, which supported the European Commission’s 2018 finding: Google misused its power in mobile operating systems by making phone makers pre-install Google Search and Chrome to get access to the Play Store. This is now the final and unchangeable ruling on Google’s Android pre-installation ruling. 

The mechanics of the abuse were direct, even if the legal fight over them was not. Samsung, Xiaomi, and dozens of smaller manufacturers wanted access to the Play Store, since an Android phone without Google’s app marketplace is commercially unsellable in most of Europe. Google made that access conditional. Manufacturers had to bundle Search and Chrome, set them as defaults, and in some cases accept revenue-sharing arrangements that discouraged them from pre-installing rival browsers or search tools at all. The European Commission concluded this arrangement locked out competitors before they ever had a chance to compete for consumer attention on the home screen. 

Google’s defense rested on a simple claim: bundling made phones better, cheaper, and more secure, and consumers were free to download alternatives afterward. A company spokesperson maintained that Android has expanded consumer choice and supported thousands of businesses across the continent and argued the judgment does not adequately account for the company’s investment in keeping the platform open. The court did not find that argument persuasive enough to overturn the underlying finding. The Alphabet Android fine 2026 decision shows a straightforward judicial view: default settings are not neutral, and a company that controls the default controls the market. 

The Long Road From Brussels to Luxembourg 

The timeline shows why this case acted as a symbol of how slowly antitrust enforcement can move against a company with Google’s resources. The European Commission made its first decision in July 2018, setting the fine at €4.34 billion. Google appealed to the General Court, which mostly agreed with the Commission in 2022 but reduced the fine to €4.1 billion. Google then made one last appeal to the Court of Justice of the European Union, but that failed on July 2, 2026, just as the Commission had expected almost ten years earlier. 

Taking eight years is not unusual in EU competition law, especially for companies big enough to litigate every available procedural avenue. What makes this case notable is less the duration and more finality. Google no further appeal is not a rhetorical flourish here — it is the literal legal status. There is no higher EU court, no other review body, and no more legal steps for Google to take. The fine, plus interest, must now be paid in full. 

Why This Matters Beyond the Balance Sheet 

This ruling is not an isolated event, and that should worry Alphabet’s board more than the payment itself. If you add this fine to the Commission’s 2017 shopping decision (€2.42 billion) and the 2019 AdSense decision (€1.49 billion), Google’s total EU antitrust bill is nearly €11 billion over roughly a decade. That figure represents EU antitrust Big Tech enforcement at its most sustained: three separate rulings, three different business areas, and one repeated finding that Google used its power in one market to reinforce its position in another. 

The financial impact did not finish with this ruling. Just one day earlier, on July 1, a Stockholm court delivered another setback. The Patent and Market Court ordered Google to pay Alphabet a $4.67 billion penalty, including a $1.97 billion damages award to PriceRunner, a price-comparison company owned by Klarna. This case, based on the Commission’s 2017 shopping-abuse decision, found that Google had pushed down independent comparison-shopping sites in search results for over a decade while promoting its own Google Shopping service. PriceRunner originally asked for nearly $8 billion, but the court awarded about a quarter of that amount. Still, it is the largest competition-law damages award in Swedish history. Google says it disagrees and is considering an appeal, and similar cases are moving forward in Britain, Germany, and Italy. 

Investors replied with minor concern, which is common for a company of this size facing such news. Alphabet’s shares fell about 1% after the announcement, suggesting the market does not view these payments as a serious threat to the company’s core business. Revenue from search advertising and cloud services is much larger than these fines. What worried investors more was the sign of future enforcement risks, not the payments themselves. 

The Digital Markets Act Is the Real Story Now 

Alphabet shareholders should pay more attention to the Digital Markets Act (DMA) than to the fine itself. The DMA gives Brussels a new way to enforce rules, one different from the approach used in this case. The Android decision took eight years and led to a single large fine. In contrast, the DMA establishes ongoing behavioral rules and allows penalties of up to 10% of global annual revenue for repeated violations. For a company as big as Alphabet, this could be much larger than all previous antitrust fines combined. 

The Commission has already said it plans to use the DMA more aggressively than the old antitrust process used in the Android case. Regulators are shifting from punishing companies after the fact to monitoring compliance in real time. This will change how Google designs Android, Search, and its advertising systems in Europe. A company that spent eight years fighting one fine now faces a system designed to avoid such long battles in the future. 

What Investors and Executives Should Watch Next 

For portfolio managers weighing what the EU Court of Justice’s Android ruling means for Alphabet investors in July 2026, the near-term financial impact is small. Alphabet has enough cash to pay both the €4.1 billion fine and the Klarna damages without affecting spending on AI or share buybacks. The headline about Google losing its final appeal and the $4.7 billion fine sounds dramatic, but it ends this chapter rather than creating new uncertainty in this case. 

The bigger question is about structure. Now, every major region has seen what happens when a platform company loses a long fight over control of default settings. Regulators in the UK and US who are looking at Google’s mobile and search practices will pay close attention to this result, and the logic behind the Android pre-installation decision may be used in cases outside the EU. Leaders at any company that controls a major distribution channel, like app stores, operating systems, or marketplaces, should see this ruling as an example of how courts draw the line between fair bundling and unfair blocking of competition. 

So far, Google has responded defensively, still arguing that Android’s openness helps both developers and consumers. This position is unlikely to change the legal result of a case that is already finished. However, it may affect how Google sets up its next round of platform agreements, as regulators—not courts—are now pushing for changes. The DMA is already raising these questions, and this time, Brussels does not plan to wait years for answers.

Source: Google loses fight over record $4.7 billion EU antitrust fine 

Austin, Texas. 

Wall Street expected 406,024 vehicles, but Tesla beat that by 74,000 units. The result was so strong that even optimistic analysts had to recheck their numbers. 

Tesla’s Q2 2026 deliveries came in at 480,126 vehicles, a 25% jump from the same quarter last year and the best second quarter in the company’s history. This ends two years of annual sales declines, prompting some investors to question whether Tesla’s growth story was over. It wasn’t. Tesla delivered 480,000 vehicles from factories in Fremont, Austin, Berlin, and Shanghai in just one quarter; this isn’t a minor deviation from expectations. It signals a real shift in demand that surprised Wall Street. 

After spending 2024 and 2025 answering questions about whether the electric vehicle market had peaked, Tesla’s latest quarter feels like a strong response. In the first quarter of this year, Tesla delivered 358,023 vehicles, slightly below expectations and prompting some skepticism. Just three months later, deliveries jumped 34%, changing the story around the stock as summer began. For two years, executives explained lower annual numbers by citing model updates, changing incentives, and weaker demand in key markets. This time, those explanations weren’t necessary. 

Breaking Down the TSLA Delivery Beat 

The TSLA delivery beat was not a small surprise. Tesla’s own forecast was 406,024 deliveries, and Street Account’s independent estimate was 406,600. Even the most optimistic analysts, like those at Goldman Sachs and Barclays, predicted between 418,000 and 420,000 units. Tesla exceeded all of these expectations. 

Tesla’s Q2 2026 deliveries of 480,126 beat Wall Street’s 406,000 estimate what investors need to know starts with the mechanics of the number itself. Tesla produced 451,758 vehicles during the quarter but delivered 480,126, indicating the company sold about 28,000 vehicles from existing inventory rather than adding to stockpiles. This is important because selling out of inventory shows strong demand, unlike companies that rely on discounts to clear unsold cars. 

The Model Mix 

Tesla Model Y Model 3 deliveries accounted for the overwhelming majority of the total, with 467,762 units delivered to customers. The other 12,364 deliveries were from the Model S, Model X, and Cybertruck, which are now grouped as “other models” after the Model S and Model X lines ended this quarter. In short, mass-market vehicles drove the results. Production for these models was 442,936 units, so Tesla sold more Model 3 and Model Y cars than it built during the quarter. This suggests that the recent updates to these models are attracting buyers who had been waiting for new features and a better range. 

Why the Stock Fell Anyway 

Here’s where the story gets interesting, and where casual observers tend to get confused. Tesla delivery beat July 2, 2026 stock reaction TSLA falls despite blowout numbers explained is the headline that actually mattered to traders on Thursday morning. Despite obliterating consensus estimates, TSLA shares dropped as much as 7.3% in the session following the report. 

The reason for the stock drop follows a common Wall Street pattern: buy the rumor, sell the news. Tesla shares had already climbed more than 13% in the four days before the delivery report, as investors expected good news. Once the numbers were out, there was little new upside, so many investors took profits. Adding to the pressure, investor Michael Burry revealed a new short position in Tesla at $416 just before the report, which brought more negative sentiment despite the positive delivery results. By Thursday morning, shares were trading near $396, even though the business news was clearly good. 

Cox Automotive had predicted a 20% drop in Tesla’s US sales for the quarter, which makes the delivery beat even more impressive. If US sales fell as expected most of the growth must have come from international markets, especially Europe and China, where Tesla has worked hard to maintain its market share against local competitors. 

The BYD Problem Hasn’t Gone Away 

No discussion of Tesla’s delivery numbers is complete without addressing BYD vs Tesla EV competition, and the picture here is mixed. BYD delivered 557,090 fully electric vehicles in the same quarter, so it remains ahead of Tesla in global battery-electric sales. However, the trends are different: BYD’s electric deliveries dropped about 8% from last year, while Tesla’s rose 25%. The gap between the two has shrunk from over 220,000 units a year ago to about 77,000 now. Tesla hasn’t overtaken BYD yet, but it is catching up, and this trend is more important to long-term investors than just one quarter’s results. 

Energy Storage Quietly Outperforms 

While vehicle deliveries dominated headlines, Tesla’s energy division posted its own quiet win. Tesla energy storage GWh deployments reached 13.5 gigawatt-hours for the quarter, up from 9.6 GWh a year earlier and slightly ahead of the 13.3 GWh analysts had penciled in. The business, regularly overshadowed by automotive results, continues compounding at a pace that could eventually rival the car division’s contribution to revenue. 

Growth in Tesla’s energy business got a boost in April when SpaceX bought $269 million worth of Tesla Megapacks for its Memphis data center. This deal shows how Elon Musk’s companies are working together on infrastructure. As data centers expand to support AI, they need reliable, high-capacity power storage, and Tesla’s Megapacks are well positioned to meet that demand, no matter what happens with car sales. 

What Comes Next 

The delivery number is just the start. Tesla’s Q2 2026 earnings on July 22 will provide full financial details, including gross margins, regulatory credit revenue, and operating income. These numbers will show whether the delivery surge leads to real profits or just reflects aggressive pricing to clear inventory. Investors will also look for updates on Cybercab production, the Optimus robotics program, and the progress of Tesla’s Robotaxi rollout. These factors are now more important to the company’s future than just quarterly car sales. 

Prediction markets for TSLA are almost evenly divided between a $450 bull case and a $360 bear case as the earnings date nears. This shows that there is still considerable debate about Tesla’s value, even after a strong quarter. The delivery number settled one question, but the earnings report on July 22 will raise new ones. Now, the market will focus less on how many cars were sold and more on how much profit those sales generated.

Source: Tesla stock sinks 7% despite strong deliveries report, posting worst day in nearly a year 

Washington, DC 

Fifty-seven thousand. That was the total net gain in American jobs last month, a figure so far below Wall Street’s expectations that traders quickly changed their September strategies. The June jobs report 2026 landed at less than half of what economists had penciled in, and the shockwaves moved through bond desks faster than the ink dried on the release. Nonfarm payrolls in June figures from the Bureau of Labor Statistics showed employers added just 57,000 positions, badly missing the 110,000-to-115,000 range forecasters had expected. It snapped a three-month run of upside surprises and forced a hard reset in how investors read the US economy’s June jobs story. 

After a spring where many believed hiring was picking up again, Thursday’s report was a sharp reality check. 

A Streak Breaks, And The Fine Print Gets Worse 

For three months in a row, job growth beat expectations, creating a sense that the economy was strong. That changed in June. The 57,000 new jobs not only missed the forecast but barely stayed above the 12-month average of about 36,000 jobs per month. This suggests that the strong numbers earlier this year may have simply pulled jobs forward, rather than showing real momentum. 

The disappointing news wasn’t just about June. Updates to April and May also made the earlier numbers look weaker. April’s job count was lowered by 31,000, and May’s by 43,000, for a total of 74,000 fewer jobs than first reported. This shows that early job reports are often just rough estimates. 

Looking at different sectors, the results were mixed. Professional and business services added 36,000 jobs, social assistance added 25,000, and health care grew by 22,000, though more slowly than before. Leisure and hospitality lost 61,000 jobs because seasonal hiring was weaker than normal. Most other big industries, such as construction, manufacturing, retail, and transportation, saw little change. 

Unemployment Rate 4.2: Progress Or Illusion? 

At first glance, the 4.2% unemployment rate looks like good news, down from 4.3% in May. But a closer look shows the improvement isn’t as positive as it seems. The drop happened because fewer people were looking for work, not because more people found jobs. The labor force participation rate fell to 61.5%, its lowest since March 2021, and the employment-population ratio also declined. Economists call it an artificial improvement when the unemployment rate falls because people leave the workforce instead of getting hired, and that’s what happened here. Household survey data showed an even bigger problem: over half a million fewer people reported being employed, even though the jobless rate went down. 

This is the main issue with the labor market slowdown in 2026: the headline number looks steady, but the details underneath is much weaker. 

What It Means For The Fed’s Next Move 

Markets reacted quickly to the news, adjusting their expectations for interest rate changes. The CME Fed Watch tool showed the chance of a rate move by September dropped from 65% before the report to 50% just minutes after it came out. Treasury yields fell, especially on the two-year note, as traders concluded the Federal Reserve has less reason to raise rates soon. 

This change is important because it happened less than a day after Fed Chair Kevin Warsh spoke more calmly about inflation. At a central banking forum in Portugal, Warsh told his audience that Kevin Warsh inflation comments centered on encouraging progress, stating plainly that inflation risks have eased in recent weeks. He tied part of that improvement to lower energy costs following progress toward a ceasefire between the United States and Iran, but he also warned that prices remain higher than before the conflict. As usual, Warsh avoided making promises about future actions. He repeated that the central bank will rely on data and that policymakers will discuss their following steps at the forthcoming meeting. 

Put those two data points together — a softening labor market and a Fed chair already signaling comfort with the inflation trajectory — and the Fed rate hike probability calculus shifts meaningfully. Weaker job growth typically reduces the case for tightening, since a cooling labor market tends to ease wage pressure over time, one of the inputs the Fed watches most closely when assessing inflation risk. 

Reading The Market Signal 

For investors making decisions based on the jobs report, the connection is simple: weaker jobs data means less pressure on the Fed to raise rates, which usually lowers bond yields and makes it easier for segments like technology to grow. That’s what happened on Thursday morning. Bond yields dropped, and interest-rate-sensitive stocks got a boost as traders saw a longer wait for tighter policy. 

Of course, this doesn’t mean the Fed will definitely keep rates steady in September. One weak month, even with lower revisions, usually isn’t enough to decide policy by itself. But it does change the conversation. Now, the Fed has to balance a slowing job market with Warsh’s comments about lower inflation risks, and together these don’t clearly support raising rates. 

Anyone searching for context on “June 2026 jobs report 57000 payrolls miss what it means for Fed rate hikes explained” is really asking what markets asked on Thursday: does slower hiring give the economy more time before interest rates go up again? Based on price action, traders believe the answer is yes, at least for now. Those digging into “why June 2026 nonfarm payrolls missed the forecast and what happens to interest rates” will find the answer sits less in any single data point and more on how the Fed balances a weaker job market with its view that inflation is improving. 

The Road To August 

The next big update comes in early August, when the July jobs report will show if June’s weak numbers were just a blip or the start of a longer slowdown. By then, Fed officials will also have more data on inflation, energy prices linked to the Iran ceasefire, and consumer spending to consider before their next meeting. Markets will keep changing as new information comes out. If July’s report shows continued weakness, the argument for the Fed to pause rate hikes will get stronger. If the numbers bounce back, Thursday’s rally in rate-sensitive stocks might not last. Either way, the job market has now become the main focus for investors, more so than inflation—a sign of where we are in the economic cycle.

Source: Economy U.S. job creation cools in June with payrolls growth of just 57,000 

Washington, DC 

The federal government has given itself sixty days to decide which artificial intelligence systems could pose a national security threat. Now, federal agencies are working quickly to figure out what happens next before the deadline arrives. 

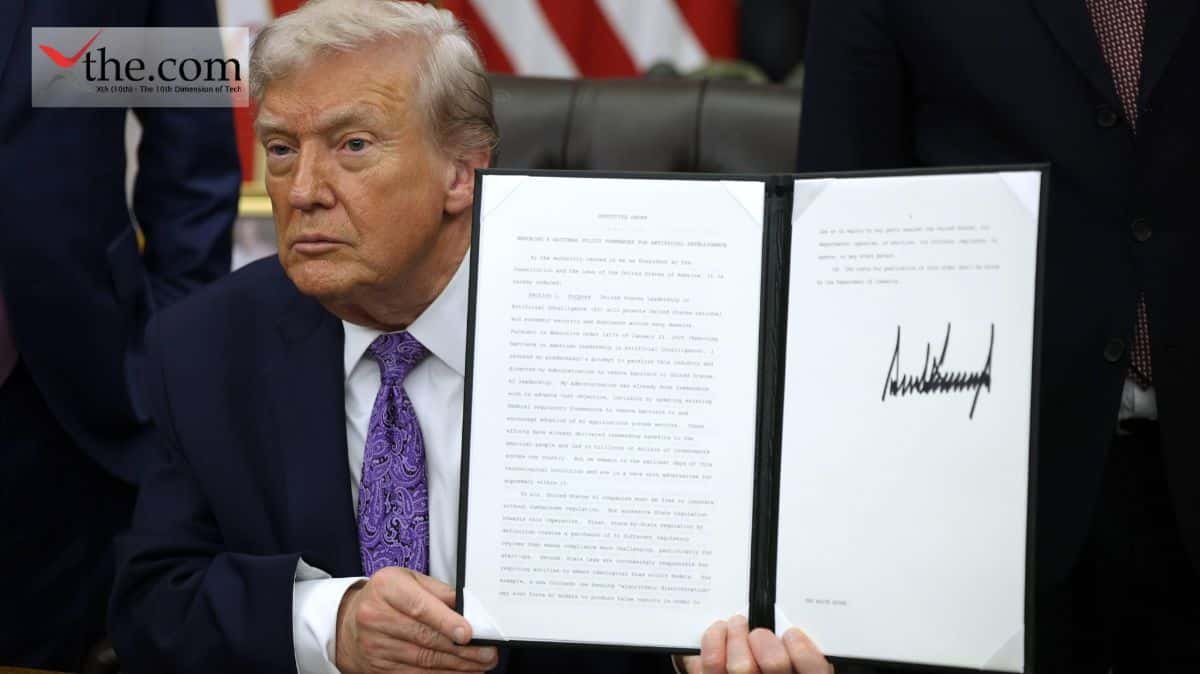
On June 2, 2026, President Trump signed the Trump AI executive order, officially called “Promoting Advanced Artificial Intelligence Innovation and Security.” For the first time, this order gives the National Security Agency a formal role in reviewing commercial AI systems before they are released to the public. This constitutes a notable change for an administration that spent its first year reducing AI oversight, and it is a shift worth examining. 

Why the NSA Now Sits at the Center of AI Policy 

The order’s most consequential provision establishes NSA frontier model review as a coordinated function shared among the NSA, the Treasury Department, and the Cybersecurity and Infrastructure Security Agency. These three bodies must jointly complete a classified benchmarking process that determines whether a given AI system meets the threshold for a covered frontier model designation. That designation is not cosmetic. Models that clear the bar become subject to a government review window before they ship to customers. 

This is a major change. In the past, CISA and the National Institute of Standards and Technology led federal AI cybersecurity efforts. Now, putting the NSA—an agency known for intelligence and code-breaking, not consumer software—at the center shows the White House sees advanced AI as a national security asset, similar to weapons technology. A senior policy attorney at a Washington law firm said this alteration could change which agencies have long-term authority over AI, even if the current framework is described as voluntary. 

What the AI Voluntary Pre-Release Framework Actually Requires 

The order tells agencies to design an AI voluntary pre-release framework within 60 days of signing, placing the deadline for early August 2026. With this system, developers can work with the government to see if their model qualifies as a covered frontier model. If it does, the developer may give the government access to the model for up to 30 days before releasing it to partners. 

Earlier drafts suggested a 90-day access window, but the final order reduced this to 30 days after debates among national security advocates and those concerned about slowing US AI progress. The order does not require mandatory licensing or preclearance, a point the White House has emphasized to avoid appearing too restrictive. However, once the government selects “trusted partners” for early access to a covered model, it still has major influence over when the model is released, even without formal veto power. 

For readers tracking the mechanics closely, this is the Trump AI executive order NSA cybersecurity review frontier models July 2026 deadline explained in its simplest form: benchmarking criteria first, frontier designation second, voluntary access window third, and a functioning clearinghouse running in parallel. 

Building the AI Cybersecurity Clearinghouse 

In addition to the review process, the order requires an AI cybersecurity clearinghouse to be up and running within 60 days. This clearinghouse will serve as a central place for sharing AI vulnerability data, threat intelligence, and defensive tools between government and industry. It is designed specifically for AI-related risks, unlike older cyber-threat-sharing programs that were not designed for generative models or autonomous agents. 

The CISA AI clearinghouse is key to this effort, coordinating submissions and sending useful threat data to critical infrastructure operators. Utilities, banks, and hospitals—sectors already facing AI-driven phishing and automated attacks—could benefit the most if the clearinghouse works as planned. Its success depends on having enough staff, and the order also tells the Office of Personnel Management to expand cybersecurity hiring through the U.S. Tech Force program. This suggests that finding skilled people, not just writing policy, may be the biggest challenge. 

What This Means for OpenAI, Anthropic, and Google 

The executive order does not refer to any companies by name. However, people in Silicon Valley know the frontier model rules are aimed at OpenAI, Anthropic, and Google. These companies now have a new, though voluntary, process to follow before releasing their most advanced systems to commercial partners. This makes AI model cybersecurity in 2026 a real compliance issue, not simply a policy discussion. Engineering teams working on large-scale models must now plan for a possible 30-day government review before launch. 

Some in the industry will see this as a manageable delay. For companies used to months of internal safety testing, a 30-day wait before launching a major model is inconvenient but not critical. Others are more cautious about the “trusted associate” selection, since the order does not explain how the government will decide who gets early access. This lack of clarity may be the order’s biggest risk. Several law firms following the rollout have pointed out that this part is most likely to cause disputes once the framework is in place. 

Anyone advising a frontier lab right now is effectively answering what OpenAI, Anthropic, and Google must do by July 31, 2026, as a practical checklist: monitor forthcoming CISA guidance, draft technical documents for the classified benchmarking process, and make sure product roadmaps are flexible in case a model is labeled as covered. 

The Bigger Shift Nobody Is Naming Directly 

If you look beyond the deadlines and specialized terms, a bigger trend appears. In its first term, this White House was known for cutting rules, speeding up deployment, and keeping government involvement low. The June 2026 order does not completely change that approach, but it does make things more complex. Now, innovation and national security are being combined under one oversight system, with the NSA playing a new and important role. 

Whether this system becomes a lasting system or just another little-used compliance step will depend on what happens after the 60-day deadline. If the benchmarking process yields a clear definition of a covered frontier model, other agencies may use this approach to evaluate future technologies beyond AI. But if it gets stuck because of classification issues or industry resistance, the order might be seen as more symbolic than practical. Either way, the outcome will affect how the next wave of powerful AI models is released, and every major lab is paying close attention. 

Source: PROMOTING ADVANCED ARTIFICIAL INTELLIGENCE INNOVATION AND SECURITY 

San Francisco, California. 

For the first time in Silicon Valley, the two most valuable private AI companies quietly asked regulators for permission to go public in the same month. Just seven days apart, both filed the paperwork that begins the process for a stock market debut, but neither has said when trading will actually start. 

This is the story behind the OpenAI S-1 filing and the Anthropic S-1 confidential submission. Two events that arrived within a week of each other in June 2026 and quickly became the main focus of this year’s AI IPO 2026 cycle. Anthropic filed first, submitting its draft registration to the SEC on June 1. OpenAI followed on June 8, confirming the news in a blog post before reporters could break it themselves. Investors searching for “OpenAI Anthropic both filed confidential S-1 IPO June 2026 what investors need to know” are really asking a single question: which of these two giants get to Wall Street first, and does it matter which one wins that race? 

Two Filings, Two Very Different Postures 

Anthropic’s filing came five days after it closed a $65 billion Series H round, a raise that pushed the company’s valuation to roughly $965 billion. The Anthropic $965 billion valuation of IPO narrative has become shorthand across trading desks for a company that, according to reporting cited by Fortune, is closing in on its first quarterly profit. That detail is important more than it might seem. Confidential S-1 filings do not disclose financials publicly, but the private fundraising math around Anthropic has consistently pointed toward a business burning less cash relative to revenue than its chief rival. 

OpenAI is taking a different approach. The company was last valued at $852 billion in March 2026, but CEO Sam Altman reportedly set his sights well above that figure before ringing the opening bell. The OpenAI $1 trillion IPO target is not a rumor plucked from thin air; it reflects Altman’s stated preference to list only when the company can command a valuation north of $1 trillion, according to people familiar with internal discussions, as reported by Bloomberg. OpenAI’s announcement made the uncertainty clear: “We have not decided on timing yet,” the company said, noting that some strategies are easier to carry out as a private company. 

Why the Delay Talk Started 

A June 26 Bloomberg report changed how analysts perceive the timing. Advisors close to OpenAI are encouraging the company to wait until 2027 to go public rather than in late 2026. Their reasoning is based on what happened with SpaceX: after its IPO at $135 a share on June 11, the stock soared to $225, then lost about a third of its gains as excitement faded. For OpenAI’s board, this kind of volatility is a real example of how quickly market mood can shift when a major tech company starts trading. 

That is the context behind the OpenAI IPO 2027 to delay conversation now circulating among bankers. Anthropic, on the other hand, has not shown the same hesitation. Its confidential filing started a regulatory review that, for a company of this scale, typically runs three to six months, putting a public prospectus release around September 2026 and a first trade date potentially in October. Anyone tracking the phrase “OpenAI IPO delayed 2027 Anthropic IPO timeline what retail investors need to prepare for” is watching two clocks that no longer run at the same speed. Anthropic also overcame a political hurdle in mid-June when the Trump administration said it no longer considers the company a national security concern, removing a regulatory barrier. 

The AI Company IPO Pipeline Gets Crowded 

Anthropic and OpenAI are not filing into an empty market. SpaceX’s own S-1 landed just weeks earlier and set the mood for the entire AI company IPO pipeline heading into the back half of 2026. When a company worth close to $2 trillion opens its doors to public markets, every other name in the hallway feels pressure to move through them while capital and attention are still available. Investment bankers describe the current moment as the most consequential stretch of technology listings since the dot-com era, with Goldman Sachs and Morgan Stanley advising both OpenAI and Anthropic on their respective processes. 

There is more at stake than just being first. The company that lists first sets the valuation standard the other will have to match or beat. Some analysts think that if Anthropic goes public before OpenAI, it could reduce investor interest in OpenAI, especially since their profitability paths differ. Others believe a strong Anthropic debut could actually help OpenAI by proving that frontier AI is a solid investment, making its own IPO easier to price. 

The IP Question Neither Company Can Avoid 

Another issue has made both companies’ filings more complicated than investors expected. On June 10, Anthropic sent a letter to the Senate Banking Committee accusing people linked to Alibaba’s Qwen AI lab of carrying out the largest known distillation attack on its models. They claimed about 28.8 million exchanges with Claude happened through nearly 25,000 fake accounts between April 22 and June 5. Distillation means training a weaker model using the outputs of a stronger one, copying its abilities without copying its code. Two days after the letter, the Commerce Department restricted global access to Anthropic’s newest models, Fable 5 and Mythos 5, because of national security concerns. The company had to disable them worldwide, but restored access at the start of July. 

The episode illustrates a risk factor that any S-1 from a frontier AI lab now has to address directly: how durable is the underlying model IP once it becomes a company’s primary balance sheet asset? Public market investors evaluating either the OpenAI S-1 filing or the Anthropic S-1 confidential draft will want clear answers on how each company defends its model weights and training data against extraction attempts, and how much that defense costs on an ongoing basis. It is no longer a footnote. It is a line item. 

What Retail Investors Can Do Right Now 

Neither company has declared a ticker, exchange, or price range yet, since confidential filings stay private until closer to the IPO. This means retail investors have few direct options right now, but there are still things to watch. How SpaceX’s stock performs in the coming weeks can preview how the market might treat new tech IPOs once early volatility passes. Looking at each company’s public comments on profitability—especially since Anthropic has shared more about its path to positive earnings than OpenAI—can help investors judge which company’s finances are stronger. It’s also important to follow the distillation dispute and related legislation, as new laws could change how AI intellectual property is protected and affect company valuations. 

The two filings came just a week apart, but the companies are now on different paths. One is moving quickly toward an October debut with a strong story about profitability. The other is deciding if it should wait for a higher valuation. Retail investors don’t have to choose sides yet. They should keep an eye on the calendar, since the next update—a public prospectus, a roadshow date, or a price range—could come from either company at any time. 

Source: IPO Radar: Open AI, Kunlunxin, Bending Spoons, Lime