New York, New York 

It took just fifteen trading days for Elon Musk’s rocket company to go from its initial public offering to inclusion in one of the most closely tracked benchmarks on Wall Street. On July 7, SpaceX’s Nasdaq-100 July 7 becomes official, marking the fastest move from IPO to index membership. If you have a 401(k), brokerage account, or retirement fund linked to the Nasdaq-100, you’ll soon have a stake in a rocket company, even if you didn’t plan for it. 

Nasdaq confirmed SpaceX’s addition after the markets closed on June 26. This announcement changed expectations for how quickly a huge company can join a benchmark that supports over $800 billion in assets. The SPCX index entry skips the usual waiting period and doesn’t require profitability. It only needs the fifteenth trading day and a market value that most new listings never reach. 

Why The Fast Track Exists 

Nasdaq changed its eligibility rules starting May 1, 2026, to accommodate very large IPOs. Previously, companies needed months of trading history to be considered. Now, the new rule removes that requirement for companies that rank among the top Nasdaq-listed firms by market value in their first weeks of trading. 

SpaceX didn’t just meet the new standard—it far surpassed it. When the company debuted on June 12, it raised about $75 billion, making it the largest IPO ever and giving it a value of over $1.7 trillion. Later, its shares pushed the valuation above $2 trillion, a level that made the SpaceX fastest index addition almost a formality rather than a debate. Few companies in market history have entered public trading already large enough to be in a top-100 benchmark. SpaceX managed it before most investors even finished reading the prospectus. 

What “Fast-Track” Actually Changes 

There was a reason for the old waiting period. Index committees wanted proof that a stock could trade readily before millions of retirement dollars depended on it. The new rule assumes that being huge is enough. The idea is that a company worth trillion already acts like a major index member from the start. Some people disagree, and the debate about whether size alone is enough will likely continue as SpaceX joins the Nasdaq-100. 

The Money Behind the Move 

Here’s what matters most for everyday investors: when a stock joins the Nasdaq-100, every fund that tracks the index must buy shares, based on the new weighting, no matter what the managers think about the company’s valuation. That obligation produces QQQ mandatory buying on a scale most single stocks never see in their first month. 

Analysts estimate the resulting SpaceX passive fund inflows at approximately $4.3 billion, driven almost entirely by funds tracking the Nasdaq-100 rather than by active investors making a bullish bet. Add in FTSE Russell’s separate move to fold SpaceX into its U.S. equity indexes, and the combined mechanical demand climbs higher still. None of this buying shows a judgment about SpaceX’s rocket business, its Starlink network, or its balance sheet. It reflects arithmetic. A fund that aims to track the Nasdaq-100 must hold the same securities as the Nasdaq-100. 

QQQ ETF SpaceX: What Passive Investors Should Know 

The Invesco QQQ Trust is the largest and most visible product tracking the Nasdaq-100, and its portfolio managers must adjust holdings ahead of the July 7 change. For QQQ ETF SpaceX exposure, the practical effect is automatically credited to a shareholder’s account. Nobody has to click a buy order. Nobody has to research the company’s cash burn or its satellite backlog. Owning shares of QQQ, or any fund benchmarked to the same index, now means owning a slice of SpaceX by default. 

There’s an important detail many investors miss. Even though SpaceX is highly valued, it won’t be a major part of the index. The Nasdaq-100 uses a special weighting system to prevent any one company from controlling it, so SpaceX will likely have a weighting below 1%. In other words, this trillion-dollar company will make up only a small part of the index, even if it’s making big headlines. 

The Case For Caution: SPCX Lock-Up Expiry 

Every silver lining in this story comes with a matching cloud, and for SpaceX it arrives in the form of the standard post-IPO lock-up period. Early investors, employees, and company insiders typically face a window during which they cannot sell shares. That window is scheduled to expire in late July, just weeks after the Nasdaq-100 inclusion takes effect. The looming SPCX lock-up expiry means a large pool of previously restricted shares could reach the open market at almost the same moment that mechanical index buying tapers off. 

Here’s how it could play out: Passive funds buy shares before and around July 7 to match the new index. This buying supports the stock for a while, but it doesn’t last. Once the funds finish rebalancing, most of the forced demand disappears. If insiders start selling their shares after the lock-up ends, the stock could face selling pressure just as the extra support disappears. Morningstar’s Michael Field has already questioned the stock’s value, and the mix of less index buying and more insider shares could be a real concern. 

What Investors Are Actually Buying 

If you ignore the technical details, the main question is still the same: is SpaceX really worth its current price? Last year, the company generated about $18.67 billion in revenue but lost nearly $4.9 billion, putting its valuation well above that of most profitable tech companies. Investors looking for advice on “SpaceX SPCX joins Nasdaq-100 July 7 what QQQ ETF investors need to know now” will see the same point in almost every analyst report: being added to the index creates demand, but it doesn’t guarantee value. 

For those trying to understand “SpaceX Nasdaq-100 inclusion $22 billion passive fund buying explained July 2026,” analysts usually estimate about $4.3 billion in passive buying from Nasdaq-100 rebalancing alone. If you add up all index providers, the total could be much higher, depending on which benchmarks are included. No matter how you count it, the amount of forced buying is huge for a company that’s only been trading for three weeks. 

Long-term investors are dealing with an old problem in a new form. Joining a major index brings headlines, forced buying, and short-term price boosts. But that doesn’t answer whether Starlink’s growth, rocket launches, or SpaceX’s path to profits really justify a value over $2 trillion. History shows that many large IPOs over the past decade dropped below their first-week highs once initial buying faded, and company fundamentals became more important. 

Gazing Forward 

July 7 will be a milestone, not a final answer. The forced buying from index inclusion will end quickly, but questions about share supply, valuation, and SpaceX’s future plans will last much longer. Investors who know the difference between automatic demand and real trust in the company will be best prepared when the excitement fades and SpaceX’s actual performance matters most.
Source: SpaceX Will Join the Nasdaq-100 on July 7. Here’s What a $10,000 Investment Could Be Worth in December, According to History. 

New York, New York 

A stock can gain a bullish Wall Street call and still fall 6% before lunch. That is precisely what happened to Space Exploration Systems this week, and the disconnect says as much about how investors are pricing artificial intelligence as it does about rockets or satellites. Wedbush Securities set the SpaceX Wedbush price target at $190 per share, initiating coverage with an SPCX outperform rating that frames the company less as a launch provider and more as an emerging force in computing infrastructure. The call, delivered by Dan Ives, SpaceX analyst and Wedbush’s Global Head of Tech Research, landed on CNBC’s Fast Money with a line that immediately reframed the stock’s investment case: SpaceX, Ives said, is “much more of an AI play” than a traditional space company. 

This new perspective is important because SpaceX has acted like a meme stock since its record-breaking IPO on June 12. The stock opened at $150, jumped to $225, then dropped back down to around $170. Wedbush’s coverage came during this period of big swings, and the market didn’t react positively at first. SPCX shares fell about 6% in morning trading, even though Wedbush presented one of the boldest valuation cases on Wall Street this year. 

The SpaceX AI Hyperscaler Thesis, Explained 

Ives based his analysis on SpaceX’s vertically integrated platform, which covers connectivity, launches, and AI infrastructure. He called SpaceX “one of the most differentiated assets within the tech market,” using this phrase to set it apart from other aerospace companies. The main idea behind the SpaceX AI hyperscaler thesis is simple: SpaceX already owns the satellites, ground infrastructure, and more of the computing power that AI companies need. It can rent out this capacity just like Amazon Web Services or Microsoft Azure rent out server time. 

SpaceX isn’t a typical hyperscaler like AWS or Google Cloud. It doesn’t offer a full self-service software stack, managed databases, or the customer tools those platforms have. Instead, it provides raw computing power, mainly through projects like Elon Musk’s Colossus data center in Memphis, Tennessee, which he calls a “gigafactory of compute.” SpaceX has already made deals with Alphabet, Anthropic, and Reflection AI to supply computing power for their AI work. These contracts alone bring in nearly $2 billion each month. Ives estimates that the wider AI and compute business is signing deals worth about $28 billion a year, which would have seemed impossible for a rocket company just two years ago. 

Even with all the attention on artificial intelligence, SpaceX Starlink revenue remains the foundation of Wedbush’s valuation model. The satellite broadband unit counts approximately 12 million subscribers as of early June, with average revenue per user near $66 across its enterprise and consumer customer base. That translates to nearly $19.3 billion in revenue and a gross margin of nearly 49%, based on Wedbush’s numbers. Ives said Starlink is “still in the early innings of penetrating the global telecom and broadband market,” pointing out that SpaceX has less than 1% of that market so far, even as it keeps growing its direct-to-device cellular service. 

In contrast, SpaceX’s launch operations act more as a strategic benefit than a big source of profit. Falcon 9 leads the global commercial launch market, and Starship aims to lower costs by carrying more satellites at once. However, most launches are used to deploy SpaceX’s own Starlink equipment rather than to sell to other companies. That’s why the launch business adds much less to Wedbush’s valuation model than Starlink or the AI compute segment. 

How Wedbush Arrived at the SPCX $190 Target 

Wedbush’s $190 target for SPCX is based on a sum-of-the-parts valuation using projected 2028 revenue. The numbers are bold by any measure. The model suggests an enterprise value of about $2.48 trillion, which would make SpaceX one of the world’s biggest companies even before its AI compute business fully develops. Ives gave the highest valuation to the AI and compute segment, saying it supports the long-term bullish outlook, even though it currently brings in less revenue than Starlink. 

Ives was open about the risks in these numbers. SpaceX reported a large adjusted EBITDA loss last quarter and will likely have another before the AI business becomes profitable. He described these losses as “an investment cycle, not a business losing ground,” which will be important for investors to evaluate in the next quarters. Ives also pointed out that the entire AI-compute plan hinges on Starship operating reliably at scale, since much of the expected computing power relies on SpaceX deploying hardware and infrastructure faster than in the past. Even Wedbush’s own figures show the stock trading at a price-to-sales ratio above 115, which assumes years of perfect execution. 

Why Nasdaq Inclusion Adds a New Catalyst 

Aside from the valuation discussion, there’s another factor helping SpaceX. The company is set to join the Nasdaq-100 index before markets open on SpaceX Nasdaq-100 July 7, an unusually fast inclusion for a company that just went public three weeks ago. JPMorgan estimates that this move may attract about $4.3 billion in buying from index-tracking funds, regardless of what analysts think of the stock’s fundamentals. This kind of automatic demand can push a stock higher in the short term, even if investors are still debating its long-term value. That’s why some traders are watching July 7 closely, regardless of Wedbush’s price target. 

What Investors Should Watch Next 

For investors trying to understand the stock’s ups and downs, the key question is which part of the business to trust first. Starlink provides steady, recurring revenue with clear numbers that can be tracked each quarter. The AI compute business could have much greater potential, but it has a shorter track record, and its success depends on meeting timelines that haven’t been tested at this scale before. Anyone reading about “Wedbush Dan Ives SpaceX $190 price target AI hyperscaler thesis explained July 2026” should realize that both the optimistic and pessimistic views are based on the same facts they just judge the risks differently. 

This uncertainty probably won’t go away soon. SpaceX’s pending earnings, the speed of building new Colossus-style data centers, and how often Starship launches will all test Wedbush’s 2028 predictions. For anyone searching “SpaceX SPCX outperform rating Wedbush what investors need to know before July 7 Nasdaq-100,” the quick answer is that joining the index creates short-term demand, but the long-term story depends on whether SpaceX can turn its satellite network into a real AI compute business, not just a side project. Wall Street has made its bet. Now, SpaceX must deliver the computing power, profit margins, and performance that a $2.48 trillion valuation requires.

Source: SpaceX is much more of an AI play, well-positioned to become major hyperscaler, says Wedbush’s Dan Ives 

Menlo Park, California 

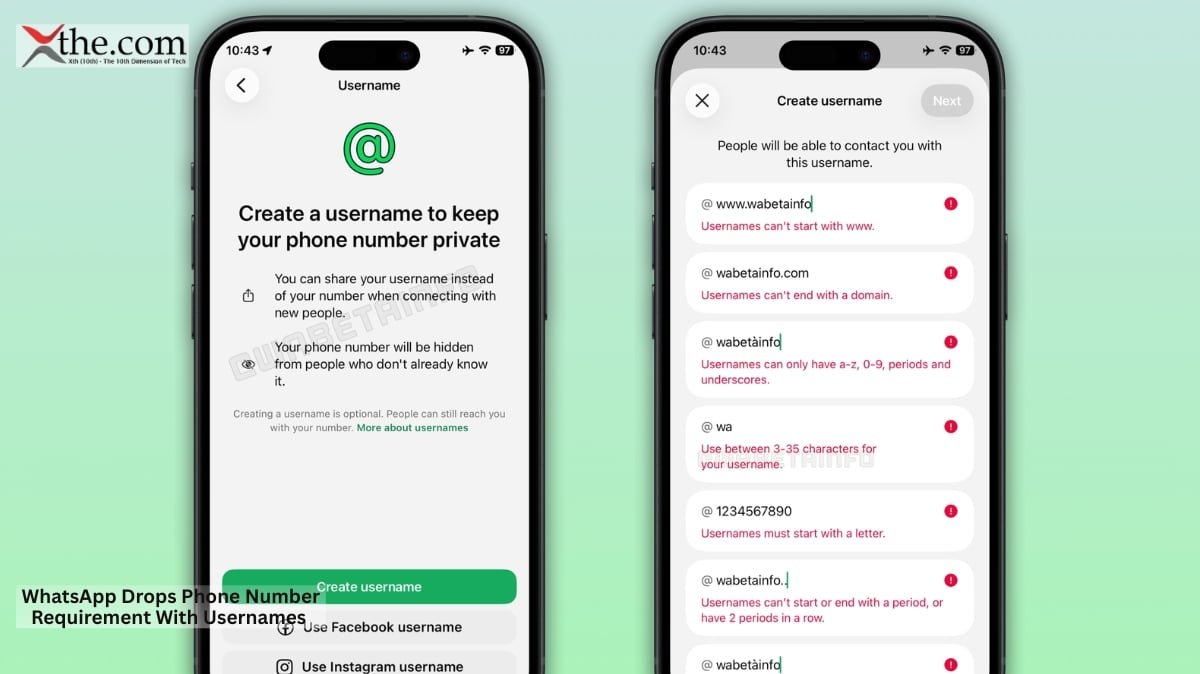
Until now, WhatsApp has always required a phone number to sign up. If you wanted to message a colleague, connect with a customer, or join a group, you had to share your mobile number. That is finally changing. With the new WhatsApp username feature and the latest WhatsApp privacy update, Meta WhatsApp 2026 will let users connect using usernames instead of phone numbers. This is a big change for the platform’s more than three billion users. 

This update solves a major privacy concern and gives creators, businesses, and regular users more control over their digital identities. 

WhatsApp Username Feature Denotes a Major Privacy Shift 

The arrival of the WhatsApp username feature represents one of the platform’s biggest identity changes since end-to-end encryption became standard. 

For years, every WhatsApp account was linked to a mobile number. This made verification easy, but it also meant users had to share personal contact details with anyone new. Freelancers, marketplace sellers, community moderators, customer support staff, and others often had to reveal their numbers to people outside their close circles. 

The latest WhatsApp privacy update changes that equation. 

Now, users can talk to each other using unique usernames instead of phone numbers. If someone knows your username, they can message you without seeing your mobile number. 

Meta designed this system to prioritize privacy over making users easy to find. 

Unlike other social platforms, WhatsApp will not have a public directory, searchable usernames, or recommendations. People must know your exact username to contact you. 

This limitation helps reduce spam, unwanted messages, and large-scale collection of user information. 

Why Meta WhatsApp 2026 Is Valuing User Privacy 

The username rollout demonstrates a broader strategy behind Meta WhatsApp 2026. 

Over the past decade, people’s expectations of personal privacy have changed significantly. Users now want messaging apps to keep their personal identity separate from public interactions. Other apps have shown that usernames are helpful, especially for creators, businesses, and online groups. 

The old WhatsApp model often made people choose between privacy and convenience. 

An online tutor had to reveal a private phone number. 

A nonprofit volunteer coordinating events shared personal contact details with hundreds of strangers. 

A marketplace seller risked ongoing spam after completing a single transaction. 

The new WhatsApp privacy update addresses those problems by providing users with an additional layer of identity between themselves and the public. 

For Meta, this is also a smart move as WhatsApp expands into areas such as commerce, customer service, payments, and creator engagement. 

WhatsApp No Phone Number Changes How People Connect 

One of the biggest implications is the arrival of WhatsApp-no-phone-number communication for everyday conversations. 

Before, you had to exchange mobile numbers to add someone, which meant your personal contact details were always visible. 

Now, the process is much simpler. 

Users can now share a username instead of a phone number when talking to customers, joining online communities, gaming groups, conferences, or working on short-term projects. 

That doesn’t eliminate phone numbers entirely. 

Phone numbers are still used for signing up, account verification, and account recovery. The key difference is users do not have to share them during normal conversations. 

This change is important for people who care about privacy. 

How WhatsApp Username Reservation Works 

Meta is beginning a staged rollout of **WhatsApp username reservation before the wider public launch expected later this year. 

Users who gain access can reserve a unique username through: 

  1. Settings 
  1. Account 
  1. Username 

The reservation process checks whether the username is available and complies with WhatsApp’s rules. 

Once approved, your username becomes the main identity you can share instead of your phone number. 

It is important to reserve your username early because each one must be unique on WhatsApp. 

As more people start using usernames, shorter or more memorable ones will become harder to get. 

Creators, entrepreneurs, consultants, and anyone with a public profile should try to claim their preferred username as soon as possible. 

Meta Privacy Features Go Beyond Encryption 

WhatsApp is known for end-to-end encryption, but Meta’s new privacy features go much further. 

Today, privacy is about more than just keeping messages secure. 

Protecting your identity is just as important. 

The new username system adds to existing features such as disappearing messages, encrypted backups, chat locks, privacy controls for profile photos, and options to hide your online status. 

All these Meta privacy features give users more control over who can read their messages and who can identify them. 

This shows how privacy risks have changed. Now, data exposure can happen even before a conversation begins. 

Creators and Businesses Receive a Valuable Advantage 

Meta also knows that having a consistent brand is important. 

Creators and small businesses could try to claim usernames that match their Instagram or Facebook accounts if those names are available. 

This consistency helps customers avoid confusion. 

For example, a photographer could use the same username on Instagram, Facebook, and WhatsApp. Instead of giving a personal phone number on ads, they can just share their branded username. 

Small businesses benefit similarly. 

Restaurants, consultants, local shops, fitness coaches, and freelancers can now communicate with customers without revealing employees’ phone numbers. 

For businesses already using Meta services, this change helps build brand recognition and makes it easier to connect with customers. 

WhatsApp 3 Billion Users Make This Rollout Significant 

The size of WhatsApp’s user base is important. 

With WhatsApp’s three billion users worldwide, even small updates can change how people communicate around the world. 

Unlike smaller messaging apps, WhatsApp is used for personal chats, family groups, business communication, customer support, education, healthcare, and international business. 

Adding usernames for WhatsApp’s three billion users will change how people think about digital identity on a huge scale. 

It also makes it easier for people to use WhatsApp for work, since they no longer have to share their private numbers. 

This added flexibility could lead to more people using WhatsApp for business and creative work. 

How to Reserve Your WhatsApp Username Without Sharing Your Phone Number June 2026 

Many users are already asking: “How to reserve your WhatsApp username without sharing your phone number June 2026”. 

The answer depends on whether your account has access to the feature yet. 

If you see the username option, go to Settings, select Account, and tap Username. Then pick an available username that complies with WhatsApp’s rules and complete the reservation. 

Once set up, your username is what you can share publicly instead of your phone number. 

If you do not see the option yet, the rollout is still in progress. Meta is giving access to more users over time and will make usernames available to everyone later this year. 

Keep checking for app updates and new features as the rollout continues. 

WhatsApp Username Feature Launch Date Privacy Update What Users Need to Do Right Now 

Interest continues growing around “WhatsApp username feature launch date privacy update what users need to do right now” as the rollout progresses. 

Right now, it is more important to prepare than to rush. 

Users should update WhatsApp, check Settings and Account for the username option, and consider which username they want to use long-term. 

Businesses should also review their Instagram and Facebook branding to reserve matching usernames, if possible. 

Since usernames are unique, having the same name across Meta services can help customers recognize and trust your brand. 

If you wait too long, your preferred username might be taken by the time the rollout is complete. 

A New Layer of Identity for the World’s Largest Messaging Platform 

The WhatsApp username feature is more than just a way to hide phone numbers. It changes how identity works on one of the world’s biggest messaging platforms. With the latest privacy update, Meta WhatsApp 2026 shows a strong commitment to granting users more control over who can contact them and what information they share. As usernames become the norm for WhatsApp’s three billion users, privacy will start before the first message is sent. This shift shows the direction digital communication is going in the future.

Source: WhatsApp Will Allow Users to Go by Usernames Instead of Phone Numbers, Closing a Privacy Blind Spot 

Santa Clara, California 

At the world’s most valuable company, free lunch is not a given. Former employees say this detail has made Nvidia’s workplace culture a hot topic in Silicon Valley. Two ex-staffers told Business Insider that while cafeteria meals are subsidized, they are not free. Coffee is complimentary, but some bottled drinks and café items are not. For a company worth over a trillion dollars, this approach is intentional. It sends a message, and the rest of the tech industry is starting to notice. What started as curiosity about a CEO’s habits is now seen as an early sign of a Big Tech perks rollback and a shift in how money is spent in the AI economy jobs market. 

The Jensen Huang Doctrine: No Frills, No Apologies 

Jensen Huang has never managed Nvidia with the goal of winning best-workplace awards. Former employees describe a Jensen Huang no-frills culture based on a clear idea: work and comfort are kept apart. One ex-employee said Huang believes in the “separation of pleasure and work.” Another mentioned that Nvidia wants people to focus on meaningful work, not stay in the office just for the snacks. There are no ping-pong tables or unlimited PTO slogans here. This is a chip company that surpassed Intel’s market value while still expecting employees to pay for their own lunch. 

This difference is important because Nvidia was never a minor startup cutting perks just to survive. The company could easily afford to build several fancy cafeterias if Huang wanted to, but he chooses not to. This decision stands out because it runs counter to the long-standing Silicon Valley belief that generous free-food budgets signal a company’s strength. 

Why a Trillion-Dollar Company Says No to Free Lunch 

What’s surprising is that Nvidia is being careful with perks while business is booming, not struggling. Most companies cut perks when revenue drops, but Nvidia is doing it as revenue grows. This shows their frugality is about priorities, not cost. They want to spend on technology, not snacks. Every dollar saved on perks can go toward new chip orders or data centers. In a field where computing power matters most, this choice looks smart, not odd. 

The Money Behind the Message 

The numbers show why Nvidia’s approach is catching on. Morgan Stanley estimates that US hyperscalers will spend over $800 billion on AI infrastructure spending in 2026 alone, about the same as what all non-tech S&P 500 companies spent last year. This is almost double the 2025 amount and three times what was spent in 2024. Morgan Stanley also raised its 2027 forecast from $951 billion to about $1.12 trillion, a 17 percent jump. Goldman Sachs, using a different method, predicts around $765 billion in AI spending for 2026 and warns that this could be an underestimate if spending continues to rise. 

Money tends to go where it can bring the best return, and right now that entails investing in chips, power, and data centers, not office perks that don’t help with AI training. When companies are approving huge increases in capital spending every quarter, cutting free lunch is an easy choice specially since Nvidia has shown it can attract talent without it. 

The Layoffs That Prove the Perk Era Is Over 

Some may think that one company’s cafeteria policy does not reflect the whole industry. But the layoff numbers tell a different story. Oracle reported in June that it cut its workforce by 13 percent over the past year, reducing headcount from 162,000 to 141,000. Oracle explained that adopting AI led to these job cuts, even as it invested billions in AI data centers, including a partnership with SoftBank. 

Meta made similar moves, cutting about 8,000 jobs, or 10 percent of its workforce, with recruiting and HR teams seeing the biggest reductions. CEO Mark Zuckerberg told staff that “success isn’t a given” in today’s climate, which sounded more like a warning than reassurance. Amazon also cut 16,000 corporate jobs in the first quarter, even as AWS grew by 24 percent, its fastest growth in over three years. Now, companies are growing while cutting jobs, unlike the 2022-2023 period, when layoffs were mostly due to overhiring. 

Silicon Valley Perks Ending, One Budget Line at a Time 

Put those three data points next to Nvidia’s cafeteria policy and a pattern snaps into focus. Silicon Valley perks ending is no longer a contrarian prediction; it is a documented trend backed by SEC filings and earnings calls. Companies are not simply trimming snack budgets. They are restructuring entire departments while redirecting freed-up capital toward compute, cooling systems, and power contracts.  

The Big Tech layoffs 2026 wave, tracked by outplacement firm Challenger, Gray & Christmas at roughly 97,000 cuts in May alone, the highest May total since 2020, is happening in tandem with record capital expenditure announcements. That combination, rising layoffs alongside rising capex, only makes sense if you accept that the money was never scarce. It was being reallocated. 

What This Means for Workers and Investors 

For employees, the main lesson is clear, even if it is not easy to accept. Judging tech jobs by perks like snack walls or nap pods is becoming outdated. Now, the focus is on pay and purpose, not office extras. New workers should look at jobs the way Nvidia encourages its staff to: by considering salary, equity, and the long-term value of the work, not whether there is kombucha on tap. 

For investors, the message is more positive. Companies that cut extra spending while still making record profits are showing financial discipline, not trouble. Nvidia’s strategy suggests that the companies most likely to succeed in the huge AI spending cycle are those that treat every expense, even coffee, as a choice between perks and computing power. Analysts should watch how quickly other companies follow Nvidia’s lead, not just how much they say they will spend. 

The searchable framing that captures this shift best is simple: Nvidia’s no-frills workplace culture what it means for Big Tech employees and investors in 2026, is not a story about cheap coffee. It is a story about where trillion-dollar companies believe the next unit of value actually gets created, and it is not in the cafeteria line. 

The Road Ahead 

None of this means Silicon Valley is about to become austere across the board. Signing bonuses for top AI researchers remain enormous, and compensation packages for scarce technical talent continue to climb even as free lunch disappears for everyone else. What is changing is the middle tier of the workforce, the roles once cushioned by discretionary perks and now exposed to a market that rewards direct contribution to AI infrastructure over tenure or headcount. Companies watching Nvidia’s playbook are learning that culture itself can be repriced, and that the market has stopped punishing companies for saying so out loud. 

 The next earnings season will show whether more hyperscalers follow Oracle, Meta, and Amazon in trading perks and payroll for compute, or whether Nvidia remains the outlier that proved the model first. Given the capex trajectory already locked in through 2027, betting against the trend looks like the riskier position. Big Tech perks rollback AI spending era: what workers and investors need to know now may end up being less a forecast and more a description of what already happened.

Source: Nvidia’s workplace culture sends Big Tech a warning 

Washington, D.C. 

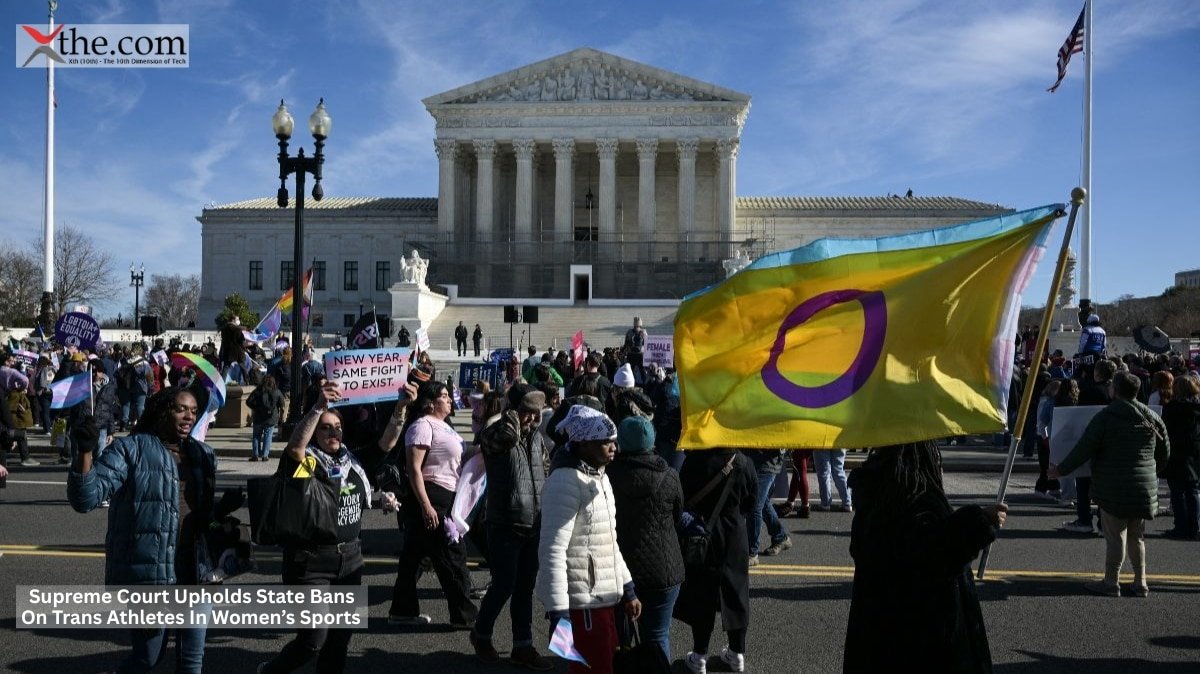
Fifteen-year-old Becky Pepper-Jackson wanted to run track with her middle school teammates in West Virginia. Six years, two federal circuit courts, and one Supreme Court docket later, the answer from the nation’s highest court is final: she cannot. On June 30, the Supreme Court’s trans athletes ruling closed a legal fight that has simmered since 2020, delivering a women’s sports ban upheld verdict that will reshape locker rooms, roster sheets, and state legislatures for years to come. 

The SCOTUS trans athlete case consolidated two disputes West Virginia v. B.P.J. and Little v. Hecox into a single opinion, and the numbers alone tell a story of a court sharply, if predictably, divided. 

The Decision, By the Numbers 

Justice Brett Kavanaugh wrote the majority opinion in the Supreme Court 6-3 ruling that found that neither Title IX nor the Equal Protection Clause of the Fourteenth Amendment stops states from limiting girls’ and women’s sports teams to students who are female at birth. The vote followed usual ideological lines, with the three liberal justices dissenting. 

At the center of the case sits the West Virginia Idaho trans athlete law framework: West Virginia’s House Bill 3293, passed in 2021, and Idaho’s Fairness in Women’s Sports Act, passed in 2020, were at the center. Both laws say that eligibility for girls’ teams is based on reproductive biology and genetics at birth, not gender identity. Idaho’s law kept Lindsay Hecox, a transgender student at Boise State University, from joining the women’s track and cross-country teams. West Virginia’s law stopped Pepper-Jackson, the state’s only openly transgender student-athlete, from running with her middle school team. 

Lower courts had ruled in favor of the athletes. Both the 4th Circuit and the Ninth Circuit found that the laws were unconstitutional discrimination. The Supreme Court reversed those decisions and sent the cases back for further action based on its opinion. In short, the states win on the main question of whether these bans are allowed. 

Why Sports, Specifically 

Kavanaugh’s opinion focused on the idea that sports are different from other public settings. The majority said that sports are usually separated by sex and are often a “zero-sum” situation, unlike jobs or classrooms in which equal treatment is the rule. This distinction limits how far the ruling goes. The court did not say transgender students can be excluded from bathrooms, dorms, or general school programs. The decision only applies to athletic competitions organized by biological sex. 

Justice Neil Gorsuch agreed with the majority and said that Title IX, written in 1972, used a strict biological definition of sex. Solicitor General Alan Hurst also argued in January that “sex is what matters in sports” because of physical differences like bone density and lung capacity. Justice Clarence Thomas, in a separate opinion, said that being transgender does not make someone part of a group that needs special legal protection. 

What the Ruling Does Not Settle 

Surprisingly, the court’s opinion is narrower than what either side wanted. The justices did not decide if transgender girls who have had puberty blockers or hormone therapy still have an advantage over cisgender girls. They called this an “ongoing medical and scientific debate” that should be handled by lawmakers and school officials, not judges. 

Importantly, the ruling allows state bans but does not require them. States and school districts with broad policies do not have to change as a result of this decision. This means that states with protections for transgender athletes can keep them in place, while about 27 states with existing restrictions can continue to enforce them, and more may follow. 

The Reaction From Advocates 

The ACLU trans sports case response arrived within hours of the opinion. Joshua Block, senior counsel for the ACLU’s LGBTQ & HIV Rights Project, said the outcome was heartbreaking for the two athletes involved. He also said the ACLU will keep arguing that giving transgender students equal opportunities does not harm other female athletes. Lawyers for Hecox and Pepper-Jackson kept their message simple throughout the case: let kids play. 

State officials in West Virginia and Idaho saw the ruling as support for the laws their legislatures passed before the courts got involved. For them, the case settles a question that has affected youth and college sports since Idaho’s 2020 law: whether states can set eligibility for women’s teams based on biological sex without breaking federal civil rights law. The answer, as of June 30, is yes. 

Legal analysts searching for “Supreme Court upholds Idaho West Virginia trans athlete ban women’s sports 2026” coverage in the hours after the decision found a flood of statements from both camps, reflecting how closely watched the case had become across state capitols, athletic conferences, and advocacy organizations nationwide. 

What Comes Next 

The ruling directly affects two states, but its impact is much wider. Over two dozen states already have similar laws, and many had court cases on hold while the Supreme Court decided these cases. In the coming weeks, expect quick moves to lift court blocks in some states and new legislative proposals in others that have not yet acted. 

For athletic associations, from state high school groups to the NCAA, the ruling gives the legal backing many needed before setting eligibility rules based on biological sex rather than case-by-case medical review. Anyone tracking “SCOTUS trans athlete ruling 6-3 explained West Virginia v BPJ” searches in coming days will likely find coverage focused on how quickly other states respond and how school districts handle the gap between state law and local inclusion policies. 

The court’s decision does not end the larger legal and cultural debate about transgender participation in public life. It exclusively addresses sports, leaving most questions about equal protection for transgender Americans available for future court cases. New legal battles over healthcare, workplace rights, and education outside of sports are already moving through lower courts, and both sides are still fighting.

Source: Supreme Court makes ruling on trans athletes in women’s sports 

Denver, Colorado. 

Diana DeGette has held her Denver congressional seat for nearly thirty years and had never trailed on election night until now. On Tuesday, early results in the Colorado Democratic primary 2026 showed a 29-year-old democratic socialist leading the fifteen-term incumbent, quickly catching the attention of Washington’s political class. The challenge to DeGette is not simply a protest vote. It has become a real contest for the 1st Congressional District and is now the clearest test of whether Colorado primary establishment power can survive a season of open revolt inside its own party. 

This result has significance far beyond Denver. Just a week earlier, Democratic incumbents in New York City were surprised when candidates supported by Mayor Zohran Mamdani did better than expected in several races. Now, Colorado’s primaries are the next chapter in that story. Strategists from both parties are asking whether New York was a one-time event or the start of a bigger fight between the party’s longtime leaders and its growing progressive wing. 

Why Colorado Became Ground Zero for Democratic Party Insurgent Candidates 

This election cycle saw three major statewide races, each featuring a well-known figure facing a challenger with a new message. Sen. Michael Bennet, once seen as the favorite to replace term-limited Gov. Jared Polis, lost his race for governor to Attorney General Phil Weiser after a campaign focused on who could oppose President Trump more strongly. Sen. John Hickenlooper narrowly beat state Sen. Julie Gonzales, a former Democratic Socialists of America member who portrayed the 74-year-old as a symbol of politics as usual. Meanwhile, in the 1st District, Melat Kiros nearly unseated DeGette. 

These races are part of a larger trend that researchers and campaign staff now call the rise of Democratic Party insurgent candidates. These challengers are usually younger, more progressive on economic issues, and openly question longtime incumbents in Washington. Melat Kiros is a clear example. She is a doctoral student and former lawyer who came to the U.S. from Ethiopia as a child. Her campaign argued that DeGette was no longer fighting hard enough for a district that is solidly Democratic, and that constituents could expect more from their representative. 

The Numbers Behind the Upset 

Signs of DeGette’s vulnerability appeared months before voting began. At the district assembly in April, she needed at least 30 percent of delegates’ support just to get on the primary ballot. She barely made it, with about 33 percent, finishing behind Kiros among the 235 delegates who voted. This was a sharp contrast to the nearly 465,000 voters eligible in the district’s Democratic primary. Once these warning signs became clear, outside money started pouring in. Justice Democrats spent over $500,000 to support Kiros, while several super PACs spent more than $2 million to back DeGette. This financial battle showed how seriously both sides took the challenge after what happened in New York. 

Zohran Mamdani Backed Candidates and the Shifting Playbook 

It is not a coincidence that DeGette’s allies invoked New York so often during the closing weeks of the campaign. Zohran Mamdani-backed candidates delivered a set of upset victories that convinced progressive organizers that a similar approach could work elsewhere, and Kiros deliberately embraced that comparison. She earned an endorsement from Sen. Bernie Sanders, built support from the Democratic Socialists of America, and drew energy from volunteers who described Mamdani’s mayoral win as proof that a disciplined, digitally savvy campaign could topple an entrenched incumbent even with a fraction of the establishment’s resources. 

Former state Rep. Alex Walia, who lost to DeGette in the 2022 primary, told local reporters that Kiros and her team are now part of a movement bigger than just one race. This idea sums up the thinking behind this year’s anti-establishment Democratic primary campaigns. Instead of running against Republicans, these candidates are challenging the belief that long-term incumbents automatically deserve to stay in office. Shanna Finch, a 38-year-old Sanders supporter who had become frustrated with politics, said she joined Denver’s Democratic Socialists of America after Mamdani’s win convinced her that local organizing could still have a national impact. 

How DeGette Tried to Respond 

Once DeGette realized the challenge was serious, she ran an active campaign. She pointed to her work as an impeachment manager during President Trump’s Senate trial after the January 6, 2021, Capitol riot. She also stressed her support for Medicare for All and for abolishing Immigration and Customs Enforcement, hoping to counter claims that she had moved to the political center. Her campaign got a big boost from outside spending after polls showed the race was close. The big question now is whether that money can overcome a strong grassroots movement. Other longtime House Democrats are watching closely, since a Kiros win would be only the second time in fifty years that a House incumbent lost a Colorado primary. 

What the Colorado Primary Establishment Battle Signals for November 

The stakes here go beyond bragging rights. Colorado’s 1st District is solidly Democratic, so the general election result was never really in question. What remains uncertain is whether primary voters across the country are ready to see seniority as a weakness rather than a strength. If Kiros wins, we could see more primary contests against sitting Democrats in safe districts over the next few years, especially where local organizers can point to Mamdani’s win and DeGette’s possible loss as examples. 

For readers trying to make sense of how this fits together, the short version is this: Colorado Democratic primaries 2026 establishment versus insurgent candidates explained in a concise phrase would read something like a party’s base testing whether it still wants the same leaders it elected a generation ago. The longer version, playing out precinct by precinct in Denver, involves generational turnover, frustration with congressional gridlock, and an authentic appetite among younger Democrats for candidates willing to say the party’s institutions have grown too comfortable. 

The Diana DeGette primary challenge Colorado progressive wing 2026 storyline will not end when the last ballots are counted. National Democratic strategists are already preparing memos about what a Kiros win or even a close call for DeGette means for incumbents in next year’s midterms. No matter the outcome, the message to Washington is clear: simply having seniority is no longer enough to guarantee a seat, and the party’s insurgent wing now has a playbook it plans to use again.

Source:  2026 Election Colorado’s primaries present the next test for the Democratic establishment 

New York, New York 

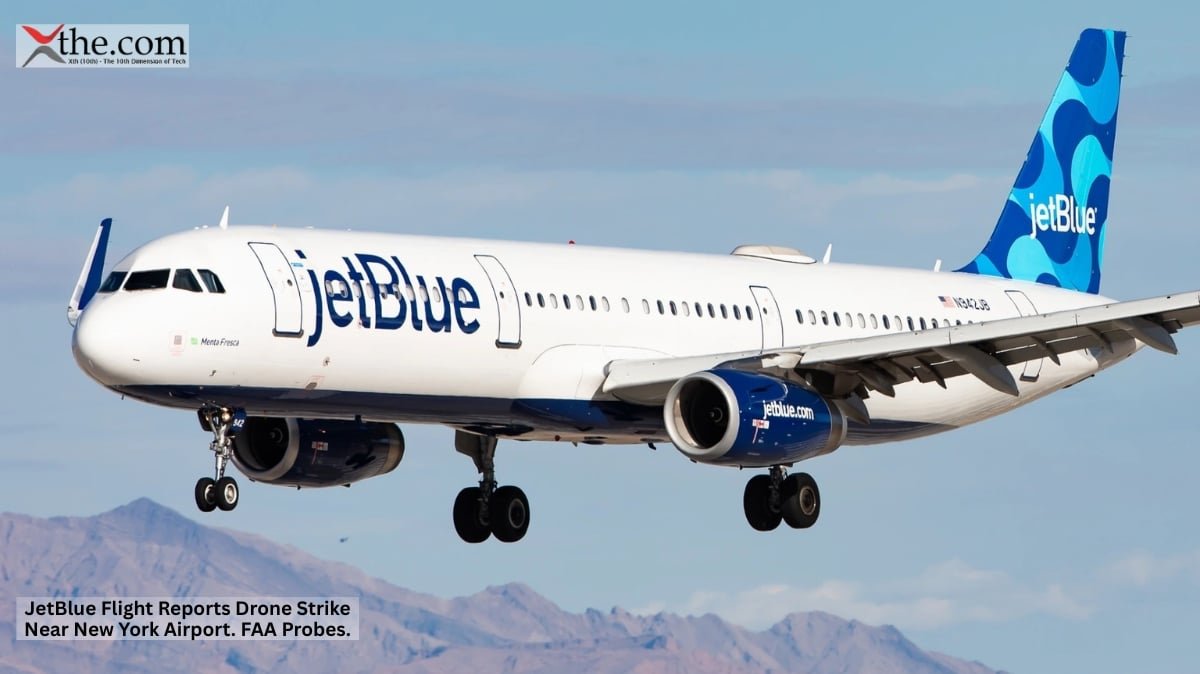
At 3,000 feet and closing on runway 13L, a JetBlue pilot radioed the tower with four words that airline safety officials had hoped never to hear on a live frequency: “We collided with a drone.” The JetBlue drone strike JFK incident, involving JetBlue Flight 948 drone contact during final approach on Monday morning, has triggered a formal FAA drone investigation and reopened a question the aviation industry has quietly dreaded for years. What happens when a piece of consumer electronics meets a 92-ton airliner in one of the busiest stretches of airspace in the country? 

The Airbus A321 was about ten to twelve miles from JFK, just north of Sea Bright, New Jersey, when the crew reported the impact. The pilot told air traffic control, “It hit us right above the cockpit,” according to audio from ATC.com. The plane landed safely at 7:25 a.m., thirty-nine minutes early. Passengers got off the plane as usual, and no one was injured. 

A Routine Landing, An Unusual Discovery 

After landing, JetBlue took the plane out of service for a precautionary inspection, which is standard whenever a crew reports a possible strike from a bird, hail, or anything unusual. Inspectors found no dents, debris, or clear evidence of a collision. This does not mean nothing happened; it means there was no obvious physical evidence during the initial check. 

JetBlue said in a statement, “The crew of JetBlue Flight 948 from Las Vegas to New York reported a possible drone encounter during the aircraft’s final approach into New York.” The airline added that safety is its top priority and it will work with investigators. The FAA confirmed the report and began its investigation the same day. This process will likely include checking radar data, air traffic recordings, and a closer inspection of the plane for any minor damage or residue that might have been missed at first glance. 

Why the FAA Drone Investigation Matters Beyond One Flight 

An unconfirmed strike would be a minor footnote if it were an isolated event. It is not. The FAA drone airspace investigation into Flight 948 lands atop a steadily climbing pile of close calls. The agency now gets over 100 reports of drones near airports each month, even though drones are not allowed near runways or approach paths. Just three days before the JetBlue incident, the crew of United Airlines Flight 1513 saw a drone while landing at Newark Liberty International Airport. That flight also landed safely. The FAA said the two events are unrelated, but having two incidents at major New York airports within a single week has sharpened scrutiny of how drone activity near JFK Airport in 2026 is tracked, deterred, and prosecuted. 

Later that same Monday, a helicopter pilot departing JFK for Manhattan reported nearly colliding with a large remote-controlled model airplane over Floyd Bennett Field. The FAA said this incident is not related to the JetBlue report. Still, these events show that low-altitude airspace over New York is now shared by commercial jets, medevac helicopters, hobbyist planes, and consumer drones, all using some of the world’s busiest approach paths. 

The Regulatory Gap Executives and Airport Operators Are Watching 

For airline leaders and regulators, the main issue is enforcement. Federal rules already ban drones within five miles of an airport unless the operator has special permission. Breaking these rules can lead to heavy fines or even jail. But these rules are hard to enforce if someone can launch a $300 drone from a beach parking lot without being noticed until a pilot reports a problem in the air. Drones, unlike birds, often do not appear on standard radar at low altitudes, and unlike wildlife strikes, drone incidents may involve intent, not just accidents. 

That distinction is precisely why the current commercial flight drone encounter pattern worries regulators more than birds ever did. A bird strike is an act of nature. A drone strike, confirmed or not, is an act of a person, and that person made a choice. Whether the January 2025 case is any guide is instructive here: a civilian drone punched a hole through the wing of a CL-415 “Super Scooper” battling wildfires near Los Angeles, forcing the aircraft out of service and leading federal prosecutors to file charges against the operator. That case proved drones can inflict real structural damage on aircraft, not simply theoretical risk. It also proved that operators can be identified and held accountable, provided investigators have enough data to trace the flight back to its source. 

What Investigators Will Look For Next 

The FAA’s review of Flight 948 will proceed in several steps simultaneously. One team will check radar and counter-drone detection data from the area around JFK, looking for anything that fits the pilot’s report. Another team will inspect the plane again, this time searching for small or hidden damage that might have been missed before. A third team will interview the flight crew, since what pilots say is important when there is little physical evidence. 

Aviation experts point out that “unconfirmed” does not mean “unfounded.” In the past, some suspected strikes turned out to be birds or minor mechanical issues mistaken for something else. Investigators are careful not to confirm a drone collision without solid evidence. However, ignoring the report would overlook both the pilot’s detailed account and the growing trend of drones entering restricted airspace near major airports. 

A Widening Test for Airspace Security 

The JetBlue Flight 948 reports drone encounter at JFK Airport FAA investigation 2026 episode is likely to become a reference point in a policy conversation that has been building for years: whether airports need dedicated counter-drone detection systems as standard infrastructure rather than an occasional pilot program. Several US airports have tested radar and radio-frequency detection technology that can flag unauthorized drones before they reach approach corridors, but deployment remains inconsistent and expensive. New York’s air traffic volume, and its proximity to dense residential coastline where a drone operator can launch unnoticed, make it a natural pressure point for that debate. 

For now, JetBlue Flight 948 has returned to normal scheduled service, the passengers who felt nothing more than a routine landing have gone about their week, and the FAA’s file on the incident remains open. What the agency concludes will shape more than one airline’s safety bulletin. It will inform how seriously federal regulators treat the drone strike commercial flight New York airport safety concern explained by this single Monday morning, and whether the next report from 3,000 feet ends the same way this one did, with no damage and no injuries, or with an outcome the industry has spent years trying to prevent.

Source: JetBlue flight reports drone strike during approach to New York airport: FAA 

Mountain View, California 

Meta, which spends tens of billions of dollars each year on artificial intelligence, could not get enough computing power from a competitor to run its own internal tools. This is the uncomfortable detail sitting at the center of a new report: Google caps Meta Gemini access after Meta requested more processing capacity than Google’s data centers could provide. The restriction, which began in March 2026, is a clear sign that Google’s compute capacity shortage is starting to change how the largest tech companies interact. 

The episode also illustrates a wider Meta AI cloud bottleneck in 2026 that goes beyond just one company’s plans. When even the biggest cloud providers cannot supply enough chips to their customers, the shortage becomes the main issue. 

What Happened Between Google and Meta 

In March 2026, Google told Meta it could not provide the full amount of computing power Meta wanted for Gemini due to infrastructure constraints. The Financial Times reported this on June 28, 2026, and other outlets such as Reuters, Bloomberg, and CNBC have since confirmed the story, citing sources familiar with the situation. 

The impact was real. The restrictions delayed several internal AI projects at Meta, leading the company to tell employees to use AI tokens more carefully and work more efficiently. Tokens measure how much AI computing power is used, so asking engineers to ration them is like telling a factory to slow down production because parts have not arrived. 

Why Meta Needed Gemini in the First Place 

It is ironic that Meta, which develops and promotes its own open-source Llama models, relied on a competitor’s infrastructure for some of its operations. Meta used Gemini for tasks such as content moderation, scam detection, and coding, and reportedly found it outperformed its own Llama models on some tasks. Other Google clients also faced limits, but Meta’s high demand made its situation especially challenging. As of late June 2026, the restrictions are still in effect. 

This link reveals something executives rarely admit: even a company as large as Meta cannot quickly build a replacement for a competitor’s better model. Buying access was faster than building it themselves, at least until that access was no longer available. 

The Roots of the Google Compute Capacity Shortage 

Google is not refusing business by choice. Demand has simply outpaced even its massive infrastructure investments. Google Cloud reached $20 billion in quarterly revenue for the first time in early 2026, growing 63% from the previous year. Still, capacity limits meant it could have grown even more, with its backlog almost doubling to about $460 billion. 

The backlog is more important than the revenue. A company can show strong growth but still fall behind on orders. Each dollar in the backlog means a customer is waiting for chips that have not yet been installed. 

Google Cloud AI Capacity Limits Go Public 

Google’s response has not been limited to quietly capping one customer’s account. On May 17, 2026, Google formalized broader Google Cloud AI capacity limits by imposing compute-based usage restrictions on Gemini Apps generally, meaning access now scales with available capacity rather than simply with how much a customer is willing to spend. In practical terms, unlimited access has effectively ended. Weekly quotas have replaced open-ended usage, a shift that touches consumers and enterprise partners alike, not just a single rival like Meta. 

Google’s response to the shortage is huge. The company plans to spend $180-$190 billion on infrastructure in 2026 and is leasing additional capacity from SpaceX and xAI. Earlier this month, Google also tried to raise $84.75 billion in equity to fund AI compute infrastructure and meet what it calls record customer demand. These amounts are so large they compare to the annual GDP of a mid-sized country, all just to keep up with requests for processing power. 

The Google SpaceX Cloud Deal and What It Signals 

One of the most notable responses to the shortage is the Google SpaceX cloud deal. Google agreed to pay about $920 million a month to lease computing capacity from Elon Musk’s SpaceX. Anthropic, which makes the Claude chatbot, made a similar deal with SpaceX the month before. Two years ago, a search engine company renting infrastructure from a rocket company might have seemed like a punchline. Now it reads as a rational hedge against a genuine AI infrastructure demand bottleneck that no single company can solve alone. 

The phrase “Google AI capacity crunch Meta SpaceX deal explained” sums up why these stories matter to readers. While Meta faced limits, Google was searching for extra capacity wherever it could, even from a company more famous for launching rockets than running servers. 

Meta’s Own Countermove 

Meta did not just accept the disruption. The company cut 8,000 jobs and moved 7,000 employees to new AI teams, while investing up to $135 billion in its own AI infrastructure. The Gemini restrictions sped up Meta’s move toward building its own models. This reshuffling shows Meta saw the March restrictions as a warning, not just a short-term problem. Depending on a competitor for important computing power, even for a short time, is a risk most companies want to avoid. 

There is another, less obvious limit besides the chip shortage. Meta’s new solar power agreements in Texas suggest that access to electricity, not just money or chips, is becoming the next big challenge for the AI industry. It is faster to make more silicon than to build a new power substation. This difference will become more important over the next eighteen months than most companies admit in their earnings calls. 

What This Means for the Broader AI Infrastructure Demand Bottleneck 

The Google-Meta situation is a case study, not a one-off event. Decentralized compute networks such as Render Network, Akash Network, and io.net are positioning themselves as alternatives to major cloud providers. They offer distributed GPU power from a global network of operators. While these networks will probably not replace Google Cloud for training the most advanced models, they could handle additional demand for jobs such as inference and fine-tuning. This overflow is exactly what the Google-Restricted Meta Gemini AI access compute shortage disrupted projects 2026headline points to: a system straining at the seams so hard that alternative supply chains suddenly look investable rather than speculative. 

Executives should see this as a planning signal, not only a story about two competitors. Any company relying on a single external AI provider now has proof that even Google, with one of the biggest budgets in history, cannot guarantee an unlimited supply whenever needed. 

The compute shortage will not be fixed by the end of the year. Building new data centers takes years, and demand for AI keeps growing every month. Companies that treat AI capacity as a key resource for diversification, just as they do with chips or raw materials, will be better prepared than those who assume there will always be enough supply. 

Source: https://techstartups.com/2026/06/29/top-tech-news-today-june-29-2026/ 

Washington, DC. 

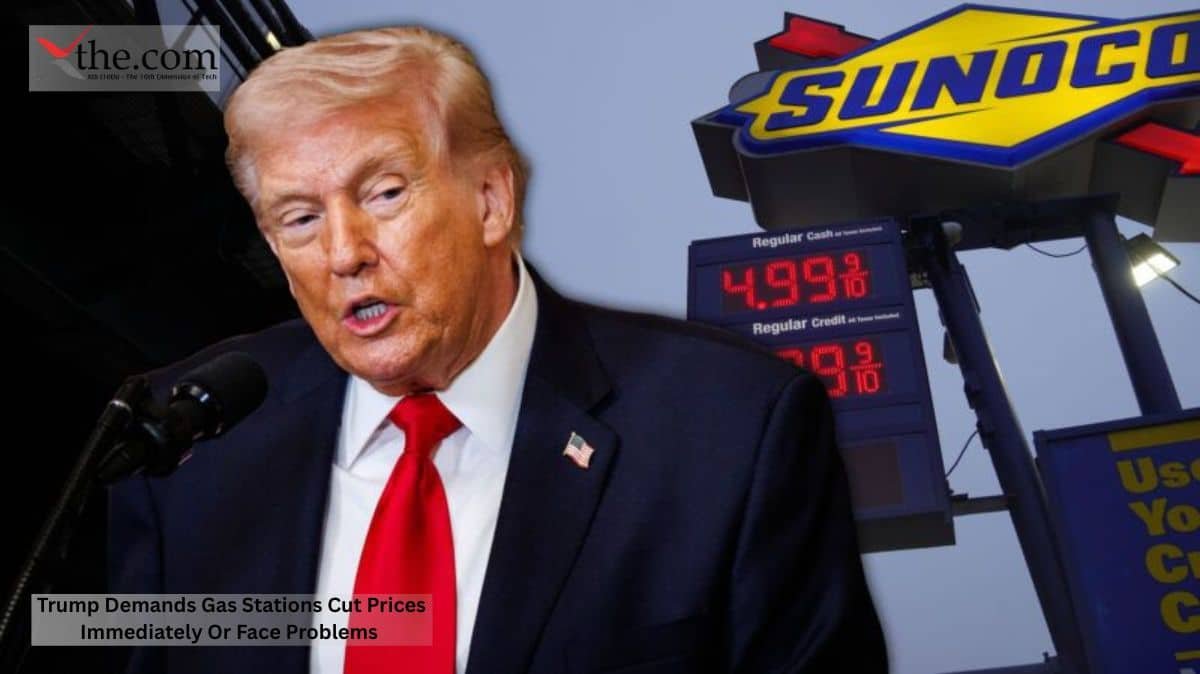
On June 29, the national average price for a gallon of regular gasoline was $3.86. That price was still too high for President Trump. In a nighttime post that sounded more like an ultimatum than a policy statement, President Trump issued a direct Trump gasoline prices demand to every fuel retailer in the country, ordering them to slash pump prices before Americans hit the road for the busiest travel weekend of the summer. 

Trump posted his message on Truth Social just after 7:30 p.m. Monday, making his point clear. “Gasoline Retailers must get their Prices down, IMMEDIATELY!” he wrote, also noting that oil was “now at $68 a Barrel, and heading south.” The Trump Truth Social gas-prices outburst was one of several posts this month, and it captured a president clearly frustrated that falling crude prices have not led to cheaper gas for voters ahead of the November midterms. 

A President Frustrated By The Pump 

Trump’s message was clear. “The Retailers must quickly react to this statement and do what they know is right. DROP YOUR PRICE FOR OUR GREAT AMERICAN PEOPLE!” he wrote that warning that “if Retailers don’t do this, big problems are imminent!” This was typical Trump: blunt, using capital letters for emphasis, and targeting an industry he thinks is moving too slowly. 

This was not the first time. A few days earlier, in another post, Trump accused major oil companies of gouging customers. “Those prices are dropping like a rock! In other words, customers are being ‘gouged,’” he wrote, adding that he had “instructed the DOJ to immediately start looking into this.” This is one of the clearest examples of Trump’s ” warn gas retailers rhetoric translating into an actual federal inquiry, with the Department of Justice now checking if energy companies are keeping prices high on purpose. 

Trump gave retailers a specific goal: $2.50 a gallon, a number he has mentioned before. This would be a big drop from current prices in most places. He especially called out California, where gas averages $5.45 per gallon, blaming the state’s fuel taxes rather than supply issues. “Soon the Tax will be higher than the Product itself, and the United States will not stand for it,” he wrote, describing California’s taxes as unfair to drivers instead of just a way to fund infrastructure. 

The Iran Conflict Behind The Numbers 

None of this unfolds in a vacuum. The fuel price Iran war impact is the real backdrop to the president’s frustration, and it is significant. The U.S.-Israeli conflict with Iran, which began in late February, caused shockwaves through global energy markets almost immediately. Iran responded to American and Israeli strikes by closing the Strait of Hormuz, the narrow waterway through which roughly one-fifth of the world’s oil supply travels. Brent crude, which had been trading in comfortable territory, briefly spiked above $100 a barrel as traders priced in the risk of a prolonged supply disruption. 

Consumers felt it fast. When the conflict began, gas averaged just $2.96 a gallon nationwide. Within weeks, that number climbed past $4.50 as refiners and distributors absorbed the shock and passed it along the supply chain. This is the essence of the gasoline price surge Iran conflict story: a geopolitical flashpoint thousands of miles from any American gas station, translating directly into higher costs at home. Data from the Bureau of Labor Statistics showed gasoline prices up 40.5% year-over-year through May 2026, and fuel oil up 58.9% in the same period. 

The Trump fuel-cost-statement campaign, then, is as much about political survival as it is about economic policy. A Gallup survey released last week found that 67% of respondents said recent gasoline price increases had caused financial hardship for themselves or their households. That is not a marginal grievance. It is a kitchen-table issue with the capacity to shape turnout in swing districts this fall, and Trump appears acutely aware of it. 

Why Prices Haven’t Caught Up Yet 

Energy experts say there is a built-in delay that Trump’s posts mostly ignore. Crude oil prices and gas prices at the pump do not change simultaneously. Refining, shipping, and distribution all take time, and retailers often sell fuel they bought at higher prices weeks ago. Chevron’s chief financial officer, Eimear Bonner, said in a CNBC interview on June 25 that “there is a lag between… reductions in oil prices and when that shows up at the pump,” but prices should even out as the market settles. 

The numbers are improving. AAA reported that the national average price has dropped for five weeks in a row, falling below $4 a gallon for the second week straight. This is a real break for drivers compared to the $4.51 average a month ago, though it is still higher than last year’s $3.19 average. Whether this is enough for a president who wants results “IMMEDIATELY” is another question. 

Wall Street is not sure the lower prices will last. A Reuters survey of 31 economists predicts Brent crude will average $84.50 a barrel in 2026, lower than last month’s forecast but still high by historical standards. Warren Patterson, ING’s head of commodities strategy, warned that the recovery could be fragile. “We have seen a significant tightening in global oil inventories since the start of the conflict, which leaves the market more vulnerable relative to the pre-war environment,” he wrote to clients. Hurricane season could also cause problems; past Energy Information Administration models show that storms could add 25 to 30 cents to a gallon of gas almost overnight. 

What Retailers Are Actually Facing 

Independent gas station owners, who usually make only a few cents per gallon, are caught between a president threatening “big problems” and a wholesale market that has not yet matched the drop in crude prices. Industry groups have often argued against claims of price gouging, saying that retail margins depend on supply contracts made weeks earlier, not on daily politics. Still, most station owners do not want to be linked to a DOJ investigation, so that fear alone might push them to cut prices faster than the economics would suggest. 

News coverage of this episode, with headlines like “Trump demands gas stations lower prices immediately Truth Social warning 2026,” has treated Trump’s post as both an economic message and a warning to an industry he thinks is dragging its feet. Explainer articles with titles like “gasoline prices surge after Iran conflict Trump retailer threat explained” have also tried to show how a war over nuclear issues ended up affecting what Americans pay at the pump, whether they drive a Chevy Silverado in Ohio or a Honda Civic in California. 

Where This Heads Next 

The next few weeks will show if presidential pressure can lower prices faster than the market usually allows. Independence Day travel is expected to push demand to record highs, which could slow the recent price drops reported by AAA. If crude oil stays around $68 a barrel and the ceasefire with Iran continues, retailers could lower prices on their own schedule, though $2.50 a gallon still looks unlikely. One thing is clear: gas prices will remain a big part of Trump’s economic message during the midterms, with each weekly AAA report serving as a scorecard for his campaign promise. 

Source: https://www.democracynow.org/2026/6/30/headlines 

Washington, DC. 

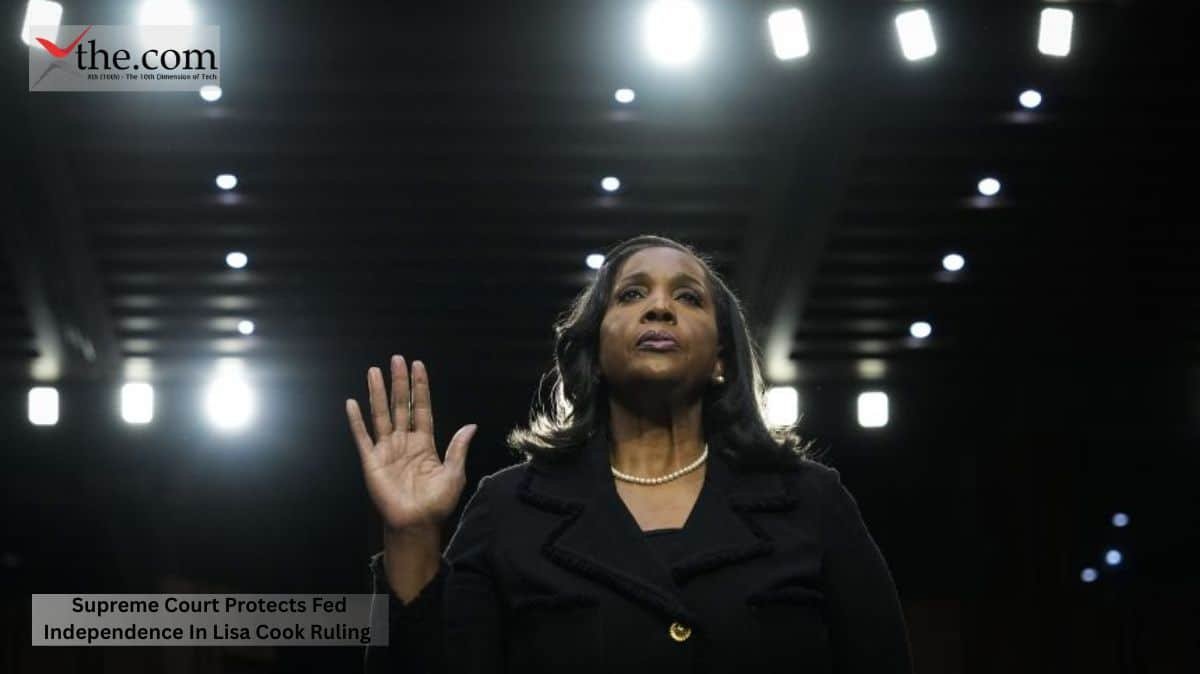
Nine months. That is how long Lisa Cook worked under the shadow of a presidential firing letter posted not to her inbox, but to a social media feed. On Monday, the wait ended, at least for now. The Supreme Court Lisa Cook ruling landed as a narrow but consequential check on presidential power, and it did something almost no one expected from this bench a year ago: it drew a hard line around the nation’s central bank and dared the executive branch to cross it. 

By a slim majority, the justices decided President Trump could not remove Cook from the Federal Reserve Board of Governors while her lawsuit is still moving through the lower courts. The decision is being read across Wall Street trading desks and law school seminar rooms alike as the clearest signal yet on Federal Reserve independence 2026, a phrase that a year ago would have sounded like an abstraction and now describes a live constitutional battle. 

What the SCOTUS Fed Governor Firing Case Actually Decided 

The SCOTUS Fed governor firing dispute, formally Trump v. Cook, never asked the justices to decide whether Cook committed the mortgage fraud Trump accused her of. It asked something narrower and, in some ways, more important: does a president get to fire a Federal Reserve governor unilaterally, without notice, without a hearing, and without judicial review? 

The Court said no. Federal Reserve governors serve fourteen-year terms and can only be removed “for cause,” a rule set by Congress in 1913 and confirmed again in 1935. Cook, whose term runs until 2038, argued she never got the notice or chance to respond that the law requires. Chief Justice John Roberts agreed, saying Cook deserved to know the charges against her and to defend herself before being removed. He called the decision narrow and sent the main dispute back to the district court, allowing Cook to stay on the Board for now. 

This difference is important. The Court did not say Trump can never remove Cook. It said he cannot remove her the way he tried—by posting a termination letter on Truth Social and acting as if no judge could review the decision. 

Humphrey’s Executor Supreme Court Precedent, Reworked Rather Than Repealed 

Anyone who has followed administrative law for the past five years has watched Humphrey’s Executor Supreme Courtprecedent take one hit after another. The 1935 decision shielded multimember independent agencies from at-will presidential firing, and this Court has spent recent terms chipping away at that shield, agency by agency. The same day it ruled for Cook, the Court ruled against Federal Trade Commission member Rebecca Slaughter, allowing her removal and confirming that Trump has broad power to fire leaders of most other independent agencies without cause. 

Why did the Fed get different treatment than the FTC? Roberts focused on the nature of the institution, not the person. He suggested that Humphrey’s Executor applies most strongly to agencies that lack significant executive power, such as today’s regulatory bodies. The Fed’s special structure, its role in monetary policy, and its long tradition of being separate from White House influence made it different. Some critics said this was an inconsistent standard, whereas supporters argued it was the only way to protect central bank independence with a Court that has otherwise given the president broad firing power. 

The SCOTUS 5-4 Fed Ruling and Its Immediate Fallout 

The SCOTUS 5-4 Fed ruling split the bench along familiar lines: six conservative-appointed justices decided the FTC case, but only a smaller group supported Cook in the Fed case. Legal experts noticed how close the decision was. Just one vote kept the Federal Reserve from facing the same outcome as the FTC and the National Labor Relations Board, whose leaders can now be removed by the president at any time. 

Federal Reserve Chair Jerome Powell, who was present at the oral arguments in January, called the Cook case the most important legal issue in the Fed’s 113-year history. He was not exaggerating. Every living former Fed chair and Treasury secretary from both parties, along with many top economists, signed a brief asking the Court to protect the central bank’s independence. Their strong concern came from a simple fear: if a president could fire a governor over a policy disagreement disguised as a fraud claim, there would be nothing to stop him from firing enough governors to control the Federal Open Market Committee, and interest rate decisions could become political promises. 

Trump Fed Governor Removal Blocked, But Not Forever 

It is important to be clear about what happened. The Trump Fed governor removal was blocked for now, but this is not a final decision. Cook keeps her job today because the government did not prove it would likely win, and because the Court said removed governors can stay in office while the trial proceeds. This is a temporary ruling, not a final answer. The case now returns to Judge Jia Cobb in Washington, DC, where the details of the mortgage fraud claims, first raised by Federal Housing Finance Agency Director Bill Pulte, will be fully examined. 

Pulte has not changed his position and, after the ruling, told reporters that he still expects Cook to be indicted. Cook’s lawyer, Abbe Lowell, said the decision brought some relief but is part of a larger effort to expand presidential power. Both sides agree on one thing: the fight is not over, and the district court’s decision on whether Trump had a valid reason will be just as important as Monday’s ruling. 

Searches for phrases such as “Supreme Court rules Lisa Cook can stay Federal Reserve job Trump removal blocked” jumped within hours of the decision. This shows that both markets and everyday savers quickly understood what was at stake. Mortgage rates, Treasury yields, and stock futures all depend on the idea that the Fed sets policy based on economic data, not politics. If that trust is lost, all these financial assets would start to reflect new risks. 

If you want a simple explanation of the “SCOTUS protects Fed independence 5-4 ruling explained 2026,” here it is: the central bank passed its first big test against presidential removal power, but only by a single vote, on a legal argument the Court itself called narrow, and the case is not over yet. 

What Comes Next for the Fed’s Independence 

The lower courts will now spend months, or maybe longer, working through the facts about Cook’s alleged actions before she joined the Board. Whatever they decide will likely be appealed to the Supreme Court, giving the justices another chance to determine how much protection the Federal Reserve really has from presidential control.rol. People inside boardrooms, on trading floors, and central bank watchers around the world will be paying close attention, because the main question goes beyond any one governor: can a president treat the Fed like any other agency, or does the institution that sets interest rates for 340 million Americans still have some independence from the White House? 

Source: https://www.npr.org/2026/06/29/nx-s1-5816232/supreme-court-ftc-independent-agencies-humphreys-executor