Washington, DC 

OpenAI’s newest model is available to just twenty companies. Anthropic’s top cybersecurity system is used by about 100 organizations, and none of them learned about it through a public announcement. Instead, access is decided privately in Washington, with each decision coming from Commerce Secretary Howard Lutnick. 

This setup may soon change. Officials are close to finishing the White House AI standards for 2026, which aim to replace the current case-by-case approach with a clear, repeatable process. OpenAI, Anthropic, and Google have been negotiating the voluntary AI model release framework for weeks, and sources say an announcement could come soon. For an industry that has spent months guessing Washington’s intentions, a published standard would finally provide some clarity. 

Why Washington Wants a Formal Rulebook 

For most of 2026, US AI governance has been made up as it goes. President Trump’s June 2 executive order allowed federal agencies to review advanced models for up to 30 days before release, but it did not specify who would receive early access or how companies could qualify. This has resulted in a series of one-off negotiations instead of a steady policy. OpenAI’s GPT-5.6 was released to just 20 vetted partners after the administration requested a delay to the public launch. Anthropic’s Mythos 5, its strongest cybersecurity model, was taken offline on June 12 due to national security concerns, then returned less than three weeks later for about 100 approved critical-infrastructure organizations, including some Fortune 500 companies. 

Neither company received a formal set of rules. Instead, they got a letter. 

This variation has frustrated both advocates and opponents of the administration. Dean Ball, who co-wrote the first AI Action Plan, said federal policy shifted from “implausibly libertarian to increasingly draconian and opaque” in just a few weeks. Lawmakers have made similar objections, arguing that appointees are choosing winners and losers without a published standard anyone can point to. A durable follow-through on Trump’s AI executive order, translated into an actual operating framework, would answer that criticism directly. 

The Shape of the Emerging Framework 

The OpenAI Anthropic government framework now taking shape is being built jointly by the Center for AI Standards and Innovation together with the National Security Agency, according to sources close to the talks. Technical teams from the main labs have met with officials nearly every day this week, focusing on two main questions: how long the review period should be, and what qualifies a model as “frontier.” 

These two questions are more important than they seem. If “frontier” is defined narrowly, only the most advanced systems would need to review, and smaller updates could launch as usual. If the definition is broad, many more releases would face a 30-day review, slowing down companies that rely on speed. Negotiators also plan to set clear US AI model benchmarks for security, so labs know exactly what they need to pass. Once a model meets that standard, it should get broader access than the current 20- or 100-partner limits, without further private negotiations. 

What Changes for the Labs 

For a reader trying to make sense of the US White House voluntary AI model release standards announcement in July 2026 explained in plain terms, the shift is really about predictability. Right now, a company finishes training a powerful model and then waits to learn, on a case-by-case basis, whether the government will let it ship. Under a published framework, the same company would know the review window, the benchmark it needs to clear, and the trusted partner process in advance. That does not guarantee faster releases. It guarantees releases that follow a known set of frontier AI release rules rather than a private phone call. 

Anthropic has publicly backed this approach. After the Mythos 5 incident, the company said it was “continuing to work with the government to expand access” and also called for a standard protocol to avoid another shutdown like the one in June. OpenAI has said its 20-partner limit for GPT-5.6 is only temporary, not a long-term plan. Google, which has faced fewer restrictions than the other two, has also joined the technical discussions, showing that the new rules are meant for the whole industry, not just one company. 

An Investor and Enterprise Lens 

What White House AI voluntary standards mean for OpenAI, Anthropic, and Google in 2026 is also a question enterprise buyers and investors are asking with increasing urgency. Companies building on frontier models have had no way to predict when a partner’s access might be granted, narrowed, or revoked entirely, as Anthropic’s customers learned when Mythos 5 access disappeared with roughly 90 minutes of notice. A published framework would give procurement teams and portfolio managers a fixed reference point: a known review period, a known benchmark standard, and a known process for expanding access once a model clears government scrutiny. That kind of clarity tends to matter as much to a chief information security officer weighing a multi-year contract as it does to an analyst pricing regulatory risk into an AI-adjacent stock. 

Still, the core tension in the policy remains. Shorter review periods foster innovation and speed, while longer ones encourage caution, especially for models with cybersecurity features like Mythos 5. That model had already found a 27-year-old bug in OpenBSD and a 16-year-old flaw in FFmpeg before its access was paused. The new framework will not remove this trade-off, but it will make clear where the line is and how often it might change. 

What to Watch Next 

If the standards are released as expected next week, the main question will be whether the new framework truly replaces the current case-by-case restrictions or just incorporates another layer of review. Companies on today’s limited-access lists will pay close attention to details on review timelines and the frontier threshold. Labs that adjust quickly to a set process, rather than ongoing negotiations, will likely lead to AI deployment for the rest of 2026. 

Source: US in talks with AI companies for voluntary model standards, FT reports 
Washington, D.C. 

Eighty thousand transactions over eight years have led to a $600 million settlement, the largest ever in the U.S. District of Rhode Island. This announcement stands out from typical compliance news. The Alibaba DOJ settlement ends an investigation that spanned two presidential administrations. Alibaba, one of the world’s largest e-commerce companies, admitted its platforms were used to sell products that federal drug laws are meant to keep out of the country. 

The Alibaba $600 million fine resolves allegations that the company and its U.S.-based payment processor, AUS Merchant Services, did not prevent merchants from selling and shipping illegal drugs, controlled substances, regulated chemicals, and pill-making equipment to buyers in the U.S. The size of the fine is striking. For investors and compliance officers, it shows how risks can quietly build over years before coming to light all at once. 

What the DOJ Actually Alleged 

Federal prosecutors said that merchants on Alibaba.com and AliExpress.com carried out about 80,000 illegal transactions from January 2016 to December 2024, moving goods with a combined gross merchandise value exceeding $200 million. The case revolves around AliExpress illegal drugs sold to U.S. buyers in violation of the Federal Food, Drug, and Cosmetic Act, as well as chemicals and equipment used to make counterfeit pills. Investigators went beyond paperwork, placing over 40 undercover orders for goods that regular patients or pharmacists could not buy without a prescription or license. 

In its statement of facts, Alibaba admitted that its internal controls were insufficient to prevent banned sellers from operating on its platforms. Some merchants used private messaging and third-party encrypted apps to avoid detection. Federal officials say this wasn’t only a one-time issue, but a pattern that lasted for years. 

The Structure of the Deal 

The DOJ non-prosecution agreement splits liability between two entities rather than one. Alibaba Group will pay a $125 million criminal penalty and forfeit an additional $200 million. Alibaba AUS Merchant Services AliPay, the U.S. payment processor formerly known as Alipay U.S. and connected to Ant Group, will pay an $85 million penalty and forfeit $190 million. Together, these payments total $600 million. AUS also admitted that its anti-money-laundering program was weak, allowing suspicious payments and questionable goods to pass through. 

Charles C. Calenda, the first assistant U.S. attorney for Rhode Island, said this is the largest monetary settlement in the district’s history. Assistant Attorney General Brett Shumate said the case shows that all online marketplaces, no matter where they are based, are expected to keep unapproved and dangerous foreign drugs off their platforms. Alibaba called the outcome a mutually satisfactory resolution reached with full cooperation and promised to set high standards for control in the future. The details of the compliance changes have not been shared publicly. 

Why This Lands Differently in July 2026 

Readers searching for the Alibaba $600 million DOJ settlement on illegal drug pharmaceutical sales, explained July 2026, are arriving at a story that does not exist in isolation. The settlement is the second major blow to Alibaba’s standing in Washington in barely a month, and the two stories, while legally unrelated, reinforce a single narrative: American regulators and American technology companies are both scrutinizing how Alibaba operates in U.S. markets and infrastructure. 

The first setback came from an unexpected source. Anthropic, the AI company behind the Claude models, told the U.S. Senate Banking Committee in a June 10 letter that people linked to Alibaba’s Qwen AI lab created about 25,000 fake accounts and made nearly 29 million interactions with Claude between April 22 and June 5. The Anthropic Alibaba AI theft allegation describes what researchers call distillation: using a stronger model at an industrial scale, harvesting its outputs, and training a cheaper rival system to copy the results. Anthropic said this campaign targeted Claude’s most valuable skills, such as advanced software engineering and intricate reasoning, and called it the largest attack of its kind, larger than three earlier campaigns by DeepSeek, Moonshot AI, and MiniMax combined. Alibaba has not openly addressed these claims, and no outside group has confirmed them. Anthropic also pointed out that the campaign continued even after the White House warned about distillation as a national security issue in April, suggesting the actions were intentional. 

The AI dispute and the drug settlement are separate issues, but together they set the stage for the end of the Alibaba pharmaceutical probe concluded, and they explain why Alibaba’s American depositary receipts have been under pressure for weeks, dropping more than 3% after the Anthropic news and falling again when the settlement was announced. 

What Investors and Consumers Should Watch 

For those considering the Alibaba AliExpress illegal drug sales US fine what investors and consumers need to know, three key questions beyond the headline number. First, will the $600 million penalty actually change how merchants behave on AliExpress, or is it just a cost that Alibaba can handle without changing its seller checks? Second, will Alibaba’s promised compliance changes be independently audited, or remain private between the company and federal prosecutors? Third, how much of the pressure on Alibaba’s stock comes from this settlement compared to the combined effects of trade policy, AI competition, and now pharmaceutical enforcement? 

People shopping on AliExpress or Alibaba.com probably will not see any immediate changes in search results or product listings. The settlement deals with past actions and requires future compliance improvements, but it does not set up a public timetable or include third-party checks that outsiders can follow. This lack of transparency, more than the size of the fine, will likely influence how regulators and shareholders view Alibaba’s next announcement, whether it concerns drugs, AI, or another issue. The company now holds the record for the largest settlement in Rhode Island federal court history, at a time when almost all its major U.S. regulatory and business relationships are under review. 

Source: Alibaba to pay US $600M to settle allegations it allowed illegal sales 

Santa Clara, California. 

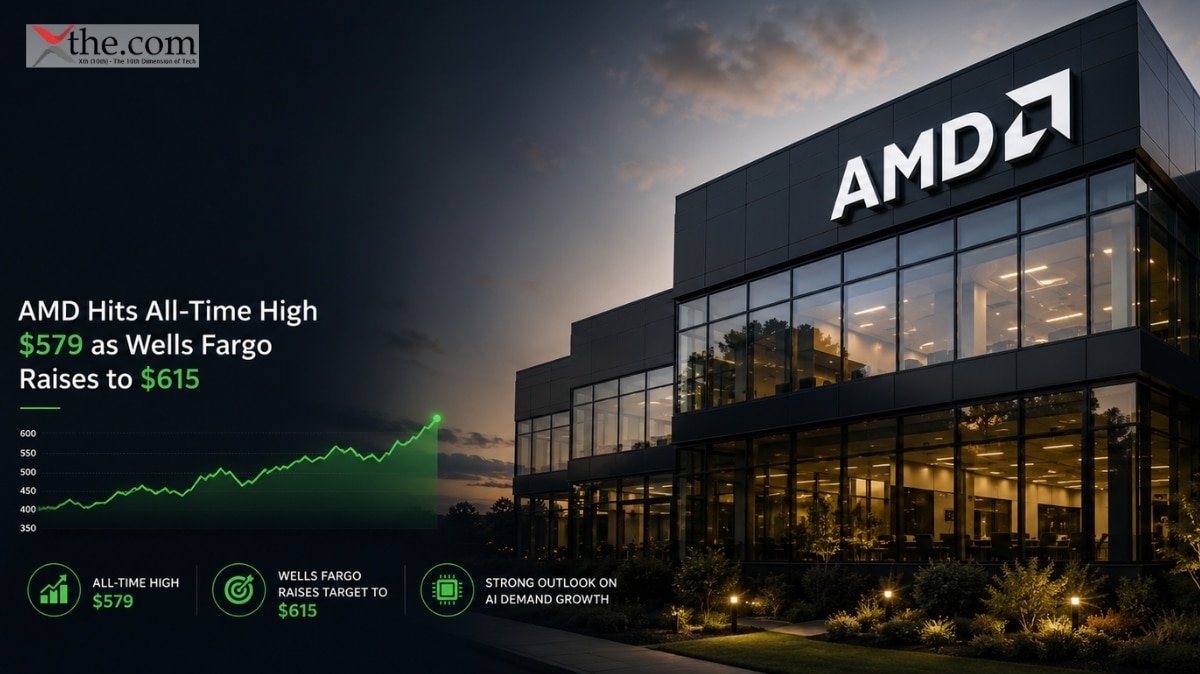
On June 30, AMD’s stock hit $579.73, setting a new record for a company often viewed as Nvidia’s runner-up. The phrase ‘AMD stock all-time high $579 Wells Fargo raises target to $615 explained June 30 2026′ started trending as AMD finished the day up over 7%. This jump prompted analysts to quickly revise their forecasts. 

This upsurge was not powered by rumors or technical signals. It was sparked by a clear, data-driven recommendation from a top semiconductor analyst. 

The Upgrade That Moved The Tape 

Wells Fargo analyst Aaron Rakers raised his AMD Wells Fargo price target to $615 from $505, an increase of more than 21%, and maintained an Overweight rating. This action signals to institutional investors that AMD’s core outlook has improved, not just its valuation. 

Rakers set his new target based on a three-year earnings outlook rather than a single product cycle. He predicts CPU revenue will reach $16 billion in 2026, $20.5 billion in 2027, and $25 billion in 2028, with about 68% growth this year. For GPUs, he expects $15.6 billion in 2026, $40.6 billion in 2027, and nearly $63 billion in 2028. These projections themselves support earnings-per-share estimates of $7.15 for 2026 and $13.40 for 2027, both above earlier forecasts. 

Wells Fargo’s semiconductor upgrade is based on unit economics, applying a 33-times price-to-earnings ratio to a 2028 EPS estimate of $18.75 to reach the $615 target. Cantor Fitzgerald set an even higher target of $700, while Goldman Sachs raised its estimate to $450 from $240, citing strong AI trends. The wide range of $450 to $700 shows analysts are still reaching a consensus, but the overall outlook stays positive. 

Why The Server Chip Story Matters More Than The Headline Number 

Besides the record stock price, there is another important development: AMD’s sixth-generation, 2-nanometer EPYC server CPU, called Venice, started production in late May and will ramp up through late 2026. AMD says more customers are adopting Venice than any earlier EPYC generation, which is a strong commercial indicator. 

Morgan Stanley expects Venice to ship 6.75 million units in 2027, beating the 5.75 million units projected for Nvidia’s competing Vera CPU in the same period. This is a new development in the NVDA AMD chip race that the market had not fully recognized before. Server CPUs usually do not attract as much attention as graphics accelerators, but AMD now estimates the total addressable market for this segment at $120 billion by 2030, according to CEO Dr. Lisa Su. Wells Fargo’s $25 billion forecast for 2028 suggests AMD could capture about 20% of that market within four years. 

AI Data Center Demand Reshapes The Competitive Map 

The main idea behind this rally is a shift happening in large data centers. Workloads are shifting from model training, where Nvidia has been dominant, to large-scale inference, where cost per token and performance per watt matter more than raw speed. This change is the opportunity AMD has been waiting for. 

Meta plans to deploy up to 6 gigawatts of AMD Instinct GPU capacity, starting with a custom MI450-based design. Meta is also a lead customer for the Venice CPU launch. AWS, Google Cloud, Microsoft Azure, and Tencent have all expanded their EPYC-powered cloud offerings, increasing AMD’s presence among major cloud providers that once relied mostly on Nvidia chips. This variation is why demand for AMD’s AI data center chips is now a key topic for portfolio managers seeking exposure to AI infrastructure without putting all their risk in a single supplier. 

The Philadelphia Semiconductor Index reflected this broader excitement, rising 3.83% that same day, with 25 of 30 stocks gaining. Moves this large across the sector are rare, except during major events, underscoring how much importance the market placed on Rakers’ report. 

The Rackspace Deal Signals A New Customer Category 

AMD is not just winning business from hyperscalers. On June 16, AMD and Rackspace Technology signed a deal to deploy 30 megawatts of AMD-based AI computing across Rackspace’s global data centers, formalizing an earlier agreement. The setup combines AMD Instinct GPUs, including the MI355X and MI350P series, with AMD EPYC CPUs in what Rackspace calls a governed Enterprise AI Cloud architecture. 

Deployment is set to start in late 2026 and continue through 2028, focusing on regulated markets like healthcare, where compliance and vendor accountability continue as important as performance. Rackspace CEO Gajen Kandiah described the goal as a governed AI stack with one accountable partner from hardware to results, targeting enterprises that have been cautious about AI spending in the absence of clear governance. For AMD, this shows that demand is growing beyond just the largest cloud platforms. 

Approaching A Trillion-Dollar Valuation 

The market capitalization math has become impossible to ignore.AMD closed June near $580 per share, up more than 171% year-to-date and over 309% over the past 12 months, pushing its valuation to the doorstep of the ten-figure mark. AMD’s market cap of $1 trillion is no longer a speculative milestone; it is a near-term arithmetic outcome if the stock holds recent levels, and TradingKey’s coverage of the June 30 session framed the company as closing in on that threshold in real time. 

This sets the stage for another search phrase now making the rounds among institutional investors: AMD close to $1 trillion market cap, AI chip demand second half 2026, investor analysis. The phrase underscores both the opportunity and the risks. AMD is currently trading at about 180 times trailing earnings, roughly six times Nvidia’s 30-times multiple. This means AMD’s performance must live up to the high expectations analysts have set. 

Of course, this does not mean AMD’s stock will keep rising without setbacks. Some doubters note that even with a 21% price target increase, there is still room for disappointment if Venice shipments fall short or hyperscaler spending slows. However, AMD’s growth now comes from several areas—server CPUs, AI accelerators, and regulated enterprise cloud deals—giving it more ways to meet its targets than it had last year. In the second half of 2026, investors will focus less on the stock price and more on whether Venice adoption, Instinct shipments, and deals like Rackspace turn forecasts into real revenue.

Source: AMD Shares Surge Over 7% to Record High. Morgan Stanley Expects Sixth-Generation CPU “Venice” Shipments to Fully Overtake Nvidia Vera 

New York, New York 

Just a few years ago, the IPO market encountered real challenges. Now, Wall Street has raised a record $251 billion through IPOs and equity offerings in the first half of 2026, marking the strongest fundraising period in recent US history. The main driver behind this jump was SpaceX’s historic public debut, which quickly reshaped the global capital markets. 

The US IPO record 2026 is the year’s biggest investment story. The IPO market in H1 2026 saw fundraising at an unprecedented level, and the SpaceX IPO record changed what people expect from major public listings. For investors, this drive goes beyond just one company. It shows renewed confidence in riskier assets, stronger demand from institutions, and a reopening of capital markets that many thought would take much longer. 

US IPO record 2026 signals a New Era for Capital Markets. 

According to Bloomberg, US companies raised about $251 billion in the first half of 2026 through IPOs and follow-on equity offerings. This set a new US equity issuance record and beat the highs seen during past tech booms. 

SpaceX led the way, with its $85.7 billion IPO becoming the largest in US history. This listing was more than merely a fundraising event. It showed that investors are still willing to invest large sums in companies with strong market positions, solid revenue growth, and lasting technological advantages. 

The impact of the US IPO record 2026 goes beyond just the numbers. As inflation settled and earnings outlooks improved, institutional investors who had been cautious during high-interest-rate periods returned in strong numbers to new offerings. 

Understanding the IPO market H1 2026 

The strong IPO market H1 2026 wasn’t just about one big deal. Many sectors contributed to this record-setting period, making it one of the healthiest times for new listings since the post-COVID recovery. 

Technology companies continued to receive high valuations, and fintech firms saw gains from improved profitability and more business customers. Healthcare innovators also attracted investors, as demand for biotech and medical tech stayed strong. 

Wider market trends also boosted investor confidence. The S&P 500 posted strong gains in the second quarter, and the Nasdaq-100 rose about 20% through June 30. These results led portfolio managers to invest more in growth companies going public. 

Strong stock performance, lower volatility, and plenty of institutional cash made it a great time for companies to go public. 

The SpaceX IPO record Changed Investor Expectations. 

Few companies have generated as much excitement before an IPO as SpaceX. When it finally went public, investor demand was even higher than expected. 

The SpaceX IPO record stood out not just for its $85.7 billion size, but also for drawing interest from almost every type of institutional investor. Pension funds, sovereign wealth funds, hedge funds, and retail investors all competed for shares. 

The SpaceX listing also changed how private tech companies are valued. Firms in aerospace, AI, robotics, satellite communications, and defense tech now have new standards for raising capital and planning future IPOs. 

For investment banks, this deal showed that very large IPOs are still possible when companies have strong advantages and proven ways to make money. 

IPO market Q2 2026 Closed with Exceptional Momentum 

Momentum picked up in the second quarter after the SpaceX debut rather than slowing down. The IPO market in Q2 2026 was the strongest quarter for new listings since 2020, driven by steady investor demand and a stronger economic outlook. 

An exceptional debut was Bending Spoons’ Nasdaq IPO, which began trading on July 1 and jumped about 42% on its first day. This strong showing confirmed that investors are still keen to back companies with profitable growth and scalable business models. 

The success of the Bending Spoons Nasdaq IPO also showed a key change. Investors now prefer companies with steady cash flow instead of just big future promises. This approach has led to better performance after IPOs than in earlier cycles. 

As the IPO market Q2 2026 concluded, investment banks reported expanding pipelines across software, cybersecurity, semiconductor infrastructure, financial technology, and space-related industries. 

US stock market H1 record Supports New Listings. 

The wider stock market also played a big role in reopening the IPO window. 

The US stock market’s H1 record shows steady gains in major indexes, stronger corporate earnings, and renewed economic optimism. Companies usually avoid going public during unstable periods. They prefer markets with rising values and strong trading activity. 

This environment has helped both companies and investors. New public companies could set better prices, and investors got access to businesses that had stayed private during the slow IPO years. 

The new US equity issuance record shows that companies wanted to raise substantial capital, and investors were equally eager to provide it. 

What Investors Should Watch During the Second Half of 2026 

With capital markets reopening, a key question is whether this pace can last. 

Right now, the IPO pipeline looks unusually strong as we move into the third quarter. Investment bankers are seeing increased interest from AI developers, enterprise software firms, digital payments companies, defense tech firms, and commercial space businesses. 

Investors looking up “US IPO market record $251 billion first half 2026 SpaceX driven what investors need to know” are asking the right question. The real answer is to focus less on flashy IPOs and more on business fundamentals. Things like revenue growth, profits, customer loyalty, competitive edge, and fair valuations matter more than hype. 

Likewise, people searching for “Best performing IPOs first half 2026 investor analysis Q3 outlook” should remember that big first-day gains don’t usually lead to long-term success. History shows that steady earnings growth is what really drives stockholder returns. 

The best opportunities may come from companies that can deliver steady results, not just impressive first-day stock jumps. 

Expected IPO Watchlist for H2 2026 

Several well-known companies are seen as likely to go public in the rest of 2026, as long as market conditions stay positive. 

Anthropic is one of the most-watched names, thanks to its rapid growth in enterprise AI and strong investor backing. OpenAI is also a top potential IPO candidate worldwide, though its timing depends on strategy and regulations. 

Outside of AI, investors should watch companies in fintech, cybersecurity, cloud software, semiconductor design, commercial aerospace, and space tech. These sectors continue to attract venture capital and have traits that public investors like: steady revenue, scalable platforms, and growing markets. 

If market conditions remain strong, more billion-dollar IPOs could sustain the momentum started in the IPO market in H1 2026. 

Investor Takeaway 

The first half of 2026 will likely stand out as a key time for US capital markets. The US IPO record in 2026, the historic SpaceX IPO record, and the broader US stock market H1 record have all reshaped expectations for public fundraising. 

This isn’t just a brief surge. The current market shows growing investor faith, stronger company finances, and more demand for top growth firms. Even though volatility will return, the open IPO market gives companies more ways to raise money and offers investors more chances in new industries. 

As the rest of 2026 plays out, the focus will move from record fundraising to the quality of companies going public. If trends continue, AI, fintech, and commercial space firms could shape the next phase of US equity markets, much like SpaceX did earlier this year.

Source: Stock Market News for July 1, 2026 

Washington, DC 

This year, over 1,200 cargo ships carrying about $125 billion in goods were stranded near the Strait of Hormuz. That’s why traders in London, Singapore, and New York are watching a conference room in Qatar more closely than any central bank meeting this week. The US-Iran Doha talks resumed on July 1, with American and Iranian delegations working through Qatari and Pakistani intermediaries instead of meeting face-to-face. Neither side is calling this a breakthrough. Diplomats describe it as something more modest and, for markets, more practical: a test to see if the Iran nuclear ceasefire 2026 can survive contact with its own fine print. 

Why Doha, and Why Now 

Indirect talks have happened before in this conflict, but the choice of venue and timing are important. Qatar holds billions of dollars in frozen Iranian assets and has been the main mediator since a memorandum of understanding was signed in mid-June. This makes Doha more than just a neutral location it has its own influence. Pakistan’s role adds another way for both Washington and Tehran to negotiate free from the pressure of direct talks that could upset their domestic audiences. 

Vice President JD Vance, addressing reporters this week, characterized the American position in blunt terms: the administration believes it has already secured its central objective by preventing Iran from obtaining a nuclear weapon, and it intends to negotiate the remaining details from a position it considers dominant. That framing matters for the US-Iran-Qatar mediation track because it signals Washington is willing to let talks stretch on rather than force a deadline, a posture markets have begun to price in as reduced near-term escalation risk. 

The Nuclear Track Is Still Separate From the Shipping Track 

One detail often missed in headlines is that the technical teams meeting in Doha this week are not primarily discussing enrichment levels or centrifuge counts. They are working through implementation disputes tied to the memorandum’s clauses on Hormuz access and the Lebanon front. Substantive Iran nuclear deal talks covering uranium stockpiles and inspections are expected to happen only after these procedural issues are settled, according to officials familiar with the schedule. Investors who see this week’s meetings as the final nuclear negotiation are missing part of the story, and this gap between perception and reality is causing extra financial volatility. 

Strait of Hormuz Oil: The Market’s Real Barometer 

While the nuclear issue grabs headlines, traders are really focused on oil flow through the Strait of Hormuz. This waterway usually handles about a quarter of the world’s seaborne oil and a fifth of global liquefied natural gas. The four-month disruption caused by this conflict didn’t just push prices higher it also showed how little flexibility there is in global energy logistics when a key route is blocked. 

This week, West Texas Intermediate crude dropped 1.1% to $68.77 per barrel, and Brent crude fell 1% to $72.20. These changes aren’t dramatic on their own, but together they suggest the market is guardedly optimistic, not convinced of a full resolution. Oil prices had swung sharply in previous weeks, with strikes and shipping incidents pushing Brent above $100 a barrel at the height of the conflict before falling back as tanker traffic improved. The current stability is a hopeful sign, but it’s not guaranteed. 

The Supply Chain Bill Has Not Been Paid Yet 

The oil price market impact of this conflict extends well beyond the futures screen. More than 1,200 cargo ships carrying about $125 billion in goods were stranded, according to insurance industry data. Tens of thousands of seafarers were stuck on ships, and some even ran low on food and fuel. Container lines stopped using the Strait of Hormuz for weeks. Freight forwarders told clients that even after a ceasefire, it could take four to six months for things to return to normal, since rerouted ships, crowded ports, and higher war-risk insurance costs don’t disappear right away. 

This delay remains important for anyone forecasting corporate earnings linked to manufacturing or energy exports from the Gulf. Shipping delays lasting months, combined with contracts set before the crisis, will squeeze profit margins. These effects likely won’t be clear until third-quarter results come out. 

WTI Crude July 2026: Reading the Signal Correctly 

Watching WTI crude July 2026 pricing in isolation misses the structural story. Prices around $69 a barrel show not just better diplomacy but also a real oversupply. Iranian exports jumped past 40 million barrels after the US ended its naval blockade, Russian shipments reached record highs, and UAE exports returned to pre-war levels using new routes. Right now, the market is dealing with both the benefits of peace and an oversupply. Figuring out which factor matters more will decide whether these prices last if talks break down. 

One failed round of talks in Doha would not immediately close the strait again. However, traders remember how quickly things changed in April, when a paused blockade resumed within a day after talks broke down. That experience is reflected in every Brent options contract this month. 

What a Genuine Long-Term Framework Would Require 

Executives running global supply chains do not need a peace treaty to plan around; they need predictability. A framework robust enough to restore corporate confidence would need to lock in guaranteed commercial passage through Hormuz, independent of the wider nuclear negotiations, establish enforcement mechanisms that survive leadership transitions in Tehran, and produce a verifiable inspection regime that satisfies both the US Congress and IAEA standards. Analysts covering this story for institutional clients have already begun portraying it as US-Iran nuclear talks resume Doha July 2026 impact on oil prices stock market explained, and the framing is apt: this is no longer a purely geopolitical story. It is a market structure story with political inputs. 

The Investor Calculus 

For portfolio managers, the main issue is when, not if, things will change. Volatility indices for the energy sector remain higher than before February, even though prices have fallen. This shows that the options market isn’t fully convinced things are stable. Stocks related to logistics, marine insurance, and Gulf-area manufacturing have moved with all headlines from Doha, sometimes reacting too strongly to minor updates. 

Several supply chain executives say privately that full corporate confidence probably won’t return before the third quarter, and only if the talks lead to a lasting agreement instead of another short-term extension. That’s an important point. Markets have priced in a temporary truce, but not a full resolution. The difference between those two is where the next few weeks of trading will focus. Reports for institutional readers now call this period an Iran ceasefire nuclear negotiations July 2026 investor impact energy market analysis moment, since what happens in Doha will affect energy portfolios long after the talks end. 

No matter what comes out of these talks, one thing is clear: the Strait of Hormuz is not merely a minor risk for global markets; it’s a key structural factor. The next update from Doha will likely move more money than most central monetary announcements this quarter.

Source: US-Iran deal could revive Trump’s trade war 

Beaverton, Oregon 

Sometimes, a strong headline earnings number can be misleading if it is driven by one-time gains rather than the main business. This is the situation investors face after Nike’s Q4 2026 results. Although Nike beat Wall Street’s earnings expectations, the details show the company is still dealing with weak consumer demand, falling sales in a key international market, and an unclear path to recovery. 

For retail investors watching NKE stock in July 2026, the main point is not just the earnings beat. The bigger issue is the growing difference between reported profits and the company’s actual business performance. The ongoing Nike China sales decline is especially troubling and continues to challenge management’s efforts to turn things around. 

Nike Q4 2026 earnings show strength on paper but weakness underneath 

Nike reported fiscal fourth-quarter earnings of $0.72 per diluted share. At first glance, the number comfortably surpassed analyst estimates of approximately $0.12 per share. 

The headline, however, masks an important reality. 

A significant portion of quarterly profit came from a Nike tariff-recovery windfall of approximately $986 million. This accounting benefit added around $0.52 per share to earnings. Without this one-time gain, Nike’s adjusted earnings were closer to $0.20 per share. 

Although $0.20 still exceeded Wall Street estimates, the underlying business remains far less profitable than the headline figure suggests. Investors looking at Nike Q4 2026 earnings should distinguish between recurring operating performance and temporary financial benefits. The company’s latest results clearly show that difference. 

Nike’s revenue for the quarter was $10.97 billion, down 1% from last year and down 4% after adjusting for currency changes. These figures show that demand remains weak across multiple major regions. 

The decline in Nike China sales remains the biggest warning sign. 

The most alarming figure in Nike’s earnings release came from Greater China. 

The company’s Nike Greater China revenue drop of 17% represented the steepest regional decline reported during the quarter. China has traditionally served as one of Nike’s fastest-growing and highest-margin markets. Losing momentum there creates problems that extend well beyond quarterly revenue. 

The Nike China sales decline shows several overlapping challenges. 

Consumer confidence in China remains low due to slower economic growth. Local athletic brands are gaining market share by selling quality products at lower prices. At the same time, more promotions across the industry make it harder for Nike to maintain strong prices. 

For investors, this weakness in China raises bigger questions about how soon Nike’s international growth can bounce back. North America is still Nike’s biggest market, but China has been seen as a key driver for future growth. 

If China does not recover, Nike’s overall earnings potential will be limited. 

Why the Nike tariff recovery windfall matters 

It’s important to pay attention to one-time accounting benefits because they can give a false impression of how a company is really doing. 

Nike’s tariff-recovery windfall came from a favorable customs decision, not from stronger sales or improved operations. 

This difference is important because investors should not expect these kinds of benefits to happen again in future quarters. 

When analysts exclude the tariff recovery from earnings, Nike’s profits look much weaker. Operating margins remain tight, inventory requires thorough management, and demand has not returned to prior levels. 

This is why experienced investors look past headline earnings per share. Real, lasting earnings growth usually comes from higher sales, better margins, and more customer demand, not from one-time financial changes. 

Nike’s turnaround strategy still faces significant obstacles. 

Nike’s management is still working on a broad Nike turnaround strategy. They are focusing on creating new products, building stronger relationships with wholesalers, and improving their web presence. 

Chief Financial Officer Matt Friend made what was likely the most important comment during the earnings call. 

He said the company does not expect the operating environment to improve meaningfully over the next six months. 

This guidance should make investors cautious if they are hoping for a quick recovery. 

Nike’s current Nike turnaround strategy entails updating its product lineup, reducing heavy discounts, rebuilding ties with key retail partners, and improving its operations across regions. These steps may help Nike in the long run, but management admits that real progress will take time. 

People’s willingness to spend on non-essential items remains uneven across many markets, and competition from both established and new athletic brands is intensifying. 

Why NKE stock July 2026 remains under pressure 

The market has already reflected many of these concerns. 

NKE stock in July 2026 is roughly 40% below its level at the beginning of the year. The shares have fallen to levels not seen since 2014, highlighting just how dramatically investor sentiment has shifted. 

The decline is not simply a reaction to one disappointing quarter. 

Instead, it shows greater uncertainty about future revenue growth, international demand, profit margins, and management’s ability to execute its recovery plan. 

The reason NKE stock 40 percent down 2026 is that investors increasingly demand evidence rather than promises. Markets reward consistent execution, especially after extended periods of declining performance. 

Valuation worries will likely persist until sales stabilize in key regions, especially China. 

Understanding the earnings beat in context 

Many investors often think that beating earnings expectations means business is getting better. 

But that is not always the case. 

This past quarter shows why it is important to look closely at the details. 

Revenue declined. 

Underlying earnings remained relatively modest. 

China weakened further. 

Management issued cautious forward guidance. 

Still, headline earnings beat expectations mainly because of a large one-time accounting gain. 

That is why many analysts call the results mixed instead of very positive. 

The long-tail keyword “Nike Q4 2026 earnings beat explained tariff windfall hides China weakness investor analysis” sums up the main issue. The announced earnings beat is only part of the story. When investors look past temporary financial gains and focus on the core business, the outlook is much more cautious. 

What investors should monitor during the next two quarters? 

Nike’s recovery will depend more on real improvements in its business than on accounting changes. 

Several indicators deserve close attention. 

Revenue growth should start to steady in major markets. Gross margins need to improve without too many promotions. Inventory must be managed carefully to avoid more discounting later. 

Most importantly, investors should watch whether Nike China sales decline begins to moderate after several tough quarters. 

Management’s comments suggest that a quick rebound is not expected, so future earnings reports will be especially important. 

If Nike can show steady improvement in Greater China, it could help restore trust in the company’s long-term international growth. 

Is Nike becoming a value opportunity? 

Long-term investors often take notice when strong brands see their stock prices drop a lot. 

Nike certainly fits that description. 

Nike still has one of the world’s strongest athletic brands, a global distribution network, invests heavily in innovation, and generates solid cash flow over time. 

However, a low stock price by itself rarely signals the end of a turnaround. 

The company’s actual business performance needs to get better in the end. 

The second long-tail keyword, “NKE Nike stock falls despite earnings beat Greater China decline explained July 2026”, sums up the current debate. Optimists say most of the bad news is already reflected in the stock price. Pessimists argue that falling international demand and cautious management comments mean more challenges could be coming. 

Both sides agree on one thing: Nike’s recovery is not complete yet. 

The road ahead for Nike 

Nike’s Q4 2026 earnings headline looked good at first, but the details show the company is still facing big challenges. The one-time tariff recovery helped profits, but falling revenue and a sharp 17% drop in Greater China show that the business recovery is not yet solid. With NKE stock in July 2026 still showing a lot of investor doubt and down 40 percent for the year, future results will depend more on real business improvements than on accounting gains. The next few quarters will show whether this is just a temporary setback for Nike or if a longer, tougher turnaround is needed. 

Source: Nike posts Q4 2026 earnings beat, but tariff refunds mask China struggles 

New York, New York 

Thirty-two stocks in the S&P 500 touched new 52-week highs on the same day the memory-chip trade lost 10% in a single session. That whiplash defined the opening bell of the third quarter, and it tells you almost everything about where money is moving right now. The Dow Jones record high July 2026 milestone arrived on Wednesday, July 1, when the blue-chip index touched an intraday peak of 52,742.66 before drifting back to close at 52,305.24, down a marginal 13.96 points, or 0.03%. It was a record made and nearly erased in the same session, and that tension between euphoria and profit-taking is the real story of the Q3 2026 stock market open. 

A Record High With an Asterisk 

Records rarely arrive quietly, and this one didn’t either. Caterpillar, an unlikely beneficiary of the artificial intelligence buildout thanks to its role supplying data-center generators, pulled back nearly 7% intraday and dragged the Dow off its high. The index still closed within shouting distance of the peak, and the achievement stands: this was the market record high July 1 that traders had been anticipating since the Dow first cracked 50,000 back in February. 

Behind that number sits a stronger, if less flattering, story. The S&P 500 Q3 start picked up right where the second quarter left off, but not without turbulence. The benchmark index closed the previous session at 7,499.36, marking its best quarter since 2020, then slipped 0.22% on July 1 to finish at 7,483.23. Manufacturing data added to the uncertainty. According to ADP, private payrolls grew by only 98,000 in June, missing the Dow Jones estimate of 110,000 and down from May’s 122,000. ADP chief economist Nela Richardson said the labor market is facing both supply and demand challenges, with job seekers taking longer to find work even as some industries still need more workers. 

Dow Nasdaq S&P 500 Q3 Opening: A Tale of Two Trades 

The Dow, Nasdaq, and S&P 500 Q3 opening split cleanly along sector lines, and the divergence was sharp enough to reshape portfolios overnight. The Nasdaq Composite fell 0.66% to 26,040.03 as investors dumped semiconductor names that had powered the market’s first-half advance. That selloff followed a run in which the chip sector had surged more than 80% during the first six months of 2026, a gain so extreme that even a modest pullback looked dramatic by comparison. 

Micron Technology fell more than 10% on July 1, but the stock is still up over 260% for the year. SanDisk dropped by a similar amount but remains more than 750% higher in 2026. Nvidia and Broadcom also slipped about 1% and 2% as the chip sector cooled off. These declines did not change the overall trend. Instead, they slowed things down after a first half that had already seen huge gains. 

Blue Chip Stocks Rally While Chipmakers Cool Off 

The blue-chip stocks rally that carried the Dow to its record was less about any single earnings blowout and more about capital rotating out of the most crowded trades. On CNBC’s “Mad Money,” Jim Cramer explained that Wall Street is now favoring companies that supply the artificial intelligence boom rather than the tech giants that fund it. He listed Micron, Intel, Marvell, AMD, and SanDisk as the companies best positioned to benefit from what he called a supply-demand imbalance that is boosting earnings. As Cramer put it, the biggest winners this quarter are not the usual household names but companies making products in short supply and high demand. 

There are real numbers behind this disequilibrium. Micron’s revenue for the third quarter was $41.5 billion, and the company’s market value briefly surpassed Meta at $1.4 trillion. SanDisk reported $5.95 billion in third-quarter revenue, up 97% from the previous quarter, and its shares have soared about 4,800% over the past year. These numbers show just how tight the memory-chip market has become as AI infrastructure projects use up all available supply. 

The Magnificent Seven Q3 Reckoning 

The flip side of that story belongs to the Magnificent Seven Q3 cohort, the handful of technology giants that have dominated market gains for the past several years. The group collectively shed roughly $2.3 trillion in market value during June alone, as investors began questioning whether record levels of AI capital expenditure will generate returns commensurate with the spending. Meta bucked that trend on July 1, surging 8% after unveiling plans to build a cloud infrastructure business with dedicated access to AI computing power, a move that simultaneously pressured infrastructure names like CoreWeave, which tumbled 14% on the news. Microsoft, Amazon, and Alphabet posted more modest gains as they attempted to stabilize after months of underperformance relative to the AI-infrastructure suppliers now capturing investor attention. 

This shift is known as the Great Rotation, and it is happening right now. Money that chased semiconductor stocks in the first half of 2026 is now moving toward the more stable, dividend-paying companies in the Dow. Analysts say this is not a rejection of the AI trend, but a sign that it is maturing, moving from speculation to steady earnings. Wall Street experts now see the AI infrastructure sector as a key driver of corporate profits, with some predicting it could make up nearly 60% of the S&P 500’s earnings growth this year. If that’s true, it helps explain why the market can react strongly to a bad day for chip stocks while the overall index keeps reaching new highs. 

What Investors Need to Watch Next 

New Federal Reserve Chairman Kevin Warsh did not offer many clues about future interest rates during his speech at the European Central Bank Forum on July 1, but he reiterated his goal of lowering inflation. Oil prices have dropped, with crude trading slightly higher at $69.78 per barrel, which could give the Fed more flexibility without triggering new inflation worries. The 10-Year Treasury yield rose slightly to 4.48%, suggesting bond markets still expect further rate hikes rather than the cuts some stock investors want. 

Corporate earnings additionally played a role in the day’s trading. Nike dropped about 3% after warning about consumer concerns, while Birkenstock got a positive review from Raymond James, which set a $52 price target suggesting more than 20% upside and called the brand a stronger growth story than many realize. Meanwhile, Bending Spoons, the Italian software company behind AOL and Vimeo, jumped 42% on its Nasdaq debut, showing that investors remain interested in new listings even as established companies shift. 

People searching for expressions like “Dow Jones hits record high July 1 2026 best quarter since 2020 Q3 stock market outlook” are really wondering whether the record means the market can keep rising or signals the top of a hot cycle. History gives a mixed answer. Strong first halves often lead to more gains in the second half, though usually smaller ones. However, this year’s big chip-sector rally means there is less room for mistakes than in past years. Investors looking at the “Stock market July 1 2026 Dow record Nasdaq chip selloff what investors need to know” story should see the memory-chip drop as a price reset, not a sign of a broader downturn, since fundamentals like Micron’s revenue and SanDisk’s contract backlog remain strong. 

As the third quarter begins, the market is both pricier and pickier than it was six months ago. Money is now moving into blue-chip industrial, financial, and communications stocks rather than just semiconductors, while investment in AI infrastructure continues at a strong pace. Whether the Dow’s July 1 record is merely a milestone or the peak will depend more on the Federal Reserve’s next steps than on any one company’s earnings report.

Source: Stock Market Today (July 1, 2026): Dow, S&P 500 rise to start Q3 2026; comms and financials do the lifting 

New York, New York 

SanDisk shares dropped 11% in a single trading session on the first day of the second half of 2026. Wall Street had just finished celebrating a strong first-half rally when the memory stock selloff erased weeks of gains in only a few hours. 

The Micron stock drop in July 2026 and the parallel SanDisk crash on July 1 did not happen in a vacuum. They followed a Bloomberg report revealing that Facebook is preparing to enter the cloud computing business, a move that instantly reframed how investors think about demand for AI infrastructure. By the closing bell, Micron MU) fell 9 percent, and SanDisk SNDK) fell 10 percent; these were not projections. They were the day’s headline numbers, and they dragged the wider chip complex down with them. 

What Triggered the Memory Stocks Selloff 

For over a year, Meta has been one of the biggest buyers of computing power. That changed on July 1, when reports said the company plans to launch two new business lines: model services and leasing bare-metal computing power. Instead of just using server capacity, Meta now plans to sell it, competing with Amazon Web Services, Microsoft Azure, and Google Cloud, and putting pressure on AI infrastructure providers like CoreWeave. 

The market reacted quickly and sharply. If Meta shifts from being a buyer to a seller, the logic goes, then some portion of the memory and compute capacity it once needed to purchase may no longer be needed at all. That single sentence explains most of the Meta cloud-oversupply fears that swept through trading desks on Wednesday morning. CoreWeave shares fell 14 percent, Corning dropped more than 13 percent, Marvell slid over 7 percent, and Lumentum lost more than 6 percent as optical component makers faced the same worries as memory chipmakers. 

Not everyone thinks these fears are justified. Some analysts say that if Meta’s cloud plans work out, the company might need to expand its data centers even faster, which could actually boost hardware demand rather than hurt it. For now, the market is divided over which view will prove right. 

Why Micron and SanDisk Took the Hardest Hits 

One of the top financial questions that day was, “Why did Micron and SanDisk fall 9 to 10 percent on July 1, 2026? Meta cloud oversupply explained.” The answer is more complex than just one headline. Micron and SanDisk are central to the DRAM and NAND memory supply chain, so they are especially sensitive to any sign of changing demand. When a company as big as Meta hints at changing how it uses computing infrastructure, memory stocks feel the impact first and most strongly. 

Two more issues made Wednesday’s decline worse. A California class action lawsuit filed the week before claims that Samsung, SK Hynix, and Micron worked together to limit DRAM supply and raise prices. This legal risk added uncertainty about pricing just as investors were already uneasy. On top of that, Citrini Research warned that DRAM prices have jumped by about 700 percent over four years, which could force major buyers to cut back just to protect their profits. This warning brought the DRAM supply concern that had been quietly growing into the open. 

Micron CEO Sanjay Mehrotra has previously pushed back against negative views, defending the company’s pricing strategy and highlighting about $200 billion in planned manufacturing and research investments, including new plants in Boise, Idaho and Syracuse, New York. In the fiscal third quarter, Micron’s revenue was $41.46 billion, up 346 percent from last year, and adjusted earnings were $25.11 per share, beating the consensus estimate of $20.28. These results do not show a company with falling demand. Instead, they show a company whose stock had risen too quickly and was due for a correction. 

Second-Half Profit-Taking Meets a Genuine Structural Question 

“Memory stocks MU SNDK WDC selloff July 2026 second half profit taking investor analysis” is the framing that many desk strategists reached for by midday. Institutional rebalancing at the start of a new half-year period is common and tends to hit the longest-running winners hardest. Micron entered the session up roughly 250 percent year to date. SanDisk had climbed more than 850 percent over the same window. Positions of that size attract profit-taking almost by default, regardless of what news breaks on any given morning. 

Western Digital provides a good comparison. After selling off SanDisk in February 2025, it now focuses solely on hard disk drives and is shielded from fluctuations in NAND prices. In the days leading up to July 1, Western Digital’s stock rose while Micron and SanDisk fell, suggesting that money was moving within the storage sector rather than leaving it altogether. 

Short-seller activity added more pressure. News that Michael Burry had taken short positions against several big AI companies, including Nvidia, shook confidence across the chip industry, not just in memory chips. The Nasdaq Composite ended the day down more than 0.4 percent, which may seem small but masked much bigger losses in the most popular AI infrastructure stocks. 

What Comes Next for Memory Investors 

Even after Wednesday’s tough session, the basic supply and demand situation for memory chips has not changed. Micron is still up about 250 percent for the year, and SanDisk is ahead by more than 850 percent much bigger gains than the single-day drop that made headlines. Long-term contracts with minimum prices, which management expects will eventually account for nearly 40 percent of Micron’s revenue, are meant to protect the business from such market fluctuations. 

The real test will come in the next few weeks, as SanDisk and Western Digital report their fiscal fourth-quarter results and as we learn more about the true size of Meta’s cloud plans. If Meta’s move increases overall demand for computing power rather than replacing current purchases, Wednesday’s sell-off will probably be seen as a sharp but short-lived adjustment. But if it signals a real change in how large tech companies approach buying versus building capacity, memory investors could be facing the start of a much longer story, not just a single volatile day.

Source: Micron Drops 8%, SanDisk Slumps 10%, Western Digital Falls 7% as Memory Stocks Pull Back With the NASDAQ 

Boise, Idaho 

Just one missing semiconductor can halt a whole vehicle assembly line. Automakers saw this firsthand during the global chip shortage and want to avoid it happening again. The Micron GM supply deal is more than just another supplier announcement. It shows a greater shift toward long-term buying strategies that prioritize supply security over short-term savings. The agreement centers on expanding Micron automotive memory across future General Motors vehicle platforms under the MU General Motors agreement, reinforcing both companies’ devotion to stable production and advanced technology. 

Micron GM Supply Deal Strengthens Automotive Chip Security 

Micron Technology and General Motors have signed a Strategic Customer Agreement to guarantee a steady, multi-year supply of memory and storage products for GM’s future vehicles. The deal includes LPDRAM automotive supply, as well as NOR flash and UFS NAND storage solutions. These technologies are now essential because modern vehicles count on more advanced software systems. 

This agreement differs from typical supplier contracts, which mainly focus on price. Instead, it highlights predictable supply, closer teamwork between engineers, and long-term planning for manufacturing. For General Motors, this helps reduce the risk of production delays due to chip shortages. For Micron, it builds another strong relationship with a major automotive customer and supports new manufacturing investments. 

This announcement further strengthens the company’s growing position in the growing Micron automotive memory, a market that continues expanding as electric vehicles, advanced driver aid systems, digital dashboards, and OTA updates become more common, cars need much more memory than before. 

Why the MU General Motors Agreement Matters 

The MU General Motors agreement comes at a time when automakers see sourcing semiconductors as a key business strategy, not simply a routine buying task. 

General Motors Chair and CEO Mary Barra said the agreement “strengthens our access to critical memory technologies while enabling deeper integration across our vehicle platforms.” Her comment shows how important memory technology has become for vehicle performance. 

All major electronic control units need reliable memory. Infotainment systems need fast storage. Driver-assist features handle huge amounts of sensor data. Battery control systems track thousands of details at all times. Even remote software updates depend on solid onboard memory. 

The Micron GM supply deal gives General Motors a clearer view of future supply and lets Micron coordinate its production with GM’s long-term plans. 

The Role of LPDRAM Automotive Supply within Next-Generation Vehicles 

Memory is now one of the fastest-growing types of semiconductors used in today’s vehicles. 

The agreement includes LPDRAM automotive supply, a technology built for high performance and low energy use. Using less power helps make vehicles more efficient, which is especially important for electric cars where saving energy is key. 

LPDRAM enables multiple vehicle functions simultaneously, including: 

  • Advanced driver aid systems 
  • Digital instrument clusters 
  • Infotainment platforms 
  • Artificial intelligence workloads 
  • Real-time navigation 
  • Over-the-air software updates 

As cars need more computing power, GM’s next-gen vehicles’ memory also needs much more memory than experts expected just a few years ago. Future cars that rely on software will probably need even more memory than current models. 

Micron Manassas, Virginia, Fab Supports Domestic Production 

A key part of this agreement is Micron’s investment in manufacturing. 

The Micron Manassas, Virginia, fab is undergoing approximately $2 billion in modernization, expanding domestic DRAM manufacturing capacities that directly support automotive customers. 

Where chips are made now matters more to automakers. Making products closer to home reduces shipping delays, shortens supply chains, and lowers the risk of disruptions from global events that can affect chip manufacturing. 

The upgraded Micron Manassas, Virginia, fab also supports broader U.S. efforts to boost domestic chip production after years of relying on overseas factories. 

Instead of relying solely on global suppliers, companies now seek more diverse manufacturing strategies to strengthen their supply chains. 

A Growing Focus on the Semiconductor Automotive Supply Chain 

The agreement also shows how the semiconductor automotive supply chain is changing. 

Before 2020, many automakers saw semiconductors as simple parts they could buy from top suppliers. The shortages during the pandemic proved that was not the case. 

A late shipment of memory chips could shut down factories making thousands of cars each week. This experience changed how the whole auto industry buys parts. 

Now, makers often work directly with chip companies to lock in production capacity years in advance. 

As a result, the semiconductor automotive supply chain now focuses more on long-term partnerships, greater transparency, and joint planning between chipmakers and automakers. 

The Micron GM supply deal is a clear example of this trend. 

Micron’s Strong Fiscal Momentum Backs Long-Term Agreements 

This announcement comes after Micron reported record earnings for the third quarter of fiscal 2026. 

In its earnings call, Micron said revenue reached $41.46 billion, up about 346% from last year. Management also shared that the General Motors deal is one of sixteen Strategic Customer Agreements signed in important markets. 

This healthy financial performance gives customers more confidence when making long-term sourcing decisions. 

Automakers usually launch vehicle platforms that stay in production for five to seven years. So they need to trust that their suppliers will continue investing throughout the product’s life. 

Micron’s recent growth means it can meet rising demand from the auto industry while also serving data center, AI, and consumer electronics customers. 

Rising DRAM Prices Reinforce Long-Term Supply Planning 

Changes in pricing also help explain why the agreement happened now. 

S&P Global Mobility data show that DRAM prices have risen about 70% since December. 

These higher prices encourage both buyers and suppliers to set up stable, long-term deals. 

General Motors gets more certainty about future parts supply. Micron secures reliable demand, which helps with planning and investment. 

Micron’s automotive memory business benefits from this firmness, since it takes years to validate components before they go into production vehicles. 

Once approved, suppliers usually remain involved throughout the entire vehicle generation. 

Micron General Motors long-term memory chip supply deal July 1 2026 what it means 

The phrase “Micron General Motors long-term memory chip supply deal July 1 2026 what it means” highlights that this announcement is important for more than just one customer relationship. 

For investors, it shows that demand for automotive memory remains strong, even as the overall semiconductor market evolves. 

For automakers, it proves that securing enough semiconductors is now a top-level business priority, not merely a routine buying task. 

For suppliers, it confirms that the industry is moving toward more direct teamwork between car makers and chip companies. 

The agreement also shows how memory has evolved from a supporting role to a technology that directly affects what vehicles can do, how their software works, and the overall customer experience. 

Micron MU GM strategic customer agreement LPDRAM automotive supply chain explained. 

To understand “Micron MU GM strategic customer agreement LPDRAM automotive supply chain explained,” you need to look beyond just the memory products themselves. 

This partnership brings together several connected goals: 

  • Reliable long-term memory availability. 
  • Greater collaboration between engineering teams. 
  • Domestic manufacturing support through the Micron Manassas, Virginia, fab. 
  • Stable sourcing for GM next-gen vehicles memory requirements. 
  • Improved resilience throughout the semiconductor automotive supply chain. 

Instead of waiting for shortages to happen, both companies are planning years in advance for vehicles that will rely more on software. 

This forward-thinking approach shows both companies have learned from recent industry disruptions. It also recognizes that future vehicle innovation will depend just as much on computing as on mechanical engineering. 

Gazing Forward 

The Micron GM supply deal shows how car manufacturing is becoming more focused on technology. Now, memory, storage, and computing power are just as important as engines, batteries, and design. With investments in the Micron Manassas, Virginia, fab, increased LPDRAM automotive supply, and rising demand for memory in GM next-gen vehicles, the MU General Motors agreement helps both companies navigate a more complex semiconductor supply chain. As cars become more software-driven, partnerships like this will likely affect both production stability and the industry’s ability to innovate worldwide.

Source: Micron, GM sign semiconductor supply agreement for vehicles 

Menlo Park, California 

For years, Meta Platforms invested tens of billions of dollars building AI infrastructure to support its own products, from Facebook and Instagram to WhatsApp and generative AI initiatives. Those investments were largely viewed as internal expenses aimed at improving advertising, recommendation systems, and AI-powered consumer services. 

That strategy appears to be changing. 

According to reports, Meta is developing a commercial cloud offering that would allow outside companies to purchase access to its AI infrastructure, creating a new Meta cloud business designed to compete directly with Amazon Web Services (AWS), Microsoft Azure, and Google Cloud. Rather than limiting its massive data centers to internal workloads, Meta could begin monetizing excess capacity while simultaneously expanding its presence in enterprise AI. 

For technology executives, investors, and enterprise customers, the implications extend well beyond another cloud product launch. 

Meta Cloud Business Marks A Strategic Shift. 

Meta has never operated a traditional enterprise cloud platform. Unlike AWS, Azure, or Google Cloud, its infrastructure has been built almost entirely for internal use. 

Now, Bloomberg reports suggest that the company wants to commercialize those assets. 

The proposed Meta Compute initiative would reportedly generate revenue through two complementary services. One would provide customers with hosted access to Meta’s proprietary AI models, while the second would offer direct compute capacity for organizations that simply need graphics processing power without having to build expensive infrastructure themselves. 

That approach immediately positions the Meta AWS rival strategy against two of the fastest-growing segments in enterprise AI. 

Companies increasingly want access to large language models without having to manage the underlying hardware. Others simply need enormous quantities of GPUs to train proprietary AI systems. Meta appears interested in serving both markets simultaneously. 

Why Meta AI compute for sale Changes The Competitive Landscape 

Cloud computing has evolved far beyond virtual machines and storage. 

The fastest-growing cloud revenue now comes from AI infrastructure. 

Every major technology company is racing to secure GPU capacity as businesses deploy increasingly complex models requiring thousands of high-performance processors. Building that infrastructure internally costs billions of dollars, making cloud providers essential partners for AI development. 

This explains why Meta AI compute for sale represents more than just another product announcement. 

Instead of allowing unused processing capacity to remain idle during certain workloads, Meta could convert those resources into recurring enterprise revenue. The business model resembles airlines selling unused seats or utilities distributing excess electricity during periods of lower internal demand. 

Infrastructure utilization improves profitability. 

Enterprise customers gain immediate access to advanced hardware. 

Meta gains a new revenue engine outside digital advertising. 

Meta Compute initiative Could Mirror AWS Bedrock. 

One reported component of Meta’s plans involves hosted AI services. 

Rather than forcing developers to download open-source models and deploy them independently, Meta could allow customers to access AI models directly through managed cloud services. 

That concept resembles Amazon’s Bedrock platform. 

Reports indicate these services could feature Meta Muse Spark models, enabling developers to integrate advanced generative AI capabilities without maintaining their own infrastructure. 

For businesses, this dramatically simplifies AI deployment. 

A financial services company building customer support automation, for example, could access Meta Muse Spark models via APIs rather than purchasing expensive GPU clusters and maintaining complex software environments. 

The result lowers technical barriers while expanding Meta’s reach into enterprise software. 

Raw Infrastructure Could Challenge The Neocloud Market 

The second part of Meta’s strategy may prove even more disruptive. 

Rather than focusing exclusively on hosted AI models, Meta reportedly intends to sell raw computing power similar to specialized infrastructure providers. 

This places Meta Cloud vs CoreWeave squarely into one of AI’s fastest-growing competitive battles. 

CoreWeave built its business around providing GPU capacity optimized specifically for artificial intelligence workloads. Rather than competing broadly with AWS, it concentrated almost entirely on high-performance computing. 

Meta enters that market with an enormous advantage. 

Its infrastructure already supports billions of users worldwide. If excess computing resources become commercially available, Meta immediately becomes one of the largest suppliers of AI infrastructure without having to construct an entirely new cloud network. 

The emerging Meta cloud vs CoreWeave competition illustrates how AI infrastructure has become a standalone business rather than simply an operational necessity. 

Zuckerberg Cloud Infrastructure Vision Extends Beyond Social Media 

Chief Executive Mark Zuckerberg has repeatedly emphasized AI as Meta’s long-term priority. 

Building larger data centers, expanding GPU deployments, and increasing capital expenditures all support that objective. 

The reported Zuckerberg cloud infrastructure strategy extends those investments into commercial enterprise markets. 

Instead of viewing infrastructure solely as a cost center that supports Facebook and Instagram, Meta could begin treating its computing network as a revenue-generating asset. 

That shift resembles Amazon’s transformation two decades ago. 

AWS originally emerged from infrastructure Amazon built to support its retail operations. Over time, that internal capability evolved into one of the world’s most profitable cloud businesses. 

Meta may be attempting a similar transition, although today’s AI-driven cloud market differs significantly from the internet infrastructure landscape AWS entered in 2006. 

Investors Should Watch Infrastructure Economics 

The AI race has often focused on models. 

OpenAI. 

Anthropic. 

Google Gemini. 

Meta Llama. 

Yet many investors increasingly believe infrastructure providers may generate more consistent long-term returns than model developers. 

Training advanced AI systems requires enormous capital investments in data centers, networking equipment, cooling systems, and electricity. Every new model increases demand for infrastructure regardless of which developer ultimately wins. 

This perspective explains growing attention around “Meta building cloud business selling AI compute power models like AWS explained July 2026”. 

If Meta successfully commercializes infrastructure already financed for internal operations, incremental revenue could improve returns on billions of dollars in existing capital expenditures. 

That changes investor expectations considerably. 

Instead of valuing Meta solely as an advertising company investing heavily in AI, markets may begin evaluating it as both an advertising platform and a cloud infrastructure provider. 

What Enterprise Customers Stand To Gain 

Competition generally benefits enterprise buyers. 

AWS, Azure, and Google Cloud have dominated enterprise cloud infrastructure for years, but demand for AI computing continues to exceed available supply in many regions. 

Additional providers increase capacity while creating pricing pressure. 

Organizations developing AI products may gain access to alternative GPU resources, hosted AI models, or both. 

That matters because infrastructure shortages have delayed numerous enterprise AI deployments over the past two years. 

If Meta introduces large-scale commercial compute offerings, businesses could diversify their supplier base while reducing dependence on a single cloud ecosystem. 

The Bigger Picture For Cloud And AI Markets 

Perhaps the most interesting development isn’t that Meta wants to compete with AWS. 

It’s that every major technology company increasingly recognizes infrastructure itself as the product. 

Data centers once supported software. 

Now, they have become the software business. 

That broader trend gives greater relevance to “Meta cloud infrastructure plans impact on CoreWeave AWS Azure Google stock investors”. 

Investors evaluating Amazon, Microsoft, Alphabet, CoreWeave, and Meta must now consider how expanding infrastructure competition affects margins, customer acquisition, and long-term capital spending. 

Cloud providers may face increased pricing competition. 

AI startups may gain additional suppliers. 

Enterprise customers could enjoy more flexibility than ever before. 

Companies capable of financing multi-billion-dollar infrastructure projects may ultimately hold the strongest competitive advantages, regardless of whose AI model generates the best benchmark scores. 

Meta’s reported cloud ambitions suggest the next phase of artificial intelligence will revolve less around algorithms and more around ownership of the physical infrastructure powering them. Whether the Meta cloud business becomes a direct threat to AWS, Azure, Google Cloud, and specialized providers remains to be seen, but one reality is already emerging: in the AI economy, data center owners may capture as much value as the creators of the models themselves. 

Source: Meta Plans Cloud Business to Take on Big Tech Rivals