New York, New York 

Wall Street just wrapped up its best quarter since 2020, a result that would have seemed unlikely only three weeks ago. The Dow Jones record high in June 2026 after a two-day surge that wiped out the pain of a recent sell-off. Blue-chip stocks, semiconductor companies, and large software firms all moved higher together. The Nasdaq and S&P 500 rally today extended into a second straight session of gains, and the catalyst wasn’t a single headline. It was three converging forces: a geopolitical de-escalation, a Supreme Court ruling that steadied the Federal Reserve, and a tech stocks rebound in 2026 that traders had been hoping for since chipmakers had their worst week since April 2025. 

What Drove the Dow Jones Record High June 2026 

The Dow Jones Industrial Average closed at 52,182.74 on Monday, up 306.63 points, or 0.59%, marking its first finish above the 52,000 threshold. Tuesday brought a second consecutive record close, with the index adding another 136 points to settle at 52,319.20 — a gain of 8.85% year-to-date. That two-day stretch is the clearest evidence yet of the Dow Jones record high June 30 2026 tech rally, explained in plain terms: money that fled growth stocks during June’s rotation into healthcare and industrials found its way back into technology once the macro backdrop cleared. 

The alphabet played a big role in the rally. Its shares rose nearly 5% on their first day as an official Dow member, taking Verizon’s place after Verizon’s stock fell more than 5% from the change. Caterpillar and Cisco Systems also had strong days, while Honeywell International and UnitedHealth did not perform as well. Because the Dow is made up mostly of industrial, healthcare, and financial companies instead of just software firms, a Dow record does not always mean tech stocks are leading. This week, though, they did. 

Nasdaq S&P 500 Rally Today Outpaces the Blue Chips 

While the Dow showed gains across many sectors, the Nasdaq’s rise was even more pronounced. The Nasdaq Composite rose 2.07% on Monday and another 1.52% on Tuesday, ending the quarter at 26,213.72, up 12.79% for the year. The S&P 500 also performed well, gaining 1.18% on Monday and 0.79% on Tuesday, closing at 7,449.36, a 9.55% year-to-date advance. Investors chasing a clean read on the Nasdaq S&P 500 jump today, investor analysis 2026, need only look at the semiconductor ETF SMH, which climbed 3.33% as chipmakers rebounded from their steepest weekly decline in more than a year. 

Small-cap stocks also moved higher. The Russell 2000 rose 0.46% to 3,024.37, setting a new milestone for an index that usually gets less attention during big rallies by large companies. This broad participation is important. When only a few large companies rebound, those gains often fade quickly. But when regional banks, industrial suppliers, and mid-sized software firms also rise, the rally may last longer, though experts say it is too soon to know if this trend will continue. 

Mag7 Stocks Rally Leads the Charge 

The Mag7 stocks rally was a key part of Monday. Tesla led the group, jumping 8.5%. Amazon rose 3.2%, Meta gained 2.2%, and Nvidia was up 1.3% after a tough period for AI-related stocks. Not all large companies joined in equally, though. Apple fell 0.7%, and Microsoft dropped 1.2%, showing that even during a rally, not every stock moves the same way. 

Options traders also saw something interesting. Big call options on Mag7 stocks were set to expire in 2027, suggesting some large investors are betting on gains that will last longer than just this week’s rally. This is different from the usual short-term moves that follow a quick sell-off. However, some traders think that quarter-end adjustments made Monday’s numbers look better than they really are, and the real test will come in the next few trading sessions. 

US Iran Truce Market Impact Removes a Tail Risk 

Geopolitics did as much to move markets this week as any earnings report. The US-Iran truce market impact became visible almost immediately once news circulated that the two countries had agreed to halt hostilities over the weekend and allow commercial ships to pass through the Strait of Hormuz. President Trump said peace talks would resume in Doha, with envoy Steve Witkoff traveling to the region for further negotiations. 

Oil prices quickly showed the market’s relief. West Texas Intermediate crude went back above $70 a barrel after dropping about 9% the week before, and Brent crude moved down toward the low $70s. Lower energy costs are important because they reduce business expenses and help ease inflation, which the Federal Reserve monitors closely. The CBOE Volatility Index, or VIX, dropped 4% to 17.65, its lowest level in weeks, suggesting traders were less worried about another conflict. 

Lisa Cook Fed Ruling Stocks Reaction 

Another important event came from the Supreme Court. The Lisa Cook Fed ruling stocks reaction reflected genuine relief among big investors who had devoted months to pricing in uncertainty over the central bank’s independence. The Court decided not to let the administration remove Federal Reserve Governor Lisa Cook while the legal case over her attempted firing continues, keeping her on the Board of Governors since last August. 

Treasury prices barely moved after the news, indicating that markets were not surprised and had already expected this outcome. Even so, removing this risk allowed sectors sensitive to interest rates, such as technology, to focus more on business fundamentals rather than uncertainty. When the Fed is seen as independent from political pressure, it gains credibility, which directly affects how growth stocks are valued. 

What Comes Next 

Corporate news also boosted the market. Comcast announced it will spin off NBCUniversal and Sky as a new, separate media company, which pushed its stock up 5%. Investors are also paying close attention to Micron’s upcoming earnings, since memory-chip prices are now a key part of the larger AI story. 

Still, there is no guarantee the rally will last. Experts have pointed out that gains driven by short-covering and end-of-quarter moves in struggling stocks are not the same as a real change in investor belief. The next few trading days will reveal whether this week’s gains are lasting or just a short break. Inflation is still high, the Fed’s future rate decisions remain uncertain, and Asian markets have been more cautious than those in the US. For example, Hong Kong’s Hang Seng index fell even as Wall Street celebrated. The record highs are real, but it will take the next earnings season to show if this is a true turning point or just a temporary peak. 
Source: https://www.thestreet.com/stock-market-today/stock-market-today-dow-jones-sp-500-nasdaq-updates-june-30-2026 

Washington, DC 

Nearly three-quarters of a million mail ballots landed on election officials’ desks after Election Day in 2024, and under a ruling handed down this week, every one of those late arrivals would still have counted. That single figure explains why Monday’s Supreme Court mail-in ballot ruling landed with such force in state capitols from Jackson to Sacramento. 

In a decision that scrambled the usual ideological lines, the justices ruled 5-4 that states can keep counting absentee ballots that arrive after polls close, as long as they were postmarked by Election Day. The SCOTUS election-day ballots case, formally styled Watson v. Republican National Committee, focused on a Mississippi law that allows ballots to arrive up to 5 business days late and still be counted. Justice Amy Coney Barrett wrote the majority opinion, joined by Chief Justice John Roberts and the three Democratic-appointed justices. This combination surprised many who followed the case. 

Why the Mississippi Case Became a National Flashpoint 

The Mississippi ballot ruling came after a series of lawsuits from the Republican National Committee and the Trump campaign before the 2024 election. They argued that federal law does not allow states to accept ballots arriving after Election Day, even if mailed on time. At first, a federal judge agreed with Mississippi, but the Fifth Circuit Court of Appeals, a panel of Trump appointees, later overturned that decision, ending the grace period. This set up a Supreme Court case with national consequences. 

Fourteen states and the District of Columbia currently maintain some form of post-Election Day grace period for domestic mail ballots, and roughly a dozen more extend similar flexibility to ballots cast by military members and citizens living overseas. That patchwork made the mail-in ballot grace period 2026 fight a proxy battle over how much latitude states keep to run their own elections a question the court answered, at least for now, in favor of the states. 

Justice Barrett’s opinion focused on a key detail in the law. Federal rules set a sole Election Day, but they do not say when ballots must arrive at election offices. She wrote that the voting process ends when people finish voting, not when every ballot is counted. This view allowed Mississippi’s law to remain in place without changing the overall system Congress created for national elections. 

Justice Samuel Alito, writing for the four dissenting justices, warned that the decision could cause confusion and weaken public faith. He said that counting ballots after polls close is like extending the election, which could make people doubt the results. Barrett’s opinion had already addressed this point, saying that questions about timing should be decided by lawmakers, not judges. 

The Supreme Court’s 5-4 mail-ballot decision stands out more for who joined the majority than for the close vote. Barrett and Roberts, both appointed by conservatives, sided with the liberal justices. This shows that debates about state power do not always follow party lines. As one election law expert said, letting states set their own rules can help either party, depending on the state. 

What This Means for Voters Heading Into the Midterms 

For election officials, the ruling removes a major source of uncertainty as they prepare for the fall elections. Washington’s secretary of state pointed out that over 250,000 ballots arrived late but were postmarked on time in 2024. Without the grace period, those voters would have lost their say. Rural areas, where mail takes longer to arrive, would have been hit hardest if the rule had changed. 

Voting rights advocates were quick to frame the decision as protective of exactly those voters. The outcome avoids a disorderly, last-minute overhaul of midterm election ballot rules just months before voters head to the polls, and it preserves confidence for military families and rural residents who depend on the extra window to have their ballots counted. Election officials in the eighteen states and territories with existing grace periods, Mississippi among them despite being a Republican-led state, can now finalize their 2026 procedures without fear of a court-ordered rewrite. 

President Trump, who has long pushed for firmer mail voting rules, called the decision a major loss. He again urged Congress to pass the SAVE America Act, which would require stricter voter ID and citizenship checks and limit mail voting to special cases like illness, disability, or military service. The House has passed the bill, but it is unlikely to pass in the Senate, so its future is uncertain. 

A Narrower Fight Still Ahead 

The Supreme Court’s decision does not end all debates about mail and absentee voting. On Monday, the justices asked the Trump administration to provide its opinion on a Pennsylvania case about whether voters must write a date and a statement on mail ballot envelopes for them to be counted. This issue could come back to the Court soon. The Court will also hear a case about Arizona’s proof-of-citizenship law next term, which could affect how states manage their voter rolls. 

The Supreme Court rule states to count mail-in ballots that arrive after Election Day in 2026, but it only settles the question of when ballots must be received. It does not address other issues, such as how ballots are checked, dated, or processed. Lawyers expect the upcoming citizenship-verification case, RNC v. Mi Familia Vota, to draw just as much attention when arguments start in the fall. 

The Road to November 

Monday’s ruling means that the same rules used in 2024 will stay in place for 2026, at least for when ballots must be received. That stability is important. Election officials had worried they might have to change procedures quickly, which could confuse voters and put extra pressure on already busy county offices. 

The SCOTUS mail-ballot grace-period ruling’s midterm-election impact will likely be measured less in headlines than in ballots quietly counted weeks from now, arriving a day or two late from a rural mailbox or an overseas military post, exactly as the law intended. Whether Congress moves on the SAVE America Act, whether the Arizona citizenship case reshapes voter rolls, and whether states like Mississippi choose to tighten their own laws despite this week’s outcome will determine how durable this settlement proves to be. For now, the deadline that matters most is the one voters already know: get your ballot in the mail by Election Day, and the rest, in most of the country, will take care of itself. 

Source: https://www.foxnews.com/politics/supreme-court-rules-mail-in-ballots-received-after-election-day 

Cupertino, California 

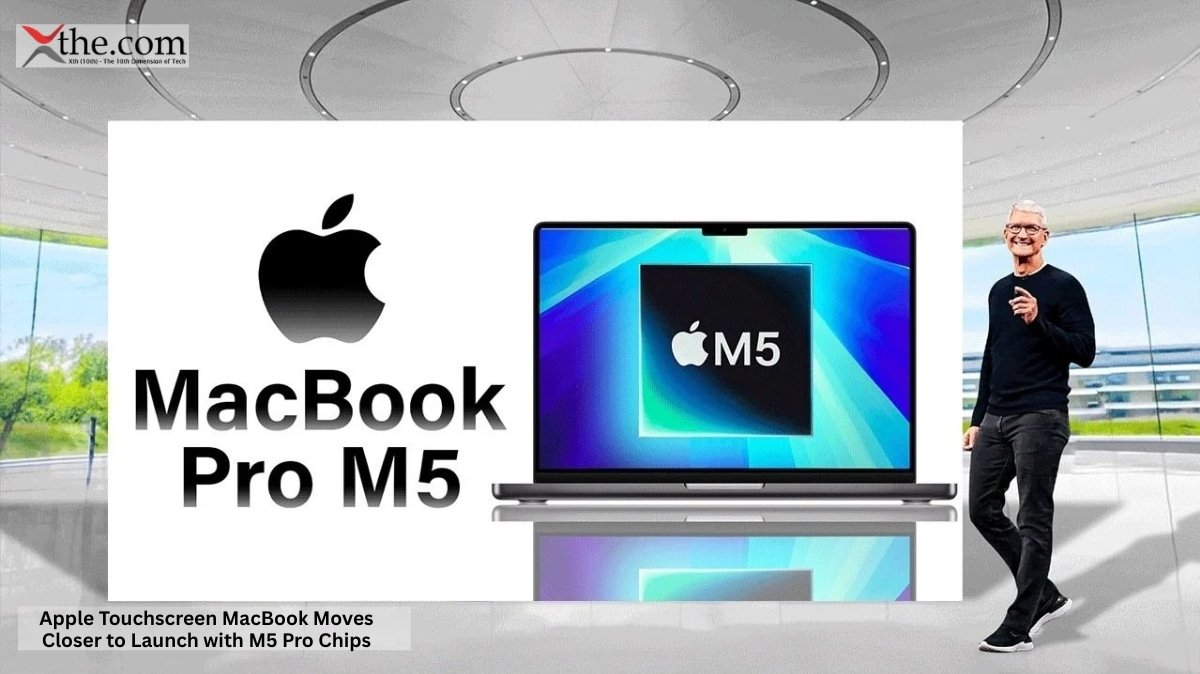
For fifteen years, Apple insisted that a touchscreen laptop was a bad idea. Steve Jobs even joked that it was like “putting a steering wheel on a refrigerator.” Now, that position is changing. Bloomberg’s Mark Gurman reports that the Apple touchscreen MacBook 2026 is not simply a rumor. It is now a real hardware project with a set production schedule, and it is coming sooner than most people thought. 

The new detail that has analysts revising their forecasts is the chip inside it. Rather than waiting for a next-generation processor, Apple’s first Apple MacBook touch display model will reportedly ship with the Apple M5 Pro touchscreen laptop configuration already sold in today’s MacBook Pro line. That decision changes the calculus for anyone currently weighing a Mac purchase, and it arrives at the most inopportune moment for buyers: in the middle of a memory-pricing shock that has already prompted Apple to raise prices across its Mac and iPad lines. 

A Fifteen-Year Reversal, Compressed Into One Product Cycle 

Apple’s choice to avoid touchscreens on Macs was intentional. For years, Tim Cook’s team maintained that touch was for the iPad, while the Mac was for exact input. This idea showed up in every keynote since the iPad’s launch in 2010. Meanwhile, Microsoft took the opposite approach with its Surface line, starting in 2012, showing there was real demand for devices that could switch between keyboard and touch input. Lenovo, Dell, and HP soon offered their own versions. Apple was the only major PC maker that stuck to its original plan. 

Now, Apple’s position is changing. According to Gurman and supply chain analyst Ming-Chi Kuo, the new MacBook is expected between late 2026 and early 2027. It will feature an OLED display, a Dynamic Island cutout like the iPhone, and Apple’s first touch-capable Mac screen. This redesign is the first major update to the high-end MacBook’s look since 2021, a period when Apple’s laptops have started to look outdated compared to Windows laptops, which get design updates more often. 

Why The Apple M5 Pro Touchscreen Laptop Decision Matters 

The most important detail in this announcement is the chip Apple chose. At first, people expected the first touchscreen Mac to use the M6 Pro and M6 Max chips. Instead, Apple is skipping the high-end M6 chips and will go from M5 straight to M7 for its Pro and Max models. This means the Apple touchscreen Mac launch date currently targeted for late 2026 or early 2027- will use chips that have already been available in the MacBook Pro since March 2026. 

This is not a step down. The M5 Pro and M5 Max introduced Apple’s Fusion Architecture, which separates the CPU and GPU while keeping unified memory. These chips offer up to four times the AI performance of the previous generation, have Neural Accelerators in every GPU core, and reach SSD speeds of 14.5 GB/s. Apple is not waiting for newer chips to add touchscreens. Instead, it is using chips that professionals already see as top-tier and building a new design around them. This move shows Apple wants to move quickly, not cautiously. 

What Touch Actually Changes For Mac Users 

Some people will point out that Apple’s approach is “touch-friendly,” not a complete redesign of macOS for touch. The trackpad and keyboard are not going away. What’s new is that users now have more options, and for three groups of users, these options matter a lot. 

Creative professionals using apps like Photoshop or Final Cut Pro have long wanted to interact directly with the screen, without needing a separate iPad. A touchscreen Mac with stylus support would let illustrators draw right on a large screen while still using full desktop software, something the iPad can’t fully match. Developers would get faster, easier navigation in complex tools, where tapping is quicker than using a cursor. Students could switch between taking notes, annotating, and typing, all on one device that works like a tablet when needed, and a full computer when it’s not. This narrows the gap between a MacBook and an iPad with a Magic Keyboard. 

This is where Apple’s longer-term thinking becomes visible. The company has spent years selling the Mac and iPad as separate philosophies. A touchscreen MacBook signals a move toward an Apple hybrid Mac-iPad strategy, even if Apple never uses that language publicly. The Dynamic Island addition reinforces the point: Apple is now porting iPhone-era interface conventions onto the Mac, narrowing the visual and functional distance between its product lines rather than keeping them deliberately separate. 

The Memory Price Spike Complicates Every Upgrade Decision 

All of this is happening while Apple raised prices on Macs and iPads in late June 2026, mostly due to a global memory shortage that has made DRAM and NAND more expensive worldwide. With the touchscreen MacBook coming soon, deciding when to upgrade has become much harder. Buyers now have to choose between paying more for current models or waiting for the new MacBook, which could also be more expensive because of its OLED screen, new design, and first-generation touch features. 

Apple’s choice to skip the M6 Pro and M6 Max for high-end models and go straight to M7 in late 2027 makes things even more complicated. The M5 Pro and M5 Max chips will stay at the top of Apple’s lineup for longer than usual, powering both the current MacBook Pro and the upcoming touchscreen model. This means it may not make sense to wait for a new chip, since the next big upgrade might not arrive until 2027, no matter which MacBook you pick. 

Touchscreen MacBook Buyer Guide 2026: Tier By Tier 

If you are waiting to buy a Mac, your decision depends a lot on which model you want. A helpful touchscreen MacBook buyer’s guide for 2026 should examine each tier separately rather than offer a single, general answer. 

If you are considering the MacBook Air, it’s best to buy now. The Air is not expected to get a touchscreen in this cycle, and its next chip update is on a different schedule. Waiting will not bring any benefits. 

If you are looking at the current 14-inch or 16-inch MacBook Pro with M5 Pro or M5 Max, your choice is tougher. These are the same chips expected in the touchscreen model, so both have the same performance. The only differences are the screen, design, and touch input. If you need a laptop now and don’t care about touch, you can buy today without worrying about missing out on performance. If you want OLED and touch, it’s worth waiting six to nine months, but be ready to pay more as an early adopter. 

Buyers on an older Intel-era MacBook Pro or an M1/M2 MacBook Pro should treat the current generation as the floor, not the ceiling. The performance jump from those machines to the M5 Pro or M5 Max is large regardless of touch capability, and waiting an additional year for the MacBook Pro touchscreen M5 Max version is reasonable only for users who specifically want the new display technology and are comfortable running on three-year-old hardware in the interim. 

The Wider Industry Signal 

Bloomberg also reports that Apple is already testing a new touchscreen model with M7 Pro and M7 Max chips, which could arrive as soon as late 2027. This shows that touchscreens are not merely a one-time experiment for Apple. The company is making touch a permanent part of its high-end Mac lineup. 

The competitive context explains immediacy. AI-focused PCs from Microsoft’s hardware partners, Qualcomm’s Snapdragon-powered laptops, and a wider industry push toward hybrid. Touch-first computing have made Apple’s decade-long abstention look increasingly like stubbornness rather than principle. Anyone searching “Apple touchscreen MacBook Pro launch date M5 Pro M5 Max chip confirmed details 2026” is asking exactly the kind of urgent buyer question Apple’s silence has left unanswered, and the company’s willingness to ship existing silicon in a new form factor suggests it would rather move fast with proven chips than wait for perfect ones. For anyone typing “Apple MacBook touchscreen first ever when to launch specs price what buyers need to know 2026” into a search bar this week, the answer is becoming clearer by the day, even as Apple has declined to comment on any of the reporting. 

What Apple does next will reveal a lot about its overall product strategy, not only about one laptop. After fifteen years of keeping the Mac and iPad separate, Apple is now making a device that blends the two. This comes at a time when memory prices, AI needs, and hybrid work are changing what people want from a laptop. The MacBook Pro coming next year might finally show that Apple is ready to follow the industry’s lead. 

Source: MacBook Ultra rumors: What to expect including the touchscreen 

Hangzhou, China 

A two-second delay between a question and its answer might not seem important, but it adds up quickly when a company faces that delay ten million times a day. DeepSeek has changed that equation. On June 27, the Hangzhou-based AI lab introduced DeepSeek DSpark AI inference, a framework that leaves the model’s weights untouched, requires no new GPUs, and is free for developers to download. Despite these advantages, it still dramatically cuts response times. DeepSeek DSpark is 85 percent faster, and unlike many AI performance claims, this one is supported by production traffic data, open-source code, and peer-reviewed technical paper. 

This release is important because it builds on a model that was already the most affordable serious option available. When DeepSeek-V4 launched in April, it pushed every closed-model provider in the West to defend a ten-to-twenty-fold pricing premium. DeepSeek V4’s faster inference was the missing piece. Speed was the only area DeepSeek had not yet pulled. Now it has: DeepSeek releases DSpark speculative decoding V4 models 85 percent faster AI inference for free in 2026, and the implications stretch from individual developer workflows to the boardroom budgets of companies running AI at industrial scale. 

What DSpark Actually Is 

DSpark is not a new model, and that difference is more important than it might seem. The Hugging Face model cards for DeepSeek-V4-Pro-DSpark and DeepSeek-V4-Flash-DSpark make it clear: both use the same checkpoints as V4 since April, but add a speculative decoding module. The model’s knowledge, reasoning, and output quality stay the same. The only change is how quickly the model produces text. 

To see why this difference matters, it helps to know how large language models generate text. A typical transformer model creates one token at a time. It produces a word or part of a word, checks the result, and then repeats the process for the next token. This is like a writer who types one letter, checks it, and then types the next. The process works, but it leaves a lot of computing power unused between steps. 

DSpark Speculative Decoding 2026: How The Fast-Forward Button Works 

DSpark speculative decoding 2026 changes that approach. Instead of checking one letter at a time, it’s like a writer quickly drafting a whole sentence in pencil, then having an editor review it all at once and erase any mistakes. A small, fast draft module suggests a group of tokens simultaneously. The full V4 model checks the entire group in a single step rather than one by one. Rejection sampling keeps the longest correct part and removes anything the draft got wrong, adding one extra token as a bonus. Since the checking step retains the same probability distribution as the original model, there is no loss in quality. The output is exactly what V4 would have produced, just much faster.pSeek’s technical paper, written by founder Liang Wenfeng and researchers at Peking University, describes the method as “Confidence-Scheduled Speculative Decoding with Semi-Autoregressive Generation.” A confidence head and a load-aware scheduler decide how many tokens to verify based on whether GPUs are busy or idle. This is what sets DSpark apart from earlier speculative decoding methods. Older frameworks like Eagle3 would draft long blocks of tokens without considering if the guesses were likely to be correct, wasting computing power. DSpark, on the other hand, chooses which guesses are worth checking. 

The Numbers: 85 Percent Faster, And Sometimes Far More 

When used in actual conditions, DeepSeek-V4-Flash users saw generation speeds increase by 60 to 85 percent compared to the previous single-token baseline, called MTP-1. DeepSeek-V4-Pro users saw improvements of 57 to 78 percent. These results are not just from lab tests. DeepSeek measured them using actual user traffic on its production servers. 

The framework was thoroughly tested with the Qwen3 model family, including Qwen3-4B and Qwen3-8B. The accepted token length, which shows how many of the draft module’s guesses pass verification, improved by 26 to 31 percent over Eagle3 and by 16 to 18 percent over another method called DFlash. Tests with Gemma models showed similar improvements, proving that this technique works beyond just DeepSeek’s own models. 

Developers who measure throughput rather than per-user latency report a wider range overall. Under strict service-level targets — 120 tokens per second per user for V4-Flash and 50 tokens per second per user for V4-Pro — aggregate throughput increases have reached as high as 661 percent in DeepSeek’s own reporting, and independent developers running the open-source release have logged speculative decoding AI throughput enhancements anywhere from 51 percent to 400 percent depending on GPU configuration and batch size. That range explains the second long-tail framing circulating among developer communities this week: DeepSeek DSpark throughput boost 51 to 400 percent open source inference optimization explained is not marketing exaggeration. It is what happens when the same architectural trick is applied to throughput-constrained systems rather than raw per-user speed. 

Why This Is The Second Punch From China This Week 

DSpark was not released in isolation. Just days before, Zhipu launched GLM 5.2, an open-weights model recognized for its large context window and strong coding performance, and offered at a flat-rate price that undercuts Western providers. Two major open-source releases from different Chinese labs in the same week show a clear trend. The open-source AI efficiency competition that began with DeepSeek’s V3 price cuts in 2025 has now broadened into a wider rivalry. Multiple Chinese labs are now competing—GLM 5.2 focuses on context and coding, DeepSeek on cost and now speed—while Western closed-model providers have struggled to keep up. 

The difference becomes even clearer when looking at pricing. DeepSeek-V4-Flash costs $0.14 per million input tokens and $0.28 per million output tokens, which is about ten to thirty times cheaper than similar models from OpenAI or Anthropic for input tokens alone. DeepSeek V4 Pro Flash DSpark deployments now combine that pricing with a speed improvement that, in practical terms, reduces the number of GPU-hours needed to serve the same volume of requests. A company spending $20,000 a month on inference compute is not looking at a marginal optimization. It is looking at a structural shift in the economics of running AI at scale. 

Why Enterprise Buyers Should Care About A Free Download 

Inference costs, not training costs, make up the biggest part of most enterprise AI budgets once a product is in production. Training is a one-time event, but inference happens every time a customer sends a message, an agent uses a tool, or a coding assistant finishes a task. A framework that reduces the time for each of these calls by 60 to 85 percent means companies rent fewer GPU-hours from cloud providers, buy fewer accelerators for their own servers, and deliver faster responses to users even if users can’t always explain why a chatbot seems slow. 

This is also where open source AI inference optimization becomes more than just a buzzword. DeepSeek released DSpark’s checkpoints and a training codebase called DeepSpec under an MIT license, the same open terms as the V4 model. Any developer can review the confidence-scheduling logic, adapt it to other open-weight models, or fine-tune the draft module for a specific use case. This level of openness is very different from how Western labs usually keep serving-layer optimizations as proprietary infrastructure instead of sharing them as research. 

What Comes Next 

The real test for DSpark won’t be DeepSeek’s own benchmarks. It will be whether independent developers are able to achieve the same 60 to 85 percent improvements when they use it with their own production traffic in the coming weeks. Early reports from the community suggest these gains are holding up across different hardware setups, though the largest throughput improvements depend on how well a deployment is already optimized. 

What’s clear now is the direction things are heading. Eighteen months ago, people wondered if Chinese open-weights models could match Western labs in terms of raw capability. That question has mostly been answered. Now, the focus is on efficiency, and in that area, the gap is not just closing it’s starting to reverse. 

Source: DeepSeek unveils DSpark, an AI breakthrough that delivers responses up to 85% faster, challenging OpenAI and Google on cost 

Long Beach, California 

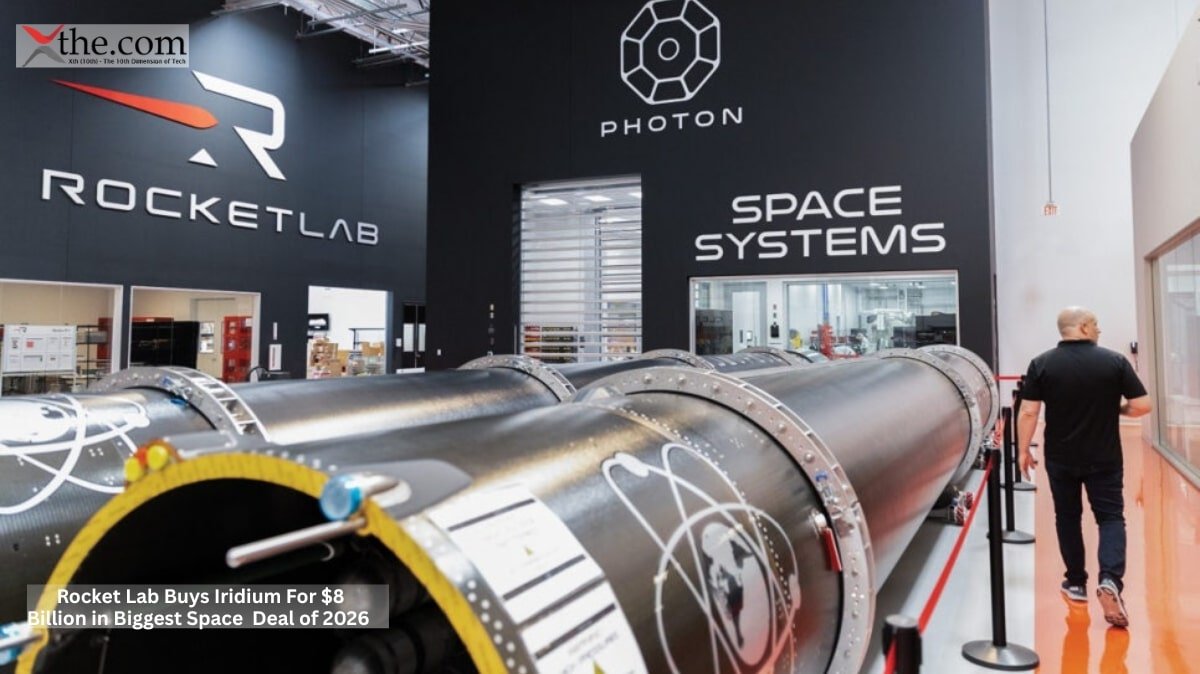
Iridium Communications shareholders saw a 24 percent premium on Monday morning, showing just how much Rocket Lab valued what Iridium had built over 30 years and the constellation’s about $6 billion in costs. The Rocket Lab Iridium acquisition isn’t just another aerospace merger. Rocket Lab, after fifteen years of proving it could reliably build and launch rockets, is now buying its way into a business that would have taken a decade and billions more to create from the ground up: a working satellite communications network with paying customers already in place. 

Rocket Lab Corporation, listed as RKLB on the Nasdaq, announced on Monday that it will acquire Iridium Communications, listed as IRDM, in a cash-and-stock deal valuing Iridium at about $8 billion. This RKLB-IRDM deal is one of the biggest consolidation moves in the commercial space sector and comes at a time when investors are especially interested in orbital infrastructure. 

The Numbers Behind the Rocket Lab $8 Billion Space Deal 

Under the terms of the agreement, Iridium shareholders will receive $54 per share in a combination of cash and Rocket Lab stock. Specifically, holders get $27 in cash plus a number of Rocket Lab shares determined by an exchange ratio set out in Monday’s statement. That Iridium $54 per share Rocket Lab payout represented a 24 percent premium over Iridium’s closing price on June 26 a figure aggressive enough to signal that Rocket Lab views the asset as scarce, not just attractive. 

The market responded quickly. Rocket Lab shares rose by up to 16 percent on Monday, and Iridium shares jumped about 25 percent. It’s unusual for both the buyer and the target to see their stock prices rise after a deal is announced. Normally, only the target’s stock goes up, while the buyer’s drops due to new debt and integration risks. This time, investors seem to think Rocket Lab has finally solved a long-standing challenge: how to grow beyond launching rockets without spending years and huge amounts of money building a new business from scratch. 

Rocket Lab needed significant resources to finance the cash part of the deal. The company secured a $3.6 billion bridge loan from Deutsche Bank and Wells Fargo and plans to use its existing cash reserves, along with additional debt and equity financing, to complete the transaction. The deal is expected to close in mid-2027, pending regulatory approval and a vote from Iridium shareholders. 

What Rocket Lab Actually Gets 

This part of the deal stands out for anyone following space industry consolidation in 2026. Iridium is not a startup with new technology and no income. It is an established company operating a constellation of 66 active satellites and 14 spares, providing phone and data services over licensed L-band spectrum. That spectrum is almost impossible to replace, as new companies spend years and significant resources trying to secure similar global rights. 

Iridium also has a strong customer base, with over 2.55 million subscribers in government, defense, aviation, maritime, and commercial sectors. These markets have long sales cycles and high switching costs, making contracts stable. Rocket Lab’s regulatory filing explains that the deal combines its launch and satellite manufacturing abilities with Iridium’s global communications network, spectrum, and partners. The result is a vertically integrated space company that designs, builds, launches, and operates its own constellations, serving millions of users directly. 

The idea of Rocket Lab vertically integrated space company is what investors are excited about. Before this deal, Rocket Lab made rockets and satellite parts for other companies’ constellations. After the deal closes, Rocket Lab will own the constellation, spectrum, ground infrastructure, and customer relationships. Everything will be managed by one company. 

Rocket Lab’s management explained the strategy clearly. They said the acquisition lets them avoid three major challenges of building a satellite communications business from scratch: getting spectrum access, waiting years for revenue after building infrastructure, and slowly building a steady customer base. In an investor presentation, the company put it simply: they found a shortcut. 

Iridium Satellite Communications RKLB: A Foothold In Markets Rocket Lab Couldn’t Reach Alone 

Besides the large number of subscribers, the filing details specific services Rocket Lab can now offer right away. The deal gives Rocket Lab a quick entry into satellite-based Internet of Things, direct-to-device services, positioning, navigation and timing, and important safety services. These are all areas where telecom and defense spending are expected to grow in the next decade. 

That Iridium satellite communications RKLB combination also folds in a 2025 acquisition Iridium itself had made: Aireon, an aviation tracking service, which Iridium bought outright in May for $367 million by purchasing the 61 percent stake it didn’t already own. Rocket Lab inherits that asset as part of the wider package, adding aviation surveillance to an already wide service portfolio. 

Any analysis of this deal has to mention the main competitor in low Earth orbit. The acquisition puts Rocket Lab in a better position to compete with SpaceX and its Starlink division, which became dominant by supplying both launch services and its own satellite communications business. SpaceX did not invent vertical integration in space, but it showed that this model can generate steady, recurring revenue rather than the variable income from launching rockets for others. 

The timing matters. The deal lands amid surging investor appetite for the space sector, with SpaceX raising roughly $86 billion in what became the largest initial public offering in history earlier this month, and the same Elon Musk-led company has signaled plans to expand its communications satellite business while developing orbital AI computing infrastructure. Rocket Lab is no longer content to be a supplier to that ecosystem. It wants a comparable end-to-end model of its own, and Iridium’s established Rocket Lab acquires Iridium in an $8 billion cash-and-stock deal on June 30, 2026. A vertically integrated space company structure gets it there years faster than building from a blank sheet. 

Peter Beck, Rocket Lab’s chief executive, stressed the ambition behind the deal. He called it one of the most transformative deals in the history of the space industry during the companies’ joint investor presentation, and this time the deal’s structure supports that claim. 

Piece Of A Broader Wave 

Rocket Lab and Iridium are not alone in making big moves. Less than three months ago, Globalstar, another major player in satellite telephony and data, agreed to be bought by Amazon for about $11 billion. Amazon plans to keep developing Globalstar’s next-generation constellation and gain access to spectrum for direct-to-device services. SES also completed its acquisition of Intelsat last year. These deals show a trend: established satellite operators with valuable spectrum rights are now highly sought after, and the buyers are often companies that already make the rockets and hardware needed to use that spectrum. 

For Rocket Lab, the plan is simple, even though it will take eighteen months to complete. Owning the entire chain rockets, satellites, spectrum, and subscribers—is where the real profits are. The big question is whether Rocket Lab can integrate a 2.5-million-subscriber legacy telecom business as smoothly as it has built and launched rockets. Regulators, competitors, and shareholders will be watching closely over the next year. If Rocket Lab succeeds, it will quietly become one of the few true end-to-end competitors to Starlink that the market has seen. 

Source: Tech Rocket Lab pops 16%, Iridium soars 25% on $8 billion space consolidation deal 

Seoul, South Korea 

Nine hundred eleven trillion won. That’s the number South Korean officials announced on Monday, which comes out to about $590 billion. This is one of the largest industrial commitments by any government in recent years. The Samsung SK Hynix $590 billion chip plan isn’t just a business move. It’s a national effort, presented by President Lee Jae Myung and the chairmen of both companies at a Seoul briefing that also sent a clear message to chipmakers worldwide. 

This announcement wraps up a remarkable week for South Korea’s two leading memory companies. It also comes as SK Hynix prepares to make another big move of its own. 

A National Strategy Disguised As A Construction Project 

If you look past the press conference, the plan itself is pretty simple, even if the numbers are huge. About 800 trillion won, or $520 billion, will go toward building four new memory chip plants in South Jeolla Province, far from Korea’s usual semiconductor hubs near Seoul. Samsung will build two of these plants, and SK Hynix will build the other two. Another 81 trillion won is set aside for an advanced packaging cluster in Chungcheong, and 30 trillion won will fund next-generation memory research over the next fifteen years. 

This is the heart of the South Korea semiconductor investment 2026 story: a government co-investing directly alongside private chipmakers, a tactic Washington has only recently begun experimenting with through its stake in Intel. Industry minister Kim Jung-kwan said the government would shorten the path from permitting to construction, compressing a timeline originally projected for the mid-2040s into the mid-2030s. That is not an incremental adjustment. It is a decision to treat memory chip capacity the way a country treats its power grid or highway system: as infrastructure too important to leave to a normal regulatory clock. 

President Lee called this effort a “great leap forward” based on three main areas: semiconductors, physical AI, and data centers. The way South Korea’s AI chip national strategy language matters here is that it signals that Seoul is no longer content to be the world’s memory supplier on the sidelines of an AI boom led by American chip designers and cloud providers. It wants the physical infrastructure of AI- fabrication plants, packaging centers, and the power and water systems that feed them- sitting on Korean soil at a scale that rivals can’t easily match. For readers trying to make sense of the headline figure itself, the short version of “Samsung SK Hynix $590 billion South Korea chip complex four fabrication plants 2026 explained” is this: two companies, four plants, one government, and a big bet that memory demand will keep rising over the next decade. 

Four Fabs, One Sold-Out Market 

The Samsung chip complex new fabs centerpiece deserves its own examination, because their timing shows what’s really driving this move. Memory chips have shifted from being basic hardware to becoming the main bottleneck in building AI systems. For example, Micron, the biggest U.S. memory maker, saw its quarterly revenue more than quadruple in a year, with profit margins jumping from 39 percent to almost 85 percent, and DRAM prices rising over 260 percent. Its stock has soared about 800 percent in the past year. SK Hynix and Samsung have seen similar growth, and right now neither can produce enough high-bandwidth memory to meet demand from Nvidia, Microsoft, and other major tech companies. 

Samsung Electronics Chairman Lee Jae-yong said Gwangju, about four hours from Seoul, is the top choice for the company’s new cluster. SK Hynix Chairman Chey Tae-won was more cautious, saying his company is still choosing a site and ensuring the necessary infrastructure is in place. He also reminded everyone that these projects take time—building SK Hynix’s Yongin campus took nine years. “A chip factory requires massive land, power, water and talent,” Chey said at the briefing, pointing out the challenges this huge project will face. 

The HBM Arms Race Behind The Numbers 

No discussion of this plan works without addressing HBM memory South Korea expansion, because high-bandwidth memory is the actual product driving the entire announcement. HBM is made by stacking layers of regular DRAM and linking them with thousands of tiny vertical channels, which lets data move much faster than with standard memory. Every major AI accelerator chip, like those inside Nvidia’s GPUs, relies on this technology. 

SK Hynix now controls between 56 and 60 percent of the world’s HBM supply, depending on which analyst you ask, and says it’s sold out through 2026 and into 2027. Samsung isn’t sitting back, though. It has started shipping HBM4 and has launched a “Super-Gap Roadmap” to regain its former lead. Samsung Chairman Lee said the company will invest in HBM factories requiring top-level processes, as well as in its current packaging facilities in Cheonan and Onyang. “HBM, which is indispensable for the training and inference of AI models, requires state-of-the-art technology for stacking semiconductor chips,” he said. 

There’s also a market value angle to this rivalry. In June 2026, SK Hynix passed Samsung to become South Korea’s most valuable public company for the first time in over 25 years, thanks mostly to its lead in HBM. Meanwhile, Samsung reported 53.7 trillion won in first-quarter operating profit from its chip division alone, showing that even as it tries to catch up in HBM, it’s still making huge profits from the overall memory shortage. 

Two Moves, One Week 

This story also ties into events in the U.S. SK Hynix has filed with the SEC to raise about $29 billion by listing American depositary receipts on Nasdaq, with trading expected to start on July 10. If it reaches the top of its range, this offering would be bigger than Alibaba’s 2014 U.S. debut and among the largest share sales ever. The money will go directly to building new facilities: the first fab at the Yongin Semiconductor Cluster, an advanced packaging plant in Cheongju, and EUV lithography equipment. 

These aren’t just two separate news stories happening at the same time—they’re part of a coordinated effort. SK Hynix is using both South Korea’s industrial policy and the world’s biggest capital market to solve one problem: it can’t build memory capacity fast enough. Listing on Nasdaq gives SK Hynix access to U.S. investors and lets people compare it directly with Micron, its main American competitor. The big investment at home provides land, permits, and government-backed infrastructure. One move brings in the money, and the other shows exactly where that money will go. 

Building The World’s Largest AI Chip City 

To really understand the scale, visualize this: this isn’t just a factory expansion. It’s more like building a whole new industrial city from scratch, focused entirely on making memory chips. Four new plants will be built in a province that doesn’t currently have any of Korea’s semiconductor supply base. There will also be a separate packaging cluster in Chungcheong and a materials and equipment hub in the southeast. On top of that, a separate 550 trillion won project—about $355 billion—will fund AI data centers built by SK Group, GS Group, and Naver. These centers aim for 8.4 gigawatts of capacity at first, and 18.4 gigawatts by 2035, supporting South Korea’s AI data center goals alongside the chip plants. 

When you add up the chip plants, packaging hub, materials cluster, and data centers, it looks more like a self-contained AI industrial zone than just an expansion of current sites. South Korea, which is a bit smaller than Indiana, is trying to build the foundation for a global AI memory supply at home, aiming to do so in about 10 years rather than several decades. 

What Could Slow It Down 

A project this daring naturally draws a lot of attention, and analysts aren’t shy about pointing out the risks. Lee Jong-ho, a professor at Seoul National University, said clearly that a project this big needs careful planning, and from the outside, it looks like things are moving faster than they should. He’s not the only one with concerns. Chey Tae-won’s comment that the Yongin campus took nine years to build already casts doubt on the government’s faster timeline for South Jeolla, even before construction begins. 

Industry experts keep mentioning three main challenges. First, the southwest region lacks sufficient power and water infrastructure for advanced chip plants, so South Korea’s grid will need a major upgrade to support both the new fabs and nearby data centers. Second, there’s a talent gap—these cutting-edge plants need lots of skilled engineers, but most of Korea’s semiconductor workforce is based around Yongin and Pyeongtaek, not the southwest. Third, memory chip markets are known for boom-and-bust cycles. Some specialists warn that the current AI-driven shortage could end sooner than the five-year plan expects, leading to oversupply and falling prices. 

Investors replied to these concerns right away. On the day of the announcement, Samsung’s shares dropped as much as 4.86 percent, and SK Hynix fell nearly 6 percent before recovering most of the loss. South Korea’s Kospi index also swung from a 3.4 percent drop to closing down just 0.2 percent. In short, the market wasn’t completely enthusiastic. Investors see the $590 billion commitment as a big gamble that demand for AI memory will keep rising rather than level off after the current data center boom. 

Where This Leaves The Rest Of The Industry 

South Korea’s two big memory companies already control most of the world’s DRAM and HBM output, and this plan aims to increase that lead. Companies like Taiwan’s TSMC, Japan’s equipment makers, and U.S. rivals such as Micron will be watching to see how quickly South Korea can build new fabs in a region without the established supply chain of Yongin or Pyeongtaek. If the government’s faster permitting process works, the southwest could become the new hub for global memory production by the early 2030s. But if problems with power, water, and talent are as tough as some expect, it could take much longer to get these plants running, giving competitors more time to catch up. 

What is not in question is the direction of travel. South Korea has decided that controlling the physical infrastructure behind artificial intelligence, not just the chip designs but the fabs, packaging plants, and power systems underneath them, is now a matter of national strategy rather than corporate balance sheets. Taken together, the announcement amounts to a South Korea semiconductor AI investment drive- Samsung, SK Hynix, new fab complex details, 2026 story that will keep evolving as ground breaks in the southwest. The next decade will determine whether the southwest of the country becomes the AI chip city its planners envision, or a warning story about building faster than the ground beneath the project can support. 

Source: South Korea unveils $880bn chip and AI investment plan 

Philadelphia, Pennsylvania 

Comcast shares had dropped by almost a third over the past year, but Monday’s announcement quickly turned things around. The stock surged up to 25% before markets opened, marking its best day in over ten years, after the company confirmed the Comcast NBCUniversal spinoff. This move completes the Comcast CMCSA split, separating its cable and wireless business from its film, TV, and theme park empire, and creates the new NBCUniversal Sky company, which will now compete directly with Netflix, Disney, and Warner Bros. Discovery in the global media market. 

This is a real, tax-free spinoff with specific executives, a clear list of assets, and a set timeline. Comcast’s board decided that keeping broadband and streaming together no longer worked for either side. The company’s financials revealed the problem: about $19.2 billion in free cash flow expected in 2025, yet the stock traded at a price-to-earnings ratio of close to 4.5. That low valuation showed investors were unsure about what they actually owned. 

What Comcast Actually Announced 

The plan splits Comcast into two separate, publicly traded companies through a tax-free deal. After the split, Comcast shareholders will own shares in both Comcast and NBCUniversal. This is important for regular investors: if you own CMCSA shares now, you don’t need to do anything. Your shares will automatically convert into ownership in both companies when the separation is complete. 

The media side will include Universal theme parks, Universal film and TV studios, NBC and Telemundo networks, the Peacock streaming service, Bravo, and the European media company Sky. The remaining Comcast entity keeps the connectivity business: Comcast Xfinity cable broadband, wireless services, and business technology platforms. Comcast plans to focus on delivering great customer experiences through its large network, which serves over 65 million homes and businesses, and its growing wireless division. 

Leadership Split Reflects Two Distinct Businesses 

The executive assignments reveal how deliberately Comcast structured this. Mike Cavanagh, NBCUniversal CEO, is now the headline appointment: Cavanagh, who has been Comcast’s co-CEO, will lead the new media company once the separation closes. Comcast co-CEO Mike Cavanagh will become the CEO of NBCUniversal. He presented the logic plainly in a statement, saying “Comcast will continue to build on its leadership in connectivity, while NBCUniversal, together with Sky, will have the scale, brands, content and financial resources to compete as a top global media and entertainment company.” 

The other half of the business will be led by a familiar leader. Former Comcast CFO Michael Angelakis is returning to run the new Comcast after the media assets are separated. Angelakis left years ago to lead the investment fund Atairos. His return shows the board wants someone with a strong finance background to lead the more focused, cash-generating connectivity business. 

Brian Roberts, Comcast’s chairman, will stay involved with both companies. The Roberts family will retain control, and Brian Roberts will work closely with Mike and Michael, focusing on new growth and opportunities arising from the split. During the investor call, Roberts directly addressed rumors, saying the split was “absolutely not” a move toward selling either company, trying to stop speculation that NBCUniversal might be for sale. 

Why Now: The Strategic Logic Behind the Split 

Comcast’s stock performance over the last year shows why this split was urgent. Shares fell about 30% over 12 months, mainly due to ongoing industry changes, not just one bad quarter. More people cut the cord, streaming competition grew, and Comcast’s broadband business met new rivals from wireless and fiber networks. Combining expensive theme parks and streaming with a steady broadband business made it hard for investors to value either part. The streaming service, which still loses money, lowered the overall value of the broadband business, which would be worth more on its own, like Charter Communications. 

This is Comcast’s second big split in about a year. The company had already separated cable networks like CNBC and USA Network into a new company called Versant. Monday’s announcement is a much bigger step, fully separating all media and entertainment assets instead of just a few channels. Evercore ISI analyst Kutgun Maral said this move reverses Comcast’s old “Harmony” strategy of keeping content and distribution together, calling it a long-awaited win for shareholders who were unhappy with the company’s lower valuation. 

What Shareholders Actually Get 

For regular investors trying to understand Comcast spins off NBCUniversal Sky into separate public company 2026 what shareholders get, the mechanics are simpler than most corporate breakups. If you own Comcast stock when the spinoff happens, you’ll automatically get shares in the new NBCUniversal company and keep your Comcast shares. You don’t need to buy anything new, and the deal is tax-free for shareholders at the federal level. The new NBCUniversal will have the same dual-class share structure as Comcast, so Roberts will keep strong voting power in both companies after the split. 

Comcast also said it plans to keep up to a 19.9% stake in NBCUniversal for up to a year after the split. The company will sell this stake gradually instead of all at once. This gives Comcast more financial leeway during the transition and shows it is not in a hurry to leave the media business right away. 

The Charter Communications Ripple Effect 

The markets saw this as more than just a Comcast story. Charter Communications shares jumped about 14% to 20% that morning, and Liberty Broadband also rose as investors reconsidered what a more focused Comcast connectivity business could mean for the cable industry. The Comcast CMCSA stock surge in 2026 didn’t just help Comcast; it boosted the entire sector, which had been undervalued for years. 

The logic is simple. If Comcast’s broadband and wireless business, now separate from media, can get a higher valuation like Charter’s, then Charter may also look more interesting to investors. People also saw this move as a sign that cable industry mergers, often talked about but rarely done, might finally happen. A standalone Comcast connectivity company is a clearer partner or acquisition target than a large company managing theme parks, streaming, and broadband. 

What This Means for Peacock and Universal 

For those following the NBCUniversal, Peacock, Universal spinoff, operations should stay the same in the short term, but changes may accelerate over time. Peacock will stay with the new NBCUniversal company, not as a separate asset. This means the streaming service will have a parent company focused solely on media, rather than competing for resources with broadband. The same goes for Universal’s theme parks and film studios, which will now report directly to a media-focused company led by Cavanagh. 

For investors specifically modeling the Comcast CMCSA NBCUniversal spinoff one-year timeline impact on Peacock streaming and Universal parks, the separation is expected to close in approximately 12 months. During that interim period, both businesses continue to operate under the existing Comcast umbrella, meaning subscribers, theme park visitors, and advertisers shouldn’t notice any immediate changes. What changes is investor scrutiny: each business now reports performance that can be measured against pure-play peers rather than being blended into a single conglomerate result, putting pressure on Peacock specifically to demonstrate a path toward sustainable profitability now that it can no longer hide behind broadband’s cash flow. 

Gazing Forward 

The next year will show whether this split delivers the value investors expect or just creates two smaller sets of problems. NBCUniversal, led by Cavanagh, enters a media landscape that is still evolving amid Paramount Skydance’s planned acquisition of Warner Bros. Discovery. The new company may soon have to decide whether to buy others or risk becoming a target itself. Comcast, under Angelakis, faces tough competition in cable and broadband from wireless and fiber companies. Both companies now have the opportunity to move faster, but they also need to prove that this speed delivers real value for shareholders, not just a short-term stock jump.

Source: Media Comcast announces it will spin off NBCUniversal and Sky from cable business 

Mountain View, California 

Four senior Gemini researchers left for rivals in just six days. Alphabet lost about $270 billion in market value over two trading sessions. Yet on Monday, the company still celebrated its Dow Jones debut with a stock pop anyway. Alphabet joins Dow Jones 2026, one of the most significant index changes in years. However, the timing highlights a company that is winning a symbolic victory while losing ground in the area that matters most: artificial intelligence. 

Alphabet’s shares rose about 4% as the company replaced Verizon Communications in the 30-stock benchmark, a change S&P Dow Jones Indices announced on June 23. The Google GOOGL Dow inclusion puts the search and cloud giant alongside four other Magnificent Seven companies already in the index: Nvidia, Amazon, Apple, and Microsoft. For a price-weighted benchmark that has sometimes lagged behind economic movements, this addition is more of a confirmation than a discovery. The Dow added Apple in 2015, years after the iPhone had transformed consumer technology, and added Goldman Sachs in 2013, after the financial crisis had already underscored the sector’s importance. Alphabet’s inclusion follows this same pattern: it is official recognition of a shift in earnings power that markets had already acknowledged. 

What Dow Inclusion Actually Means for Investors 

Alphabet Dow Jones today carries genuine, if modest, mechanical consequences. Every fund that tracks the Dow Jones Industrial Average now needs to hold Alphabet shares to match the index. This might seem important, but the numbers tell a different story. About $115 billion in assets are tied directly to the Dow, which is much less than the nearly $20 trillion linked to the S&P 500, where Alphabet has been listed for years. The required buying from Dow-tracking funds will not have a lasting effect on Alphabet’s share price. 

What really changes is Alphabet’s visibility and the story around it. Now, retail investors with Dow-linked index funds in their 401(k) plans automatically hold a share of Alphabet, even if they never chose to buy it. Financial advisers who use blue-chip benchmarks have another reason to talk about the stock with clients who might not have noticed it before. The index also shifts more toward technology. S&P Dow Jones Indices pointed out that Alphabet’s involvement in advertising, cloud infrastructure, artificial intelligence, hardware, autonomous driving, healthcare technology, and media distribution makes it a much broader representative of the communications sector than Verizon ever was. By Friday’s close, Alphabet shares were up about 11% for the year, putting it near the top of the Magnificent Seven, even after a tough June. 

That last point is important. Alphabet is experiencing its worst month since February 2022, with its stock falling in six of the last seven weeks. The boost from joining the Dow is real, but it does not change the fact that the company’s shares have been sliding overall. 

Alphabet AI Challenges 2026: A Talent Exodus With No Recent Precedent 

This is the difficult reality behind Monday’s celebration. Alphabet’s AI challenges 2026 begin with a wave of researchers leaving, which has worried even optimistic analysts. On June 19, Nobel laureate John Jumper, who spent nine years at Google DeepMind building the AlphaFold system that won the 2024 Nobel Prize in Chemistry, left for Anthropic. Just days later, Noam Shazeer, the vice president of engineering who co-led Gemini development and co-authored the important “Attention Is All You Need” paper that backs modern AI, announced he was leaving for OpenAI. Google had spent $2.7 billion to bring Shazeer back by acquiring Character.AI, but he stayed less than two years before leaving again. 

The departures only sped up. Bloomberg reported that Jonas Adler, who worked on Google’s AI coding tools, and Alexander Pritzel, who specialized in model pretraining, were also leaving for Anthropic. Soon after, a fifth researcher, Arthur Conmy, who worked on Gemini 2.5 and AI safety, posted his own move to Anthropic. That is the Google Gemini engineer exodus Anthropic story in full: four senior departures to one company in six days, and three of them were directly involved with the model Google relies on to stay competitive. 

Alphabet’s stock dropped about 7% on June 22, its biggest single-day fall in over a year, after the news about Jumper and Shazeer leaving. The stock fell further as the departures of Adler and Pritzel became public, bringing the two-day market value loss to more than $270 billion. Some analysts dismissed these exits as minor compared to Alphabet’s nearly 200,000 employees. Jefferies kept a Buy rating on Alphabet with a $445 price target, calling the departures just background noise. Others are more concerned. D.A. Davidson analyst Gil Luria told Barron’s that the main competition now seems to be between Anthropic and OpenAI, which is notable given Google’s size and chip resources. 

The timing makes the situation even more worrying. Google quietly delayed the release of Gemini 3.5 Pro to July without giving a public reason, even though the researchers who left worked in AI coding and pretraining—areas that are vital to the next flagship model. A 2025 SignalFire analysis found that DeepMind engineers were eleven times more likely to leave for Anthropic than for any other company. This trend started before the latest departures and suggests the problem is ongoing, not just a coincidence. 

Compute Scarcity: Customer Constraint and Recruiting Liability 

The second pressure point compounds the first. Alphabet compute capacity shortage Meta has become a key story in the AI infrastructure cycle. The Financial Times reported that around March, Google told Meta it could not provide all the Gemini computing power Meta wanted to buy. This restriction continued through June, delaying Meta’s internal projects and forcing the company to encourage employees to use AI tokens more efficiently. It is an awkward situation for one of the world’s most valuable companies. 

Meta had used Gemini for coding, customer service, advertising tools, and content moderation. Google’s models were said to perform better than Meta’s own Llama systems at the important but less visible job of catching scams and removing dangerous content. Now, Meta is moving these tasks to Muse Spark, its own internal model in the Superintelligence Labs division. At the same time, Meta is cutting 8,000 jobs and reassigning 7,000 laborers to focus on AI infrastructure. Meta’s 2026 capital spending is expected to be between $115 billion and $135 billion, showing how committed it is to relying less on a competitor’s models. 

Google’s own figures show why it had to ration computing power. The company is spending over $180 billion on infrastructure this year but still faces nearly $460 billion in unmet demand for Google Cloud. Instead of quietly accepting this gap, Google made a deal to lease about 110,000 Nvidia GPUs from SpaceX for around $920 million a month. This was described as temporary capacity to meet Gemini Enterprise demand. Anthropic has a similar deal with SpaceX at an even higher monthly cost. It is unusual for a company spending $180 billion of its own money to still need to rent nearly a billion dollars’ worth of chips each month to fill the gap. 

This is where the issue of computing power turns into a recruiting problem. One report linked the timing of Shazeer’s departure to a decision to move computing resources from his project to a DeepMind team in London. Google said this was to improve collaboration, but within the company it was seen as a sign of whose work was valued when resources were limited. When researchers have to compete with Meta and other customers for the same limited GPUs, it hurts morale. In other words, computing power is now more than just a cost—it affects who stays at the company and who leaves. 

Google AI Spending Investor Concern and the Pricing Question 

All of this feeds Google AI spending investor concern that extends well beyond Alphabet to the whole AI infrastructure sector. The negative view is simple: companies are spending hundreds of billions on data centers and chips, while open-source Chinese AI models are catching up in performance at much lower costs. If these cheaper options can match the quality of top models for more tasks, it becomes harder for Alphabet to justify its spending to shareholders, especially since the stock has dropped about 10% in the past month. 

The positive view looks at the same facts differently. Demand for AI computing power is growing faster than even the most bold expansion plans across the industry. Google Cloud revenue grew 63% year-over-year, and the company is limiting access to a huge customer like Meta not because demand is weak, but because supply cannot keep up. A real bubble would mean too much supply chasing too few buyers. Instead, the data show the opposite: capacity is sold before it even exists, the biggest companies are being turned away from products they want to buy, and emergency leasing deals are costing nearly a billion dollars a month. This seems less like a speculative bubble and more like a real shortage of data centers, advanced chips, and electricity. 

Alphabet’s second-quarter earnings, set for July 28, will be the next real test of which story is true. Investors will look to see if Google Cloud’s growth can keep up with the high spending, if the delayed July release of Gemini 3.5 Pro can make up for the gaps left by Adler and Pritzel’s departures, and whether the loss of talent leads to real product problems or is just background noise in a company that still brings in over $400 billion a year. 

What This Means Going Forward 

The headline ‘Alphabet Google joins Dow Jones Industrial Average 2026 stock pops 4 percent AI questions explained is the headline version of a more complicated reality: index inclusion is a lagging signal of economic weight, not a verdict on competitive position. The Dow’s shift toward technology confirms what the market already knew about Alphabet’s earnings power. It does not answer whether the company can keep the researchers behind its Nobel Prize-winning work, fix a compute shortage that limits Meta’s access, or outperform Anthropic and OpenAI as both prepare to go public. 

The Alphabet Dow inclusion day one Google Gemini talent exodus, compute shortage investor concerns will probably shape how analysts consider the company this summer. Being labeled a blue-chip brings prestige and a small boost from index funds, but it does not bring back a Nobel laureate, free up GPUs that Meta needs, or guarantee that Gemini 3.5 Pro will be strong enough in July to end the doubts that have already cost Alphabet a quarter-trillion dollars in market value. Alphabet joins the Dow as one of its most powerful companies, but whether it stays that way depends on choices made inside DeepMind and Google Cloud, not on which 30 stocks are in a price-weighted index from another era.

Source: Tech Alphabet stock pops 4% on Dow debut, but the tech giant faces major AI questions 

New York, New York 

One stock that has lost over a third of its value since January is about to report earnings, and Wall Street cannot agree whether it is worth $43 or $85. That gap alone tells you everything about the stakes riding on Nike earnings this week, the headline event in a holiday-shortened trading week that also features Constellation Brands Q3 results, JPMorgan, Micron Technology, and FedEx. These five companies are on the latest Zacks earnings surprise list June 2026, and their reports will be the first real test of whether the wider S&P 500 earnings preview June 2026 narrative strong growth, broad-based beats can hold up when two very different consumer-focused businesses are in the spotlight. 

The numbers supporting this story are clear. S&P 500 earnings for the June quarter are expected to rise 23.7% from last year, with revenues up 11.4%, according to Zacks Investment Research data from June 29. So far, 84.6% of companies that have reported May-quarter results have beaten earnings estimates. This is a strong performance for this stage of the reporting season and sets a high bar for the NKE STZ earnings June 30 releases to clear. 

Why This Week Matters More Than It Looks 

The second-quarter earnings season officially starts on July 14, when JPMorgan and other big banks report, and the full S&P 500 Q2 earnings growth picture becomes clearer. This week is more like a preseason, but it still matters. Thirteen S&P 500 companies with May-ending quarters have already reported, showing combined earnings growth of 179.5% and revenue growth of 29.5%. However, these numbers are boosted by a few big outliers and should be viewed with caution. This week, four more companies with May-quarter calendars, including Nike and Constellation Brands, will report. Their results will help traders set expectations before the flood of bank earnings. 

Micron Technology and FedEx have already set a tone of their own in recent sessions, with results that fed into the sector-by-sector estimate revisions Zacks tracks each week. Energy has been the highlight, with aggregate profit estimates up more than 90% since early April, driven by higher oil prices. Technology, Basic Materials, Utilities, and Business Services have also seen upward revisions. Strip out Energy and Tech, and the picture would actually look negative an indication that this earnings cycle, for all its headline strength, remains narrower than the aggregate numbers suggest. That makes the Nike turnaround earnings watch and the Constellation Brands report this week genuinely informative rather than incidental noise, because both companies sit outside the sectors currently propping up the index. 

Nike: The Market’s Consumer Confidence Gauge 

Nike stands out this week as the company investors are watching most closely. Its shares are down about 35% this year, a tough drop for a stock once seen as a reliable performer. The decline shows that Nike’s turnaround has taken longer than management’s original “Win Now” plan suggested. Ongoing weakness in Greater China, shrinking margins due to higher costs, and persistent tariff issues have tested investor patience for the past two years. 

What’s unusual about Nike’s situation before this report is how much analysts disagree. Some have price targets as low as $43, such as Deutsche Bank after a recent downgrade, while others expect it to reach $85. The more optimistic analysts believe that changes in wholesale channels, a more focused product lineup, and marketing around the 2026 World Cup will help Nike regain pricing power and improve margins. This wide range of opinions shows there is real debate about whether Nike’s brand can overcome its present challenges, not just short-term uncertainty. 

Investors watching Tuesday’s release should focus on four things. First, gross margin trajectory: any sequential improvement would validate management’s inventory-discipline narrative; another miss would renew the bear case. Second, Greater China revenue, which has been the single biggest drag on the turnaround story and remains the market’s preferred proxy for whether Nike’s brand strength is eroding structurally or merely facing a cyclical air pocket. Second, the direct-to-consumer versus wholesale mix, since the pivot back toward wholesale partnerships has been central to the recovery plan, and skeptics want evidence that it is working rather than simply propping up near-term revenue at the expense of brand positioning. Third, the dividend payout ratio, which has crept above 100% of free cash flow in recent quarters a yellow flag that bears have started citing more frequently. Fourth, forward guidance on tariff-related costs, since management commentary here will shape estimates for the next several quarters more than the trailing print itself. 

Options markets expect about an 8.5% move in Nike’s stock on the day of the report, showing just how uncertain investors are. If Nike beats expectations and shows real progress in China, the stock could rally toward the higher analyst targets. But if results disappoint, especially with cautious guidance, talk of new multi-year lows could return. 

Constellation Brands: The Quiet Defensive Bet 

Constellation Brands occupies the opposite end of the sentiment spectrum. While Nike has dominated headlines, Constellation shares are modestly positive for the year — up roughly 4% — a result that looks unremarkable until set against the wider consumer staples and beverage-alcohol landscape, much of which has struggled amid softening discretionary alcohol spending and altering consumer behaviors among younger drinkers. Constellation’s portfolio, anchored by Modelo and Corona, has continued to outperform peers in the domestic beer category, giving the stock defensive qualities that have attracted investors rotating out of more volatile consumer names. 

The stock’s valuation shows the same trend. Constellation trades at about 12 times its expected earnings, which is lower than most other consumer staples stocks that usually trade at much higher multiples. This lower valuation shows investor caution about growth in the beer market and concerns about tariffs on imported brands. However, if Constellation Brands’ Q3 results show it is still gaining market share, there could be room for the stock’s valuation to rise. 

The main points in Constellation’s report are simpler than those in Nike’s. First, look at beer-segment depletion rates, which show real consumer demand by removing the effects of wholesaler inventory changes. Next, check the gross margin, since aluminum costs and tariffs have been important topics lately. Also, pay attention to management’s full-year guidance. If they confirm or raise their outlook, it will support the idea that Constellation is a stable choice in an uncertain market. But if depletion rates disappoint, it could mean even the safest consumer staples are starting to feel the pressure. 

The Bigger Picture for the S&P 500 

Looking at the bigger picture, a clear trend appears. S&P 500 Q2 earnings growth has been strong overall, but most of the gains have come from Energy and Technology. Other sectors like Transportation, Medical, Consumer Discretionary, Autos, and Construction have seen their estimates cut since April. Nike’s results will be seen as a test of consumer spending on non-essentials, while Constellation’s will show how steady spending on staples is as families deal with slower economic growth. 

Anyone running a screen for this week’s notable reports the kind of search captured by phrases such as “Nike Constellation Brands Zacks earnings surprise list June 30 2026 what investors need to watch” is really asking a wider question: does the strength embedded in aggregate S&P 500 numbers hold up once you look past the sectors doing the heavy lifting? Nike and Constellation will not answer that question definitively. But as two consumer-facing companies reporting just two weeks ahead of the real Q2 season opener, they offer the clearest available preview of how discretionary and defensive spending are diverging a dynamic anyone running an S&P 500 Q2 2026 earnings season preview Nike NKE Constellation Brands STZ results analysis will want to track closely. 

The main event is still on July 14, when JPMorgan and other big banks will set the mood for the rest of the Q2 earnings season. Until then, this week’s reports are like a dress rehearsal for investors and for Nike, it’s a rehearsal with real stakes, as the stock could swing anywhere between $43 and $85 based on the results.

Source: JPMorgan, Micron, FedEx , Nike, Constellation Brands are part of Zacks Earnings Preview 

Houston, Texas 

About 40% of companies testing autonomous AI agents have stopped before reaching production, based on several industry surveys this year. The main issue is not the AI model itself, but the supporting infrastructure. On June 16, HPE and Nvidia addressed this problem by expanding the HPE Nvidia AI Factory. This full-stack architecture is designed for the next stage of enterprise computing, where agents take action instead of just answering questions, such as chatbots. 

The announcement, made at HPE Discover in Las Vegas, introduces three new features to HPE Private Cloud AI, the companies’ jointly developed platform. The Nvidia Vera CPU now leads a new compute layer designed for managing AI agents. The Nvidia Agent Toolkit adds tools for governance and monitoring agent behavior in real-world use. Nvidia Confidential Computing brings hardware-based data protection to the entire system, a key requirement that has slowed agent deployments in finance, healthcare, and government for nearly two years. 

Why HPE And Nvidia Are Betting On Agentic AI Infrastructure 

Generative AI was built to answer questions. Agentic AI, on the other hand, takes actions such as querying databases, executing trades, rewriting code, or escalating tickets, all without human approval at every step. This shift completely changes the infrastructure requirements. If a chatbot makes a mistake, it only wastes time. But if an autonomous agent with access to a financial system makes a mistake, it could move money, it should not. 

HPE CEO Antonio Neri explained that as AI becomes more autonomous, organizations need systems designed to run it securely, manage it responsibly, and scale it efficiently. Nvidia CEO Jensen Huang agreed, saying that every part of the computing stack is being redesigned for what he calls the age of AI agents. 

This redesign is exactly what HPE agentic AI infrastructure has been designed to deliver: not just a faster chip, but a coordinated package of computing, networking, governance software, and security hardware. This allows a CIO to move an agent from a test environment to a real production workflow with customer data, without having to rebuild the security model from the ground up. 

The Vera CPU: A Compute Layer Built For Reasoning, Not Just Throughput 

The main new hardware is the HPE ProLiant Compute DL394 Gen12, which uses the Arm-based Nvidia Vera CPU. This is where Nvidia Vera CPU enterprise AI workloads find a dedicated home. Unlike GPU-centric training clusters, the Vera CPU targets the sequential logic required by agentic reasoning. It manages tasks such as chaining decisions, evaluating tool calls, running reinforcement learning loops, and processing complex fiscal models, where single-core performance and RAM bandwidth are more important than mere parallel processing power. 

The server provides about 1.2 terabytes per second of memory bandwidth, enabling faster multi-step agent reasoning in real workloads. For example, a financial reconciliation agent that goes through 10 steps can maintain its state between decisions instead of starting over each time. HPE has combined the chip with iLO 7 firmware and a secure enclave that meets NIST’s quantum-resistant security standards. This is important for regulated companies making long-term infrastructure choices. The DL394 Gen12 will be available in fall 2026, with HPE Private Cloud AI support coming in 2027. 

The Vera CPU is part of the larger Vera Rubin platform, which powers extensive deployments. The HPE Nvidia Blackwell GPU AI Factory remains the main option for current projects. The new Vera Rubin NVL72 rack-scale system is designed for advanced models with over one trillion parameters. The HPE Compute XD700, built on Nvidia HGX Rubin NVL8 and supporting up to 128 Rubin GPUs per rack, increases capacity for companies with the largest training and inference needs. 

Governing Autonomous Agents Before They Become A Liability 

Computing power by itself does not solve the trust issue. This is where the Nvidia Agent Toolkit production deployment enters the picture. The toolkit includes Nvidia Nemotron open models, the NemoClaw blueprint, and the OpenShell secure runtime. HPE calls this an agent operating system, software designed to monitor agent behavior in real time, enforce governance policies, and flag problems before they become bigger risks. 

In practice, this acts as a permissions layer for autonomous software. HPE Private Cloud AI now allows secure local agent registration, so IT teams can approve which models, skills, and tools an agent can use based on central policies. This prevents agents from accessing systems without approval. New HPE Zerto features help by detecting unauthorized agent actions and providing continuous data protection, so the environment can be restored to a clean state if an agent misbehaves when no one is watching. 

Imagine a customer service agent who can issue refunds over an extended period. Without governance tools, a logic mistake or a harmful prompt could cause thousands of unauthorized operations before anyone notices. With the Agent Toolkit’s policy enforcement and Zerto’s rollback feature, such problems can be caught and fixed quickly rather than found much later during an audit. 

Confidential Computing: The Missing Piece For Sensitive Workloads 

For the past two years, enterprise security teams have asked the same question before allowing AI agents near regulated data: who can see the data while the model is working on it? Encryption protects data when it is stored or transmitted, but data being processed is usually exposed in memory. This creates a risk that attackers or even cloud providers could exploit. 

HPE Confidential Computing AI tackles this risk by bringing Nvidia Confidential Computing to the entire HPE AI Factory lineup. Every chip in the Vera Rubin series now includes built-in hardware protection. This keeps model weights and sensitive data encrypted even while in use, and this is verified by hardware, not just a vendor’s policy. For example, a hospital using diagnostic agents on patient records or a bank using fraud-detection agents on transactions can move from pilot projects to full production that meets compliance standards. Nvidia Confidential Computing will be generally available for HPE AI Factory in the fourth quarter of 2026. 

The Networking Backbone: Spectrum-X And BlueField 

All of this depends on networking that can move huge amounts of data between thousands of GPUs without slowing things down. Nvidia Spectrum-X BlueField enterprise infrastructure is now the standard networking layer for HPE’s AI Factory, combining Nvidia Vera BlueField-4 DPUs and ConnectX-9 SuperNICs with Spectrum-X Ethernet switches. Nvidia’s benchmarks show about 1.6 times higher AI communication speed compared to regular Ethernet, which makes a big difference when training models or supervising multiple agents. For large or sovereign deployments, HPE also offers Nvidia Quantum-X800 InfiniBand through the HPE Cray Supercomputing GX5000, allowing customers to scale up without changing their governance or security setup. 

The Bigger Picture: HPE’s Full-Stack Bet Against The Hyperscalers 

This is where comparisons with AWS and Google Cloud help enterprise buyers make decisions. AWS Bedrock Agents and Google’s Gemini Enterprise Agent Platform, which replaced Vertex AI Agent Builder, both offer mature, API-based ways to use agentic AI and are closely tied to their own cloud systems. For companies already using AWS for data storage or BigQuery for analytics, this built-in integration is valuable and hard to match elsewhere. 

HPE and Nvidia are offering something different: the HPE Nvidia AI Factory expansion Vera CPU, Agent Toolkit Blackwell GPU agentic AI enterprise 2026 as a deployable, on-premises or as a hybrid setup, with hardware, networking, governance software, and confidential computing all packaged together, instead of being pieced together from various cloud services. For regulated industries that need data control, or for organizations concerned about ongoing cloud costs at scale, this full-stack ownership model delivers a unique value compared to API-based solutions. It is not meant to replace Bedrock or Gemini Enterprise, but provides an alternative for buyers who want to own the infrastructure, not just use it. 

This difference is especially clear when it comes to HPE Nvidia AI infrastructure for agentic multi-agent systems and confidential computing in enterprise deployments. Most large cloud providers use software-based isolation and contracts to manage data. HPE’s approach uses hardware-based confidential computing, which can prove that data was never exposed in clear text, no matter who runs the infrastructure. For defense contractors or multinational banks navigating data residency laws, this can be the deciding factor when choosing a solution. 

What Enterprise IT Buyers Should Take From This 

The rollout will happen in stages, not all at once. New HPE Private Cloud AI features will be available in July 2026, and HPE Data Fabric Software will come in October. Most of the agentic observability tools and Confidential Computing will be generally available in the fourth quarter. The Vera CPU server will be ready for production in fall 2026, but full Private Cloud AI integration will not happen until 2027. 

This timeline is important for planning. Companies looking at agentic AI now should see this announcement as an outline for planning and budgeting, not as a product they can use right away. Organizations that start early with governance, secure agent registration, and confidential computing will be better prepared when all features become available than those that wait until everything is ready. 

Autonomous agents are on the way, ready or not. HPE and Nvidia believe that the companies that succeed in the coming years will be those that establish strong control systems before agents start acting independently.

Source: HP accelerates enterprise workflows with OpenAI Frontier