Beaverton, Oregon 

Nike’s stock, which was above $180 less than three years ago, opens today’s session near $40, and tonight that 78 percent collapse meets its moment of truth. Nike’s Q4 earnings on June 30 will be released after the closing bell, and the NKE stock earnings today event holds more significance than any Nike report in a decade. The swoosh has lost more market value than many companies are worth, and Wall Street is watching to see if the decline is finally over. 

According to Yahoo Finance, analysts expect Nike’s Q4 revenue to be between $10.85 billion and $10.9 billion, which is about 2 to 4 percent lower than last year and matches management’s forecast. Earnings per share are expected to be around 11 cents, down from 14 cents a year ago. For most large retailers, these numbers would not stand out. For Nike, though, they mark another step in a decline that has erased tens of billions in investor value and forced the company to admit its business model needs fixing. 

The Nike fiscal 2026 results Context: How a Sneaker Giant Lost Its Footing 

To understand tonight’s report, it helps to look back at the strategy shift that started the decline. When John Donahoe was CEO, Nike focused heavily on selling directly to consumers and moved away from wholesale partners who had sold its shoes for years. Stores like Foot Locker, Macy’s, and many regional retailers lost access and priority as Nike pushed more inventory to its own app and website. The idea was to cut out the middleman, keep more profit, and control the customer relationship. But in reality, this left a gap. Smaller brands like On, Hoka, New Balance, and other running-focused labels took over the wholesale shelves Nike left behind, attracting shoppers who wanted more choices instead of just one big brand. 

The result was a textbook case of Nike revenue decline 2026 dynamics: market share erosion that compounded quarter after quarter, even as the wider athletic apparel market kept growing. Nike’s full-year fiscal 2026 earnings per share are forecast at $1.49, down 31 percent from $2.16 in fiscal 2025, a brutal two-year stretch that parallels the stock’s own trajectory. Greater China has been a particular wound. Management flagged on the Q3 call in March that Chinese revenue would likely fall approximately 20 percent in Q4, a consequence of deliberate marketplace cleanup and reduced sell-in to distributors carrying excess inventory. The strategy is intentional pain, not accidental decline, but intentional pain still shows up on the income statement. 

Inside the Nike turnaround plan: Win Now 

CEO Elliott Hill, who took over from Donahoe in late 2024, has focused on a strategy called “Win Now.” The plan is to repair relationships with wholesale partners, restore product innovation that had slowed, and balance direct sales with the fact that many customers still want to try shoes in stores. Tonight’s call will be carefully watched for signs that this turnaround is starting to work, not just slowing the decline. 

Stifel analyst Peter McGoldrick summed up the market’s doubts by lowering his price target to $50 from $56 and keeping a Hold rating. He said he is not ready to say the stock has bottomed because Nike is still losing market share. McGoldrick expects revenue to remain about the same in fiscal 2027, suggesting the turnaround could take longer than some hope. On the other hand, BTIG’s Robert Drbul lowered his target to $55 from $75 but kept a Buy rating, believing that most of the inventory problems are already reflected in the price. This split—one analyst cautious, the other more optimistic, but both lowering targets—shows how uncertain the investment outlook is right now. 

Why Nike gross margin tariffs Pressure Is the Number Everyone Is Watching 

The most important number for the stock tomorrow is gross margin. Tariff costs have increased Nike’s expenses for over a year, and the company has used discounts to clear extra inventory. Both factors have hurt profits. This quarter, there is a twist: tariff refunds not included in earlier forecasts are expected to give a one-time boost. However, if you remove that benefit, the core results should be similar to previous predictions. Analysts will look beyond the headline to find the real margin trend. 

If gross margin holds steady or improves, it would show that Hill’s focus on pricing and cleaning up sales channels is working. This would mean Nike can sell fewer products but make more profit, instead of relying on promotions. If margins worsen, it would suggest Nike is still struggling with high tariff costs and excess discounted inventory in wholesale channels. Wall Street expects the stock could bounce back to $45-$48 if margins improve and the China business stabilizes. If China’s revenue decline is less than the expected 20 percent, or if management says the inventory cleanup is nearly complete, that could help support the stock price. 

The World Cup Wildcard 

Beyond the worries about earnings, there is a positive factor: the 2026 FIFA World Cup. The tournament is bigger than ever, with 48 teams and 104 matches across the United States, Canada, and Mexico. Nike is not an official FIFA sponsor that role belongs to Adidas, which has held the rights since 1970. Still, Nike supplies uniforms for twelve national teams, including Australia, Brazil, Canada, South Korea, Croatia, France, England, Norway, the Netherlands, the United States, Turkey, and Uruguay. This puts Nike on the uniforms of some of the sport’s most popular teams. Adidas has more teams overall, with fourteen, but Nike’s teams include big markets like Brazil and France, which are strong for jersey sales, no matter who the official sponsor is. 

This is important because Nike has often made a big impact at World Cups through creative marketing, even without official sponsorship. For example, the 1998 ad with Brazil’s team playing football in an airport is still one of the most famous sports commercials, and it was made without FIFA’s approval. With an estimated six billion viewers for this tournament, even a small boost in jersey and shoe sales could help Nike’s revenue, separate from its restructuring actions. However, investors should not expect this effect to show up in tonight’s Q4 results, since the tournament started on June 11 and most sales will be counted in the first quarter of fiscal 2027. Still, it is an important factor in Nike’s turnaround that should be discussed on the earnings call. 

NKE stock price 2026: Buy, Hold, or Wait? 

For retail investors parsing the Nike fiscal Q4 earnings report June 30 2026 revenue decline turnaround plan results explained, the honest answer is that conviction should hinge on gross margin path and China commentary, not on the headline revenue or EPS miss that the market has already priced in. A stock down 78 percent from its highs has already absorbed years of bad news; the question is whether tonight’s report confirms the bottom or extends the wait. Investors asking Nike NKE stock earnings June 30 2026 what analysts expect and whether to buy before report ought to weigh the bifurcated analyst sentiment carefully: a Hold rating from Stifel reflecting genuine uncertainty about the pace of recovery, against a Buy rating from BTIG betting that depressed expectations create asymmetric upside. 

For most retail investors, the sensible move is to wait until the earnings report comes out rather than buying before it does. With a P/E ratio around 28, Nike is not cheap relative to its current earnings, and a weak update from China or further margin pressure could push the stock even lower before any World Cup boost helps. Investors who already own shares have a good reason to be patient, since fiscal 2027 earnings per share are expected to recover to about $1.85 as restructuring and tariff issues improve. For new investors, there is little benefit in buying just before a major event, when the same information will be available the next day with less risk. 

Nike’s turnaround was always going to take more than one quarter. Tonight’s results will show whether Hill’s efforts are ahead of schedule or whether it will take several more tough quarters to recover. Either way, the company’s next chapter begins as soon as the numbers are released.

Source: Nike Q4 earnings, Nike stock, Nike turnaround, NKE earnings, Nike fiscal 2026  
New York, New York 

The $200 laptop RAM kit you bought last year may cost $400 by the end of 2027. That is not hyperbole. That is the arithmetic of a Jefferies Equity Research forecast that should alarm anyone planning to buy a computer, phone, gaming console, or tablet in the next 18 months. 

Memory chip prices surge: 2026 projections from Jefferies show a 40 to 50 percent rise in Q3 2026 versus the current quarter, followed by another 30 to 40 percent hike in Q4. In 2027, the firm projects a further 40 to 45 percent year-on-year increase. The only meaningful relief on the horizon arrives in 2028 and even then, it arrives modestly. 

This is not a blip. This is a structural repricing of the entire consumer technology ecosystem. 

Jefferies Memory Forecast 2026: The Numbers Behind the Warning 

The Jefferies memory forecast 2026 lays out a stark trajectory. Cloud Service Providers are locking down 50 percent of total memory capacity a share that could rise to 70 percent — by signing two-year long-term agreements that require a 40 percent prepayment. No consumer electronics players have signed these agreements. That asymmetry is the entire story. 

AI hyperscalers Microsoft, Google, Amazon, Meta are essentially buying memory futures at scale, pulling the available pool away from PC makers, smartphone manufacturers, and gaming hardware companies. The consumer market gets whatever is left. 

Microsoft has reported paying two-and-a-half times as much for memory now as at the end of last year and expects costs to double again by late 2027. Apple has noted it has never experienced such rapid increases in component prices. Those cost increases do not stay inside corporate earnings reports. They move downstream, fast. 

The Gas Station Analogy That Explains Everything 

Think of global DRAM supply as a single fuel pipeline. AI data centers are the industrial buyers refineries, airlines, shipping fleets that lock in contracts for the bulk of the flow. Whatever trickles through to the retail pump is priced at whatever the market will bear, because supply is tight and getting tighter. 

HBM demand, AI data center DRAM pressure are the root drivers. The big three memory makers Samsung, SK Hynix, and Micron have prioritized high-bandwidth memory production for AI accelerators, and China’s CXMT, widely hoped to be a source of cheaper supply, has not materialized as a disruptive force. 

CXMT’s DRAM technology lags 1.5 to 2 generations behind global leaders. Without EUV lithography, the company cannot upgrade to DDR6 or HBM3E. The “cheap Chinese memory” thesis was, in the words of sector analysts, a myth. 

DRAM Price Increase Q3 2026: What’s Already Breaking at Retail 

The DRAM price increase Q3 2026 is not a future event. Its effects are already visible across the consumer electronics landscape. 

Apple raised iPad and MacBook prices by hundreds of dollars this month, with Tim Cook confirming that iPhone prices will follow. The Steam Deck recently saw a 50 percent price increase, partly due to memory costs. Microsoft raised Xbox hardware pricing. Each of these decisions traces back to the same supply chain constraint: the companies building AI infrastructure are consuming memory at a pace that the existing global manufacturing base cannot keep up with. 

“Jefferies warns DRAM memory prices surge 40 to 50 percent Q3 2026 and 30 to 40 percent Q4 no relief until 2028” — that headline, read carefully, describes an 18-month window in which every major consumer hardware category reprices upward simultaneously. Laptops, phones, tablets, gaming consoles, and even budget Chromebooks carry DRAM and NAND. None are exempt. 

DRAM NAND Price Surge Q4 2026: Who Wins, Who Loses 

Markets rarely produce a crisis that hurts everyone equally. The DRAM NAND price surge Q4 2026 creates a clear divide between shareholders and consumers. 

Samsung SK Hynix memory pricing power has never been stronger. Both companies — alongside Micron — are sitting on a seller’s market that their own production decisions helped engineer. With no new wafer capacity growth projected for 2027 and only 15 to 20 percent new capacity expected by 2028, the oligopoly retains pricing control through the end of the decade. Investors holding positions in Samsung, SK Hynix, or Micron are, structurally, positioned on the right side of this shortage. 

Consumers are on the other side. Smartphone shipments are expected to fall 15 percent in 2026 due to higher prices and weaker demand. The PC market is projected to decline by 11.3 percent. These are demand destruction numbers — the market signal that price increases have exceeded what buyers will absorb. 

The dynamic described by “why AI cloud demand is locking up DRAM capacity and pushing memory prices higher for consumers in 2026” is not abstract. It is the reason a budget gaming laptop that cost $799 in January 2026 may cost $1,100 by Q1 2027. The AI infrastructure build-out, essential as it may be for long-run productivity, is extracting a direct and immediate tax from ordinary technology buyers. 

Memory Shortage No Relief 2028: The Long Road 

Memory shortage no relief 2028 is the defining constraint of the current cycle. Even Jefferies’ optimistic 2028 scenario assumes only a 15 to 20 percent increase in supply — modest relative to the demand trajectory that AI infrastructure spending has set in motion. 

China’s NAND technology is expected to become more globally competitive and could catch up by 2028 — but that remains a 2028 story, not a 2026 or 2027 one. For the near term, the market structure is locked. Long-term agreements between hyperscalers and the major producers have already allocated most of the available supply, leaving consumer electronics manufacturers to compete for scraps at premium spot prices. 

What to Buy Now: A Practical Guide Before Prices Go Higher 

The one actionable takeaway from the Jefferies report is timing. If you need to buy, buy now. Here is how to think about it by category. 

Laptops and PCs. Configurations available today reflect pricing before the Q3 surge lands at retail. A system purchased in July 2026 will almost certainly cost more in the same spec by October. If an upgrade is on your roadmap for the next 12 months, accelerate the purchase. 

Smartphones. Apple has telegraphed iPhone price increases. Android flagships from Samsung and others face the same input cost pressures. Mid-cycle upgrades bought within the next 60 days avoid the repricing wave for new models arriving in fall 2026. 

Gaming Consoles and Handhelds. Console prices are already moving. The Steam Deck’s 50 percent hike is a leading indicator, not an anomaly. Anyone sitting on a planned console or handheld purchase should treat current prices as a closing window. 

RAM and SSDs. For those purchasing memory and storage directly, carefully reviewing your requirements and buying what you need now can help you avoid the impact of price hikes, especially since smaller configurations may see those increases sooner. DDR5 kits and NVMe drives at today’s prices represent a meaningful discount relative to where the market heads by Q4. 

Refurbished and Pre-Owned. The secondary market for certified refurbished devices currently reflects older pricing. That window is narrowing as dealers adjust, but it remains a legitimate path to avoiding the sharpest near-term increases. 

The memory market has entered a cycle unlike any in recent history. Supply is structurally constrained. Demand from AI infrastructure shows no deceleration. The producers who control global output are operating with pricing power they have not held in decades. For consumers, 2026 and 2027 represent a period of sustained hardware inflation with no historical playbook — except the oldest one: buy what you need before it costs more.

Source: Samsung Newsroom 

Austin, Texas  

Oracle Stock Crash 2026: When the Bill Arrives for a Borrowed Future 

Oracle shares closed at $148.53 on June 26, capping a 19% weekly decline — the steepest since August 2001, when the stock fell 20% during the dotcom bust. The selloff erased roughly $80 billion in market capitalization. For a company whose market cap peaked near $900 billion just nine months ago, that number lands like a verdict. 

The Oracle stock crash 2026 did not arrive without warning signs. It arrived because investors finally did the math — and the math on Oracle ORCL worst week territory tells a story about a company that has staked its future on AI infrastructure it cannot yet fully monetize, using borrowed capital at a scale that would make most CFOs lose sleep. 

This is not a routine correction. This is a structural reckoning. 

The Four Failure Signals Driving the Oracle $130 Billion AI Debt Crisis. 

Signal One: A Capital Expenditure Number That Broke Its Own Forecast 

Capital spending jumped 162% to $55.7 billion in fiscal 2026, overshooting the company’s own $50 billion guidance. That is not modest overspending. That is a company building faster than it planned, in a market where demand signals remain strong but cash does not. 

Think of Oracle data center capex spending this way: imagine a luxury hotel developer who borrowed heavily to build 500 rooms, then decided mid-construction to add 80 more without renegotiating the loan. The rooms may eventually fill. The debt accrues regardless. 

Oracle spent nearly triple what it spent in fiscal 2025 on property, plant, and equipment — chasing cloud infrastructure capacity alongside Amazon, Microsoft, and Google. The difference? Those companies can sell a full technology stack. Oracle is still assembling its competitive position while the bill compounds daily. 

Signal Two: Negative Free Cash Flow at a Scale That Demands Attention 

The result pushed free cash flow to a negative $23.7 billion, ballooning from a deficit of just $394 million the year before. 

Oracle’s negative free cash flow 2026 of nearly $24 billion in a single fiscal year is not a rounding error — it represents a fundamental shift in the company’s financial character. Oracle built its reputation as a cash-generation machine, the kind of enterprise software business that reliably returned capital to shareholders. That identity is, at least temporarily, gone. 

The hotel analogy extends here. The property is under construction. Guests — in Oracle’s case, cloud customers — are signing long-term contracts and booking rooms. Remaining performance obligations, the contracted revenue Oracle has yet to recognize, ended the quarter at $638 billion, up 363% from a year earlier and $85 billion higher than just three months before. More than half of that backlog is tied to a single customer: OpenAI. The bookings look extraordinary. But the hotel is not yet generating enough room revenue to service its construction loans. 

Signal Three: $130 Billion in Debt and Counting 

The Oracle $130 billion AI debt figure is the centerpiece of investor anxiety. Total debt stood at $156.2 billion at the end of May, comprising $149 billion in long-term debt and $7.2 billion in short-term obligations. A year earlier, total debt was roughly $87 billion. 

Oracle was sitting on about $130 billion in debt at the end of May, with capital expenditures rising 162% to nearly $56 billion in the 2026 fiscal year. The variance between the $130 billion figure widely cited and the more precise $156 billion reflects the speed at which Oracle’s balance sheet is changing — the number has been a moving target. 

That debt does not sit idle. It accrues interest. It constrains flexibility. And it amplifies downside risk if AI adoption timelines slip or if a customer of OpenAI’s significance were to renegotiate or delay. One concentrated relationship backing $319 billion in backlog is a feature in a bull case and a catastrophic vulnerability in a bear case. 

Signal Four: Planning to Borrow $40 Billion More 

In fiscal 2027, Oracle plans to raise $40 billion through debt and equity financing, including a $20 billion share sale announced earlier, after $43 billion in debt sales and $5 billion from equity issuance last fiscal year. 

This is the signal that broke investor patience. The market had already absorbed the capex numbers and the negative cash flow. When Oracle disclosed it intended to add another $40 billion in financing — including a dilutive equity offering — the message was clear: this cycle is not ending soon. ORCL investor analysis now centers on whether the company can grow into this capital structure before the cost of carrying it overwhelms the income statement. 

The Ellison Factor: Absent at the Earnings Call, Falling on the Billionaire Rankings 

Larry Ellison, Oracle’s co-founder, was absent from the earnings call this month, leaving dual CEOs Clay Magouyrk and Mike Sicilia and recently appointed finance chief Hilary Maxson to answer questions. “Hilary has a tough life,” Magouyrk said on the call. 

That line, meant as a passing joke, became the inadvertent tagline for the week. 

Oracle Larry Ellison’s net worth drop has been swift and visible. Because of Oracle’s retreating stock price, Ellison has been surpassed on the world’s list of wealthiest people by Google co-founders Larry Page and Sergey Brin, Amazon founder Jeff Bezos, and Michael Dell. Ellison’s absence from the call raised questions that the earnings presentation could not answer — about strategic conviction, about the internal read on where this trajectory leads, about whether the architect of Oracle’s AI ambition is prepared to defend it publicly. 

The company’s headcount shrank 13% to 141,000 employees during fiscal 2026, with a notable pullback in sales and marketing, raising questions about Oracle’s ability to diversify its customer base while simultaneously scaling infrastructure. A company cutting its sales force while betting its balance sheet on a single hyperscale customer relationship is not operating from a position of comfort. 

Wall Street Divided: Buy Ratings vs. Structural Warnings 

The analyst community on the Oracle stock crash June 2026 causes has not reached consensus, and that disagreement itself is instructive. 

Evercore analysts, who recommend buying the stock, wrote in a note on Wednesday: “We expect financing/leverage and the pace of equity issuance to remain the central investor debate near term, even as demand signals stay strong.” That framing — bullish on demand, cautious on structure — represents the more optimistic camp’s honest read. The revenue growth is real. Total revenue rose 21% to $19.2 billion. Cloud revenue jumped 47% to $9.9 billion, led by a 93% surge in cloud infrastructure. Non-GAAP earnings came in at $2.11 a share, up 24% and ahead of estimates. 

Piper Sandler maintained a constructive view, with analysts writing that they “believe ORCL will remain debated, but we are constructive on ORCL’s AI-driven consumption growth.” On the other side, the Oracle data center capex collapsehas caused free cash flow to swing by more than $23 billion in a single year — a trend that has prompted others to flag structural cash flow deterioration as a concern that growth metrics cannot paper over indefinitely. 

What History Says About the Oracle ORCL Stock Worst Week Since 2001 Dot-Com Bust 

The historical pattern matters here, and it cuts in two directions simultaneously. 

Since its 1986 IPO, Oracle has fallen 25% or more in a single month only 10 times — most recently in June 2026, down about 29%. The last time the stock fell this hard in a single month was August 2001, near the bottom of the dot-com collapse. 

In the month following a 25%-plus monthly crash, Oracle posted an average loss of 8.8%. Six months out, Oracle returned an average 21.7% and a median 36%, positive two-thirds of the time. A year later, the average ballooned to 113%, though the median settled at a still-powerful 93%. 

That recovery data is real — but it masks a critical nuance. Following the 2001 crash, Oracle did not immediately recover. Investors who bought the initial dip absorbed further losses before the longer-term rebound materialized. The Oracle $130 billion AI debt situation is fundamentally different from 2001 in one important respect: the company then was burning cash on speculative enterprise software deals. Today, it is burning cash on physical infrastructure, backed by signed customer contracts. Whether that distinction justifies a faster recovery — or whether the debt load creates a ceiling on any rebound — is the question that $56 billion capex negative free cash flow investor analysis must ultimately answer. 

The Reckoning Ahead 

Oracle’s revenue trajectory is not the problem. Cloud infrastructure revenue growing 93% in a single year would, in any other capital structure, be cause for celebration. The problem is that the company building this infrastructure has taken on debt at a pace that now requires almost perfect execution — strong utilization rates, continued AI demand, a compliant credit market, and a diversified customer base — to justify the risk premium investors are being asked to absorb. 

The hotel is nearly built. Whether it achieves the occupancy rates its debt covenants assume will determine whether fiscal 2027 becomes the year Oracle grows into its balance sheet — or the year the market decides the rooms are priced too high for the uncertainty they carry.

Source: MLQ News 

Boise, Idaho 

Micron Technology reported the kind of quarterly numbers that companies dream about. Revenue of $41.46 billion against analyst estimates of $35.84 billion. Gross margins expanded to 84.6%. A Q4 guidance figure of $50 billion that shattered the Wall Street consensus of $43.58 billion. The stock surged 15 percent in after-hours trading on June 24. Then, two sessions later, it fell nearly 7 percent. Micron stock drop 2026 has become the defining market paradox of the summer a company posting numbers that obliterated expectations, only to reward investors with a savage sell-off. 

If you hold MU, SNDK, or WDC, this week should serve as a master class in the structural forces now working against the memory trade, even as the underlying business has never looked stronger. 

Why “Buy the Rumor, Sell the News” Played Out in Textbook Fashion 

The Micron earnings beat sell-off wasn’t a random event. It was arithmetic. Micron stock had already surged more than 270 percent in 2026 ahead of the June 24 earnings report. When a stock is at those levels during earnings week, the price already reflects a best-case outcome. Any result short of miraculous disappoints the marginal buyer. Any result that qualifies as miraculous simply confirms what the most aggressive bulls already priced in leaving no one left to push the stock higher. 

After a 31 percent earnings surprise, the previous quarter still produced a nearly 20 percent one-week drop; the lesson was already written: guidance, not the earnings beat itself, drives the stock’s reaction. Micron Q3 confirmed it again. The afternoon after stellar numbers hit the tape, the stock opened the next session red. By Friday, June 26, MU stock falls after earnings had become the dominant market narrative. Micron’s stock price declined 6.69 percent on Friday, dropping from $1,213.56 to $1,132.33, with 86 million shares traded a volume surge that accompanied the decline. 

Understanding the mechanics of the pullback matters less than understanding the three structural forces beneath it. These aren’t noise. They’re signals. 

Reason One—Apple and Microsoft Are Looking for an Exit From Western Memory Suppliers 

Apple confirmed the severity of the memory cost crunch when it raised Mac and iPad prices on June 25, unable to absorb the increase in memory costs. That headline, which rattled consumer tech investors, contained a sharper implication for memory chip stocks decline: the world’s most profitable consumer electronics company a buyer with extraordinary negotiating leverage cannot absorb these prices. That makes it an existential incentive to find alternatives. 

Reports emerging from Silicon Valley and Cupertino this week pointed to both Apple and Microsoft actively exploring sourcing arrangements with Chinese memory producers—a move that would route critical DRAM NAND supply concerns 2026 directly around Micron, SanDisk, and SK Hynix. The memory shortage shaking Apple and Microsoft was described as an existential crisis for smaller players, and that framing cuts both ways. If the shortage persists, hyperscalers have every economic incentive to accelerate sourcing in China. If they succeed, Micron loses pricing power on standard DRAM contracts precisely when HBM remains constrained. 

The irony is brutal. Micron’s pricing discipline—the same discipline that produced 84.6 percent gross margins—is now compelling its largest customers to fund the development of competing supply chains. 

Reason Two—HBM Capacity Constraints Cap Near-Term Revenue Even as Demand Explodes 

High-bandwidth memory is the product that defines Micron’s current valuation. HBM3E and HBM4 products are fully booked through 2027, with demand extending into 2028, and Micron secured $22 billion in strategic customer agreements, including $18 billion in cash deposits. That sounds like unambiguously good news. In one sense, it is. In another, it is precisely the problem. 

When supply is already fully allocated through 2027, the company cannot generate incremental revenue from incremental demand. A hyperscaler that wants more HBM today cannot get it from Micron. CEO Sanjay Mehrotra disclosed that Micron can fulfill only 50 percent to two-thirds of customer demand in the medium term a structural supply deficit that continues to amplify pricing power. But investors pricing “Micron MU stock falls 6 percent after blockbuster earnings, three reasons investors need to know” into their search bars this week have already absorbed the implication: if supply is capped, revenue growth has a ceiling, and that ceiling was partially visible in the Q4 guidance beat itself. Wall Street had expected $43.58 billion. Micron guided $50 billion still constrained by what it can physically produce, not what it can sell. 

A Chosun Biz report revealing that SK Hynix was slowing its next-generation HBM4 capacity expansion in favor of commodity DRAM sparked a broader tech-sector selloff and a 10 percent plunge in South Korea’s KOSPI index, heightening investor fears that the hyper-growth cycle for AI-specific memory hardware may be approaching a peak. Whether or not the HBM super-cycle has peaked is a question no analyst can answer with certainty. The market, however, has already moved. 

Reason Three—AI Infrastructure Cost Fears Are Repricing the Entire Semiconductor Sector 

The third force is the broadest and, arguably, the most consequential. The AI infrastructure buildout has generated staggering returns for Nvidia, Micron, and SanDisk, as well as for the semiconductor ETFs that hold them. But memory stocks’ June 2026 decline reflects growing investor anxiety: at some point, the cost of building AI infrastructure must translate into revenue. Alphabet and Nvidia two companies with the most direct exposure to AI capital spending sat out the broader megacap tech bounce this week. That is not coincidence. 

Memory chip stocks came under heavy pressure Tuesday, extending a broad technology selloff on Wall Street as investors grew increasingly uneasy about the enormous sums being poured into artificial intelligence infrastructure. The concern isn’t that AI demand is fabricated. Micron’s numbers confirmed it’s real. The concern is that the pace of infrastructure investment cannot be sustained indefinitely without monetization. If Alphabet and Microsoft slow their data center buildout even marginally DRAM and NAND demand softens faster than any current model anticipates. 

The “why memory chip stocks MU, SNDK, WDC are falling despite strong Micron Q3 earnings June 2026”question has a clean answer: when the fear shifts from supply scarcity to demand durability, the valuation multiple compresses even as earnings expand. 

The Contagion Spreads to Sandisk and Western Digital 

The SanDisk WDC stock drop June 2026 played out in sympathy with Micron, and the losses at both names were disproportionate to any company-specific deterioration. Option traders turned moderately bearish on SanDisk Corporation, with shares down 10.36 percent on June 26, despite no negative fundamental news from SanDisk itself. 

The synchronized drop came just one trading session after a coordinated rally in which MU gained 9 percent, SNDK gained 9 percent, and WDC climbed 3 percent the entire memory complex trading as a single thematic unit on AI memory supercycle sentiment. These stocks move together because institutional positioning treats them as a sector rather than as individual companies. When the sector narrative wobbles, all three names pay the price regardless of underlying fundamentals. 

For investors holding semiconductor ETFs with heavy memory weightings, this dynamic matters more than any individual earnings print. The sector beta amplified by extraordinary year-to-date returns means that position sizing and risk management now matter as much as fundamental analysis. 

 What Comes Next for MU, SNDK, and WDC 

Micron’s business is structurally stronger than at any point in its 48-year history. The company’s market cap has surpassed $1 trillion, revenue has more than quadrupled year-over-year in fiscal Q3, and CEO Mehrotra has signed 16 long-term strategic customer agreements spanning three to five years with financial commitments totaling $22 billion. These are not the metrics of a company facing a cyclical peak. They are the metrics of a company that has embedded itself into the core infrastructure of the AI economy. 

But the lesson of June 26 is that extraordinary metrics, priced in advance by a stock that has risen 700 percent over twelve months, generate selling pressure rather than buying interest when they arrive. The three structural headwinds Chinese memory alternatives, HBM capacity ceilings, and AI infrastructure cost anxiety will not resolve in a single quarter. Memory chip stocks’ decline may extend further before it stabilizes. 

The investors who emerged from this week with the clearest picture are those who understand that memory stocks falling June 2026 represent a sentiment reset, not a fundamental reversal. The next entry point in MU, SNDK, and WDC will likely come when fear peaks—not when earnings do. 

Source: Cathie Wood Aggressively Buys Coinbase; What Other Crypto Stocks ARK Invest Holds, Latest Holdings List Revealed 

Seoul, South Korea 

For the past 13 years, Micron Technology has traded at a 35% higher valuation than SK Hynix. This difference was not about technology, but about location. 

That structural disadvantage is about to end. The SK Hynix US listing 2026 set to debut on Nasdaq on July 10 is the most significant semiconductor capital markets event since Nvidia reached a trillion-dollar valuation. The South Korean memory giant plans to raise about $29 billion by issuing American Depositary Receipts at $166 each. If SK Hynix HSBC valuation analysts are correct, investors buying at that price are getting a discount. HSBC expects the listing to increase SK Hynix’s price-to-book ratio from 2.8 to 3.4, implying about 20% upside from the indicative listing price. 

Why the SK Hynix IPO Nasdaq Move Is About More Than Capital 

On the surface, the story is simple: a leading chipmaker needs funds to build more factories. SK Hynix plans to use the money to construct new production facilities in South Korea. However, the strategy goes beyond just financial consideration. 

HSBC’s outlook for SK Hynix now highlights what the bank calls “more proactive shareholder-friendly initiatives and better accessibility to global investors.” In other words, the Korea Exchange has consistently undervalued one of the world’s key semiconductor companies, and the Nasdaq listing is meant to correct that. 

The “Korea discount” is a well-known issue. Worries about corporate governance, being close to North Korea, and limited liquidity in Seoul’s market have kept even top Korean stocks undervalued. Over the past 13 years, Micron has traded at an average premium of 35% to SK Hynix. HSBC says this is due to better access to US investors and more shareholder-friendly policies, not better technology or market status. 

That 35% figure deserves to sit with investors for a moment. SK Hynix has supplied the majority of the HBM memory AI demand 2026 requires, yet its home-market valuation has reflected a persistent institutional blind spot. US fund managers have been underweight Korean semiconductors not because the fundamentals are weak, but because accessibility has been poor. A Nasdaq ADR eliminates that friction overnight. 

The HBM Premium: What SK Hynix HBM Chip Demand Really Means 

High-bandwidth memory is not just another product. It is the most important bottleneck in AI infrastructure, and SK Hynix has a level of control over the supply chain that few semiconductor companies have ever reached. 

Wall Street analysts have raised their price targets for SK Hynix, noting that its HBM capacity for 2026 is already sold out and that supply shortages are expected to continue into 2027. Every Nvidia H100 and Blackwell GPU requires HBM3E stacked memory placed directly next to the processor die, and SK Hynix supplies it. When major companies like Microsoft, Google, Amazon, and Meta compete for GPUs, they are also competing for SK Hynix’s products. 

HSBC raised its price forecast for SK Hynix from 2.9 million won to 4 million won, citing strong HBM pricing and the impact of the Nasdaq listing as the main drivers. These two factors go hand in hand. AI infrastructure spending is driving demand, while the US listing brings in capital and greater recognition of the company’s value. 

The company’s market value recently surpassed $2 trillion following a strong AI-driven rally, making it one of Asia’s most valuable semiconductor firms. This is not just speculation. It shows the strength of HBM3E pricing, long-term customer commitments, and a product roadmap. HBM4 development has already started, keeping SK Hynix ahead in memory technology for years to come. 

SK Hynix Stock US Listing Premium: The Nasdaq Effect in Practice 

The SK Hynix stock US listing premium thesis is grounded in structural market forces, not hype. Consider what Nasdaq index inclusion has historically done for stocks with sufficient liquidity and market cap: passive fund flows from index-tracking ETFs create systematic buying pressure that is entirely disconnected from quarterly earnings cycles. 

If the $29.4 billion raise happens at the expected price, it would be one of the largest global listings, second only to SpaceX’s record share sale earlier this month. This size almost makes certain that discussions about index eligibility will start right away. If SK Hynix is quickly added to the Nasdaq-100, as SpaceX was, it would gain access to trillions of dollars in passive capital that currently does not invest in the company. 

SK Hynix said the ADR listing will expand its investor base, “ultimately allowing its true corporate value to be properly evaluated,” and added that the move will “elevate our standing as a global company by broadening our touchpoints in the United States, the epicenter of AI technological innovation.” 

These statements show that SK Hynix is aiming for more than just a one-time capital raise. The company wants to become a regular part of US institutional portfolios, joining Nvidia and Taiwan Semiconductor Manufacturing Company as a key memory infrastructure stock in every major AI investment strategy. 

SK Hynix vs Samsung Market Cap: A Historic Reversal With Competitive Consequences 

The SK Hynix vs Samsung market cap dynamic has already shifted in ways that would have seemed implausible five years ago. SK Hynix briefly overtook Samsung to become South Korea’s most valuable publicly traded company a reversal that does not reflect just AI tailwinds, but a deliberate strategic bet on HBM that Samsung has struggled to match at the same yield and performance levels. 

That competitive gap matters enormously for SK Hynix Nasdaq IPO HBM AI chip demand valuation premium calculations. Samsung is still the world’s biggest memory chipmaker by volume, but in the AI era, volume is less important than margin, yield, and next-generation performance. SK Hynix leads in all three areas of HBM. 

The US listing adds a new kind of competitive pressure. If SK Hynix achieves a valuation on Nasdaq similar to or higher than Micron’s, Samsung will have to reconsider its own approach to international capital markets. While it would make sense for Samsung to cross-list, its complicated governance and broad business structure make that much harder. For now, SK Hynix’s Nasdaq listing gives it a valuation advantage that Samsung lacks. 

SK Hynix US Stock Listing 2026 HSBC Says Worth 20 Percent More Than Korea Share Price: The Risk Calculus 

Events of this size in the capital markets always come with risks. Technology stock valuations have been under pressure as investors question whether AI infrastructure spending can continue to grow at its current pace. Memory is a cyclical business, and the same factors that pushed HBM prices up could reverse if large tech companies slow their spending sooner than expected. 

There is also the execution question. ADR liquidity, particularly in early trading sessions, can create price dislocations that bear no relationship to fundamental value. Investors who chase the listing-day price action on the SK Hynix US stock listing 2026 HSBC says worth 20 percent more than Korea share price thesis may be buying into short-term momentum rather than the structural re-rating HSBC is describing. 

The more disciplined HSBC actually recommends a more disciplined approach: buying at the $166 indicative price, which is 8 to 9 times forward earnings and much lower than Micron’s double-digit multiple. This difference is the main point. If US institutional investors value SK Hynix like Micron, given its stronger position in the HBM market, the 20% upside estimate could be conservative.xt 

The July 10 debut date may change, but the overall trend is clear. SK Hynix’s HBM chip demand remains the primary supply constraint for AI hardware, and its Nasdaq listing turns that strength into an investment opportunity for global investors. HSBC’s 20% premium prediction is not the highest possible outcome; it is the starting point for what a careful re-rating could look like when the world’s top AI memory company is no longer limited to a market that has undervalued it. 

Samsung is paying attention, and so are all the institutional investors who have had to buy Micron as a stand-in for a company they could not invest in directly. That barrier goes away on July 10, and the new capital will value HBM memory AI demand 2026 in a way the Korea Exchange never could.

Source: CNBC News 

New York, New York  

On the last trading day of the week, Cathie Wood made a clear statement through ARK Invest’s daily trade disclosures for Friday, June 26. The firm made one of its biggest portfolios shifts this year by fully exiting Alibaba and buying more shares in top US companies focused on artificial intelligence, crypto infrastructure, and commercial space. Anyone following Cathie Wood ARK trades June 2026 saw the numbers left little room for interpretation. 

ARK sells Alibaba BABA: 570,391 shares offloaded across ARKK, ARKW, and ARKF in one session, totaling about $54.2 million. The day before, ARK had already sold another 176,004 Alibaba shares worth around $17.6 million. Over two sessions, Wood cut more than $71 million in ARK sells Alibaba BABA exposure. This is not trimming. This is closure. 

ARK Invest Buys SpaceX: The Second-Largest Acquisition of the Day 

The headline grab belongs to the Alibaba exit, but ARK Invest buys SpaceX is the position that deserves equal scrutiny. ARK purchased 45,728 shares of Space Exploration Systems Corp (NASDAQ: SPCX) worth nearly $7.01 million across four ETFs—ARKK, ARKQ, ARKW, and ARKX. That breadth of deployment across four separate funds signals conviction, not opportunism. SpaceX recently completed a $25 billion bond offering across five tranches and is reportedly evaluating a Starlink-branded mobile service for US consumers two catalysts that reinforce ARK’s bullish posture on the company. SpaceX’s stock has corrected significantly since its IPO debut, and ARK has used prior dips to accumulate aggressively, having acquired $32.4 million in SPCX shares following a 16% decline. 

Cathie Wood Coinbase COIN: A High-Conviction Dip Play 

Cathie Wood Coinbase COIN position is arguably the most tactically interesting trade of the day. ARK bought 68,366 shares of Coinbase Global (NASDAQ: COIN) across ARKK, ARKW, and ARKF, totaling about $9.7 million. This was ARK’s biggest purchase by dollar value that day. The buy came after a smaller Coinbase purchase on Thursday, showing ARK’s renewed interest in the crypto exchange after a week-long break from crypto buying. 

Cathie Wood’s ARK Invest dumps $54 million, Alibaba buys SpaceX, Coinbase, Palantir, June 27, 2026, captures a portfolio rotation driven in part by Coinbase’s low valuation. Coinbase’s stock is down about 23% to 30% this year, depending on the timeframe, after missing Q1 2026 earnings. Revenue was $1.41 billion, below the $1.52 billion estimate, and the company registered a $1.49 loss per share instead of the expected $0.27 profit. Most of this loss resulted from a $718 million non-cash markdown on Coinbase’s crypto investment portfolio, an accounting adjustment, not a sign of business problems. 

ARK seems to be looking past these short-term issues. Coinbase holds almost $516 billion in customer assets, manages over 25% of all USDC in circulation, and earns significant revenue from stablecoins, derivatives through the Deribit acquisition, and its Base Ethereum Layer 2 network. USDC on Base already supports 90% of AI agent transactions on-chain. This long-term infrastructure is what Wood values, not just the quarterly trading revenue. 

ARK Buys Palantir PLTR: Accumulating Into the Decline 

ARK’s buys Palantir PLTR followed a familiar pattern. ARK bought 41,601 shares of Palantir Technologies (NASDAQ: PLTR) across ARKK, ARKW, and ARKF, totaling about $4.5 million for the session. This came after buying 30,528 Palantir shares on Thursday, worth around $3.3 million. Palantir’s stock is down about 39% this year, dropping from a 52-week high of $207.52 to recent lows near $106. Wedbush still rates the stock as Outperform, with a $230 price target, implying over 60% upside from current levels. 

ARK’s strategy with Palantir fits its usual approach: buying strong companies when their stock prices are low. Palantir’s government and commercial AI contracts remain solid, and its US commercial revenue continues to grow. The stock’s decline reflects concerns about increased AI competition, not a real problem with Palantir’s business. 

Why ARK Is Exiting Chinese Tech Entirely 

The ARK Invest ARKK portfolio June 2026 tells the story of a firm methodically reducing geopolitical risk exposure. The Cathie Wood dumps Alibaba trade was not spontaneous. Alibaba has faced scrutiny from multiple directions: Anthropic publicly accused the company of AI model distillation practices that violated its usage policies, and Chairman Joe Tsai’s AI investment ambitions have raised concerns among institutional investors about capital allocation discipline. Alibaba’s stock briefly hit a 52-week low on June 25. 

For ARK Invest ARKW ARKF latest trades June 2026 portfolio changes explained for investors, the thesis is clear: US regulatory risk on Chinese equities has not disappeared, the bilateral technology competition is intensifying, and the same capital can be deployed into domestic AI and crypto infrastructure plays where ARK has higher analyst conviction and fewer regulatory overhangs. 

What This Tells Retail Investors 

Three signals worth isolating from ARK’s Friday activity. 

First, the Coinbase accumulation is a classic “buy the dip” in a high-beta asset where short-term sentiment has diverged from structural fundamentals. ARK is not chasing price momentum. It is buying revenue infrastructure stablecoins, derivatives, and the Base network—at a cyclical discount. Retail investors watching the ARK Invest ARKK portfolio June 2026 should distinguish between Coinbase’s trading-revenue volatility and its platform value. 

Second, ARK’s $7 million investment in SpaceX across four ETFs is a significant, diversified position. ARK’s ongoing buying suggests it sees the recent price consolidation after SpaceX’s IPO as a good entry point, not a red flag. While Argus has started coverage with a Hold rating due to valuation concerns, ARK is focused on the long term. 

Third, the Alibaba exit is as much a risk-management signal as a thesis signal. When a fund sells $71 million in a stock across two sessions, it is not making a price call. It is removing a risk category from the portfolio. The ARK sells Alibaba BABA across three ETFs is a structural decision, not a reaction to a one-day price move. 

Retail investors who copy ARK’s trades without considering the holding period may misunderstand the strategy. ARK buys undervalued stocks, holds them through ups and downs, and looks at returns over five years. If history repeats, the Coinbase position could look much better at $250 than it does now at $160. The real question is whether retail investors can wait that long or handle the drops along the way. 

The velocity and scale of Friday’s trades signal that the ARK Invest ARKW ARKF latest trades June 2026 portfolio changes indicate a deliberate portfolio architecture one that bets on domestic AI infrastructure, crypto settlement rails, and commercial space at the expense of Chinese tech exposure. Wood is not hedging. She is concentrating. Whether that concentration proves prescient depends entirely on which of those long-duration theses resolves first and how much volatility the market tolerates in the interim.

Source: Cathie Wood’s ARK sells Alibaba stock, buys Coinbase and Palantir 

Cupertino, California 

On Monday, June 23, a base Mac Studio M3 Ultra costs $3,999. By Thursday, June 26, the same model was $5,299. There was no new chip, no new screen, and no faster SSD. The exact same machine was $1,300 more expensive in just 72 hours. This is the Apple MacBook price increase 2026 at its most dramatic, and it is not a minor adjustment. It is the most significant price hike Apple has made in decades, and the reason lies in every AI server farm from Virginia to Singapore. 

The industry calls the Apple Mac price hike memory chip crisis “RAM-ageddon.” Despite the dramatic name, the situation is simple. High-bandwidth memory, or HBM, which is the dense and fast DRAM used in AI accelerators, is now extremely scarce in consumer electronics. In 2026, AI data centers are using about 70 percent of the world’s high-end DRAM supply. That means there is less available for laptops, tablets, and desktops that people and businesses rely on. 

What Tim Cook Said—and What It Means 

Apple CEO Tim Cook addressed the issue directly. He described it as a “hundred-year flood” for memory and storage costs, telling The Wall Street Journal, “I’ve never seen anything like it in any area in over 40 years.” This is significant, coming from someone who has managed Apple’s supply chain through events such as the tsunami in Japan, COVID lockdowns in Zhengzhou, and US-China trade skirmishes. The Tim Cook memory-cost warning carries weight precisely because Apple has historically absorbed component shocks rather than passing them on to customers. 

Apple explained, “We’ve never seen component prices rise this much or this quickly. Until now, we have protected our customers from these increases, but we have now reached a point where we need to begin raising prices.” The words “need to begin” matter. They do not mean prices have already peaked. Instead, they suggest that more price increases could be coming. 

The numbers explain why this is happening. TrendForce reports that DRAM contract prices jumped about 90 percent in the first quarter of 2026 and another 60 percent in the second quarter. Memory and storage now cost about four times as much as they did less than a year ago. The Apple DRAM shortage 2026 is not a supply chain blip. Micron CEO Sanjay Mehrotra expects these tight conditions to last beyond 2027, saying the company does not currently have “line of sight as to when memory supply will be able to catch up with increasing demand.” 

The Specific Models Hit Hardest 

The Apple Mac Studio new price jump from $3,999 to $5,299 is the biggest single increase, at 33 percent overnight, but it is not the only one. The base MacBook Air with 512 gigabytes now costs $1,299, up from $1,099. The entry-level MacBook Pro with 1 TB of storage went from $1,699 to $1,999. The MacBook Neo, Apple’s budget laptop released in March, rose from $599 to $699. If you customize your device with more memory, the price can go up by several hundred dollars at checkout. 

The trend is clear: devices that need more memory have seen bigger price increases. For now, the iPhone, Apple Watch, and AirPods are not affected. These products use less DRAM per unit, and Apple seems to be protecting its most popular and profitable category ahead of the iPhone 18 launch in September. Analysts think the memory shortage could add about $200 in component costs for each new iPhone, especially for models with more storage. 

Microsoft’s Xbox Confirms the Pattern 

Apple is not the only company raising prices. On the same day, Microsoft said it would increase the price of its Xbox game console by $100 to $150, depending on the version, and would stop selling Xbox consoles with two terabytes of memory, its top configuration. Valve’s Steam Machine launched at $1,919 for its two-terabyte model, which was higher than planned due to RAM costs. When companies like Apple, Microsoft, and Valve all make similar pricing moves in the same week for the same reason, it shows the problem is structural, not just a temporary cycle. 

Deutsche Bank analysts framed it plainly: “The production of memory chips is becoming a zero-sum game. For every wafer devoted to HBM stacks for AI servers, others are unavailable for smartphones, PCs, or vehicles.” 

Apple Stock Drops 6 Percent—What the Market Is Saying 

Apple’s stock dropped 6.12 percent to close at $275.15 on June 25, 2026—its worst single day since April 2025. The Apple stock drops 6 percent, a reaction that shows a specific investor worry: Apple almost never raises prices mid-cycle. Doing so signals that cost absorption has hit a ceiling. Evercore ISI analyst Amit Daryanani said, “price hikes between product cycles are extremely unusual for Apple and raise the risk of some pressure on demand for Macs and iPads.” 

On the other hand, some investors point to Apple’s latest quarterly results as an indication of strength. In Q2 2026, Apple’s revenue grew 17 percent year-over-year to $111.2 billion, with a gross margin of 49.3 percent. Customers who paid 22 percent more for iPhones last quarter are unlikely to leave the Mac ecosystem over a $200 price increase. Wall Street analysts have a consensus price target of $314.42, with 30 Buy ratings. The 6 percent drop could be a buying opportunity, or it might be the start of a longer decline in demand. The July 30 earnings call will be the first real test. 

Buy Now or Wait? A Practical Analysis for MacBook Buy Now or Wait 2026 

This is the main question for executives, small business owners, and power users who need to decide whether to buy now. The answer depends on your needs, but for most people, it now makes sense to buy sooner rather than later. 

The case for buying now: Micron does not expect the shortage to ease until 2027, and while prices could drop if the memory market stabilizes, Micron does not see that happening soon. Apple’s statement that they “need to begin raising prices” implies that current prices are the lowest we will see for a while. Waiting six months will probably not bring lower prices; it is more likely to mean another round of increases, especially if the iPhone 18 passes on the next wave of higher costs. 

The three-year total cost-of-ownership argument: Consider a knowledge worker or small-business team using a Mac Studio M3 Ultra at the new $5,299 price point instead of paying for cloud AI subscriptions. A team of five paying $40 per user each month for a premium AI assistant would spend $2,400 a year, or $7,200 over three years. The Mac Studio, even at the higher price, can run AI tasks locally at no extra cost per use, keeps sensitive data off the cloud, and still has value after three years. Over that time, owning the device can save money and protect privacy for data-heavy work, even with the price increase. 

The case for waiting: If your current machine is functional and you can defer purchase until late 2027, new fab capacity from Micron’s Idaho and New York expansions may begin to relieve supply pressure. The risk is that you are waiting on a timeline defined by semiconductor construction schedules, which are inherently unpredictable. 

For most people who need a machine now, the “Apple MacBook Mac price increase 33 percent memory chip shortage AI data center demand June 2026 is a reset, not a temporary change. The days of lower prices are over. 

The More Profound Structural Question 

The why Apple MacBook iPad prices went up overnight June 2026, and whether to buy now or wait, has a simple answer on the surface: memory costs. But there is more to it. Back in 2023, no one expected AI data centers would use 70 percent of the world’s high-end DRAM by 2026. The chip shortage was not caused by any one company; it resulted from years of AI research and a huge surge in investment during 2024 and 2025. 

What has changed for good is Apple’s place in the memory market. For years, Apple’s size gave it power over suppliers. Now, Apple is in talks with Intel about making custom chips and may shift some production away from TSMC as it looks for new supply options. This process will take years. In the meantime, Apple’s prices reflect a new balance set by the world’s biggest AI companies, not by Apple itself. 

People who buy this month pay today’s prices. Those who wait are betting on a memory market that Micron, Deutsche Bank, and Apple’s CEO all say will be tight until at least 2028. That is a long time to wait for a price drop that might never come.

Source: Apple’s Mac Price Hike: $5,299 Local AI vs the Cloud 

Austin, Texas 

On one Friday afternoon in June 2026, Oracle shareholders saw about $80 billion in market capitalization to evaporate. The Oracle ORCL worst week since the 2001 dotcom crash, forcing institutional investors to rethink their positions and leaving retail investors facing a 19% weekly loss with no clear bottom in sight. The 2026 Oracle stock crash was not caused by a sudden panic or new regulations. Instead, it came down to simple math. The company spent so much that it created a serious cash-flow problem, leaving even its most loyal analysts struggling to reconcile the company’s growth story with its financial reality. 

The Numbers That Triggered the Sell-Off 

Oracle spent $55.7 billion on capital expenditures in fiscal 2026—a 162% increase over the prior year. To put that figure in human terms: Oracle built more data center infrastructure in one year than most sovereign wealth funds invest over ten years. The company described this as a bold bet on AI cloud infrastructure. For now, Wall Street responded by selling the stock. 

This heavy spending led to a cash flow position that has no flattering interpretation. Oracle’s free cash flow was negative $24 billion for the year, meaning the company used $24 billion more than it generated from operations after investments. For a mature software company that used to deliver steady, predictable returns, this is a major shift. 

Compounding the concern, Oracle’s $130 billion total debt load now sits on the balance sheet as a structural weight. The company has announced plans to raise an additional $40 billion through a combination of new debt issuance and equity offerings. That decision—raising capital from shareholders and creditors simultaneously while generating negative free cash flow—is the financial equivalent of building luxury hotels on borrowed money, with occupancy rates remaining deeply uncertain. The hotel looks impressive. The debt service is real today. The guests have not fully arrived. 

The Oracle AI Debt Crisis Behind the Headlines 

The strategic thesis at Oracle is clear: hyperscale AI model training and inference require massive, purpose-built data center capacity, and whoever owns that capacity at scale will command pricing power and long-term recurring revenue. Larry Ellison has made this bet loudly and repeatedly, positioning Oracle Cloud Infrastructure as the alternative to Oracle vs Amazon Microsoft cloud dominance. The argument has merit in theory. 

The problem is execution risk and timing. Amazon Web Services and Microsoft Azure each entered the cloud era with decade-long head starts, deeply embedded enterprise relationships, and the luxury of building infrastructure gradually as demand materialized. Oracle is attempting to compress that timeline dramatically—spending $55.7 billion in a single year to catch infrastructure that rivals built over ten years. The Oracle $56 billion capex 2026 number is not an error. It is a deliberate gamble that AI-driven demand will materialize fast enough to generate the cash flows necessary to service $130 billion in total obligations while simultaneously funding further expansion. 

This week’s sell-off felt even more disturbing because the company’s chairman was absent. Larry Ellison, who usually uses earnings calls to share his vision for Oracle’s technology, did not join the call. The company did not explain why. For investors already worried about overreliance on a single leader, this silence made matters worse. 

Oracle Larry Ellison Net Worth Drop and the Billionaire Ranking Shift 

The market’s verdict has had personal consequences at the very top. Oracle Larry Ellison’s net worth drop accelerated this week, with the Oracle chairman falling behind Larry Page, Sergey Brin, and Jeff Bezos on the Bloomberg Billionaires Index. These are not permanent rankings billionaire wealth shuffles with stock prices daily—but the optics matter. When a founder’s personal fortune declines as the market questions his company’s most important strategic decision, it sharpens the narrative between leadership conviction and financial discipline. 

Analyst Divide: Is This a Buying Opportunity or a Structural Break? 

Wall Street is now divided. Evercore ISI is optimistic, saying Oracle’s infrastructure spending will lead to long-term revenue from contracts that current cash flow numbers don’t yet reflect. Their argument is based on Oracle’s growing backlog of AI cloud contracts, which reportedly total over $130 billion in future obligations. This suggests revenue is on the way, just not recognized yet. 

The opposing view is less charitable. Several analysts claim that the Oracle ORCL stock crashes, 19 percent worst week since 2001 dot-com bust AI debt explained, investors’ narrative conveys something real: a company that has permanently altered its corporate risk profile in pursuit of a market role it might not be able to keep against better-capitalized rivals. The Oracle’s $130 billion debt, negative $24 billion free cash flow, and AI data center spending crisis, June 2026, are not a quarterly blip. It shows a multi-year capital commitment that will squeeze profits, limit stock buybacks, and reduce financial flexibility, regardless of how AI demand changes. 

Looking back, the last time Oracle had a weekly drop this big was during the 2001 dotcom crash. After that, the stock lost another 47% to 53% over the next 18 months before stabilizing. This is not a prediction for today. Oracle’s 2026 business is very different from the speculative bets of the dotcom era. The company now has real revenue, solid contracts, and strong pricing power in its core database business. Still, history shows that big market shocks usually take time to settle. 

What Comes Next 

The central question for Oracle shareholders is not whether AI infrastructure spending was the right strategic call in the abstract—it almost certainly was. The question is whether Oracle’s balance sheet can sustain the pace of that spending long enough to realize the return. At Oracle’s $56 billion capex 2026 run rates, with Oracle’s negative free cash flow at negative $24 billion, and with $40 billion in additional financing planned, the margin of error is thin. 

Investors will pay close attention to Oracle’s next earnings call—not just for revenue forecasts, but also to see if Ellison appears and what he says about spending. If Oracle turns its backlog into revenue faster than expected, the pessimists will be proven wrong, and the stock could rebound quickly. But if revenue takes longer to show up or AI demand is weaker than projected, Oracle’s AI debt crisis will get worse, and $130 billion in debt will seem more like a burden than a smart bet. 

There are no guaranteed winners in the AI infrastructure race. But the financial impact is clear, and Oracle’s investors are now feeling the effects.

Source: Oracle News 

Seoul, South Korea.  

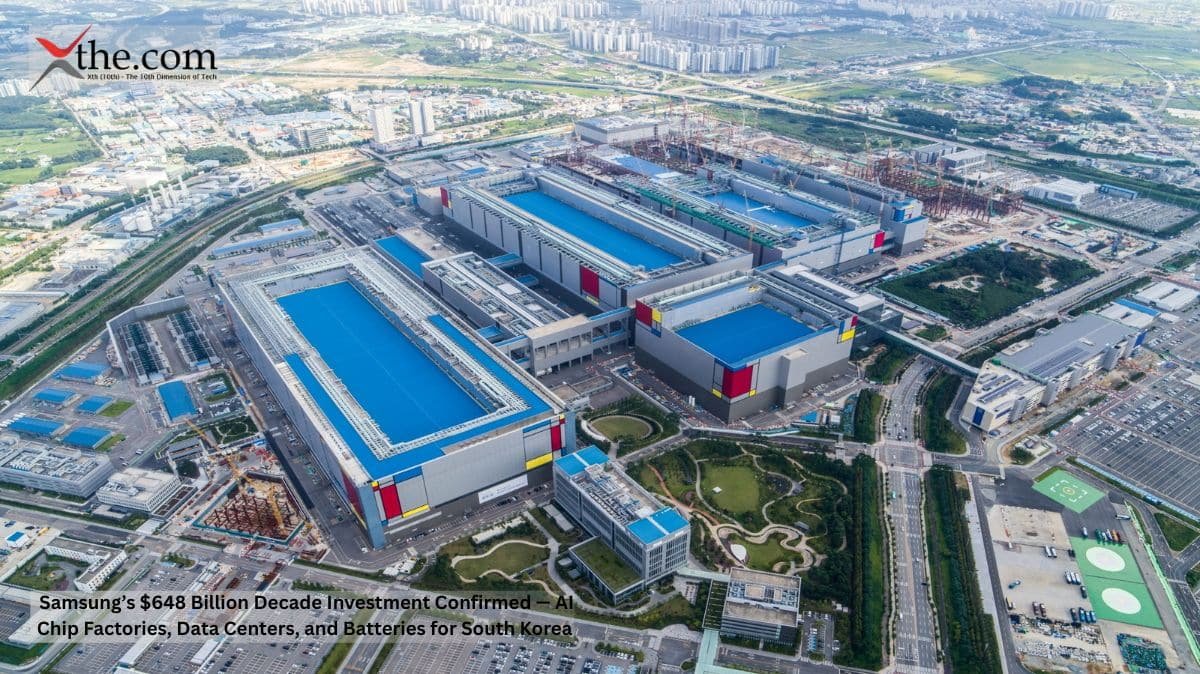
The figure is staggering: 1,000 trillion won. That equals $648 billion over ten years, all from one company trying to rebuild the country’s industrial core. On Monday morning at the presidential office in Seoul, Samsung Electronics officially announced what economists are calling the largest corporate infrastructure commitment ever. The reasons for this urgency are clear. 

SK Hynix, Samsung’s main domestic competitor, now has a market value of about $1.35 trillion, surpassing Samsung Electronics earlier this year. This shift, in which a memory chip supplier overtook the world’s largest consumer electronics company, pushed Samsung to turn its plans into firm commitments. 

The Architecture of the Samsung $648 Billion Investment 

Samsung’s 1,000 trillion won plan is not a one-time payment. Instead, the company will invest over ten years in four main areas: advanced semiconductor manufacturing, AI data centers, battery cell production, and next-generation displays. Out of the total, up to 300 trillion won, or about $194 billion, is set aside for new chip factories in southwestern South Korea. 

The Samsung semiconductor factory 2026 timeline anchors the earliest phase of construction, with initial groundbreaking expected before the end of this calendar year. What makes this announcement distinct from prior investment pledges is the geographic specificity. Samsung is not expanding around its existing Hwaseong or Pyeongtaek campuses near Seoul. It is deliberately pushing west and south, into provinces that have historically sat outside the semiconductor corridor. 

The logic is physical, not political. Land capable of supporting a leading-edge fabrication plant — which requires millions of gallons of ultrapure water daily, substations capable of delivering hundreds of megawatts of uninterrupted power, and seismically stable ground — no longer exists at a viable scale around the capital. Seoul’s metropolitan sprawl has consumed it. The Samsung AI data center South Korea faces identical constraints: the power grid serving greater Seoul is already operating near capacity, and hyperscale AI inference requires dedicated electrical infrastructure that simply cannot be retrofitted into a congested urban periphery. 

Samsung SK Hynix President Lee Jae Myung: The Political Dimension 

Monday’s announcement was not made in the boardroom. Instead, it took place at the presidential office, with Samsung SK Hynix President Lee Jae Myung and executives from both companies present. This setting was meant to show that Seoul views semiconductor self-sufficiency as a national security issue, not just an industrial policy issue. 

The meeting made official what had been months of talks between the government and the major business groups. President Lee Jae Myung, who became president earlier this year after a turbulent period, has made semiconductors central to his economic plans. His strategy to make South Korea AI chip hub by 2026 depends on Samsung completing this project on time and with the right technology. 

The government’s role is also practical. Faster permits, power grid upgrades, and water infrastructure for the Samsung Southwest Fab need central government support. Without faster approvals, starting construction in 2026 could be delayed until 2028, giving competitors such as Taiwan’s TSMC and SK Hynix more time to expand. 

The Samsung 648 Billion Dollar 10 Year Investment Plan South Korea AI Chip Factory Data Center Confirmed 2026 — What It Actually Builds 

The investment goes beyond just building chip factories. Samsung’s AI data center south Korea plans include creating secure facilities to handle Korean-language models, government data, and financial tasks without relying on foreign cloud services. Samsung has been working toward this for years, and the new funding will speed up the process. 

The battery manufacturing expansion is aimed at the electric vehicle market, where South Korean companies have lost ground to Chinese rivals with lower prices. Samsung SDI, the battery division, will get significant funding to increase production of advanced solid-state cells. The plan also includes making more foldable and rollable OLED displays, showing Samsung’s belief that unique designs will boost profits in the coming years. 

The new Samsung semiconductor factory 2026 will make chips smaller than 2 nanometers, seeking to match the technology TSMC leads today. The main question for investors is whether Samsung can catch up within the time frame of this investment. 

The Skeptic’s Case: Talent Doesn’t Move as Easily as Capital 

Money can move easily, but engineers cannot. The southwestern areas where Samsung Southwest Fab plans to build do not have many experienced semiconductor engineers, EUV lithography experts, or the network of suppliers and technicians needed to run a top-level factory. 

Analysts from several Seoul research firms have pointed out this issue since Monday’s announcement. Building factories in Chungcheong or Jeolla provinces is possible with sufficient capital and swift permits. But finding the thousands of skilled engineers needed is a separate challenge that money alone cannot fix. 

Samsung’s plan seems to include building alliances with universities and offering housing incentives near the new factory sites. The goal is to attract and develop talent at the same level as in Seoul, even though these regions have never had it before. It’s a bold social project atop a major industrial effort. 

Samsung SK Hynix South Korea Semiconductor Decentralization President Lee Jae Myung Meeting June 2026 — The Stakes 

The June 2026 meeting with Samsung, SK Hynix, and President Lee Jae Myung was more than a press event. It marked the end of a long debate among South Korean leaders about whether to keep semiconductor factories in the capital, which is efficient but risky, or to spread them out and make the industry more resilient. 

Now, the decision is official, with a ten-year investment plan in place. Whether Samsung’s $648 billion investment achieves its goals depends on how well the company can manage a project of this size and complexity, something South Korea has never tried before. The ambition is clear, but the real test will be turning these plans into working factories, data centers, and production lines on schedule, while keeping up with strong competitors.

Source: Samsung Plans a Massive $648 Billion Gamble to Reshape its AI Future 

Beijing, China 

$4.40 per million output tokens compared to $30. That is not a small difference. This is the gap between Zhipu GLM 5.2, the new 753-billion-parameter open-weight model from Beijing-based Z.ai, and OpenAI’s GPT-5.5. GLM 5.2 outperforms GPT-5.5 on several long-horizon coding benchmarks. For years, Silicon Valley has claimed that top AI performance comes with high prices. China open source AI model releases keep proving otherwise. 

GLM 5.2 vs GPT-5.5: What the Benchmarks Actually Show 

Zhipu GLM 5.2, released on June 13, 2026, is the third major model in Z.ai’s GLM-5 family. It is designed for long-horizon, agentic programming tasks. The model uses a Mixture-of-Experts architecture with 744 billion total parameters and about 40 billion active per token. This approach keeps inference costs much lower than a dense model of equivalent size, while still delivering strong performance. 

The results are clear. On SWE-bench Pro, GLM 5.2 scores 62.1 while GPT-5.5 scores 58.6. On FrontierSWE, GLM 5.2 gets 74.4 compared to GPT-5.5’s 72.6. For PostTrainBench, GLM 5.2 achieves 34.3% versus GPT-5.5’s 25.0%, and on SWE-Marathon, it reaches 13.0% against GPT-5.5’s 12.0%. The advantage holds up during long engineering tasks. GLM 5.2 ranked first on Design Arena, second on Code Arena Frontend, and led the open-weight category of the Artificial Intelligence Index v4.1. 

GLM 5.2 vs Claude Opus is more challenging. Claude Opus 4.8 still leads on most coding benchmarks, with scores like 69.2 versus 62.1 on SWE-bench Pro and 71.9 versus 63.7 on ProgramBench. It also has better agentic reliability. GLM 5.2 offers strong value: its performance is close, but its cost is much lower. On Humanity’s Last Exam with tools, GLM 5.2 scored 54.7, beating GPT-5.5 at 52.2 and coming close to Claude Opus 4.8 at 57.9. 

There are two important caveats. These results come from the vendor’s own tests, and agentic benchmarks can be sensitive to their setup. Since the weights are open under the MIT license, anyone can rerun the tests themselves. Early third-party tests have generally confirmed the coding results, which is more important than the vendor’s own claims. 

Chinese AI Model Free MIT License: The Licensing Story Is The Bigger Story 

The benchmark results are important, but the license may matter even more. 

Z.ai released the model’s weights under an MIT open-source license, making it a “Pure Open” system. The company’s technical documentation states that this license guarantees “no regional limits” and allows “technical access without borders.” For enterprise technology leaders, this is significant. A Chinese AI model free MIT license means you can download, fine-tune, modify, and deploy it commercially without needing permission, paying usage fees, or facing geographic restrictions in the terms of service. 

The practical impact is clear. Z.ai’s GLM 5.2 lets organizations host advanced AI locally, avoiding geographic and commercial restrictions. A Fortune 500 company handling regulated workloads like healthcare data, legal documents, or financial models can self-host Zhipu GLM 5.2 on its own infrastructure. This means paying only for compute and removing the data-residency risks of sending sensitive content through third-party APIs. 

This economic advantage comes from the model’s architecture. GLM 5.2 uses an optimization called “IndexShare,” which reuses the same indexer across every four sparse attention layers. At the maximum 1-million-token context length, this reduces per-token compute FLOPs by a factor of 2.9. Running a 753-billion-parameter model is still demanding, but IndexShare makes it much less costly than similar dense models. 

Zhipu AI Benchmark Results 2026: The Timing Was Not Accidental 

The release happened in a competitive context. GLM 5.2 launched about 48 hours after new US export rules forced Anthropic to disable its Fable 5 and Mythos 5 models for foreign nationals on June 12, 2026. Foreign developers, companies in allied countries, and non-US government agencies that had been using Anthropic’s most capable models woke up to find those tools unavailable indefinitely, with no clear resolution in sight. Two days later, an open-weight China open-source AI model under MIT licensing and with top coding performance appeared on Hugging Face, with no geographic restrictions. The timing was strategic and effective. 

GLM 5.2 became the first Chinese AI model to rank in the top three worldwide on a major AI benchmark. Well-known US technologists have called it reliable enough for daily professional coding. On OpenRouter, the model was adopted by more than 13 providers within days. Now, GLM 5.2 is available from 23 providers, with the platform automatically choosing the best price and speed. Its rollout was as fast as, or even faster than, the DeepSeek V4 release that shook markets in early 2025. 

Open-Source AI Enterprise Alternative: What The Price Comparison Forces Executives To Consider 

GLM 5.2 API access costs $1.40 per million input tokens and $4.40 per million output tokens. This is about one-sixth the combined cost of GPT-5.5 ($5/$30) and much less than Claude Opus 4.8 ($5/$25). While some online claim that frontier labs operate at “probably at 90%+ margins,” the real point is that the price difference is significant, regardless of the actual margins. 

Consider a practical example. An enterprise running a code review and documentation pipeline that produces 500 million output tokens per month pays $15,000 per month to OpenAI for GPT-5.5. The same workload on the Z.ai API costs $2,200. If self-hosted, the cost is just compute and electricity. With such a price gap, the main question shifts from “is this Chinese model good enough?” to “what are the documented risks of using it?” 

That risk is real and should not be ignored. Open-weight availability lets you run GLM 5.2 on your own infrastructure, helping protect data privacy in regulated industries by keeping all data in-house. Self-hosting removes concerns about exposing data through APIs. However, it does not address questions about the model’s training data, its behavior under hostile prompts, or the geopolitical risks of using Chinese-developed AI in critical business systems. Fortune 500 business continuity teams are now weighing these factors with real deadlines, since American alternatives have just become unavailable for their international branches. 

“China Zhipu GLM 5.2 Open-Source AI Model Performance vs GPT-5.5 Claude Opus Price Comparison 2026” — The Wider Shift 

The story of “GLM 5.2 MIT license free download enterprise AI alternative to OpenAI Anthropic June 2026” is not simple. GLM 5.2 is not better than Claude Opus 4.8 in every area, and it is not a full replacement for GPT-5.5 in multimodal or general-reasoning tasks. However, at $4.40 per million output tokens, with an MIT license and a 1-million-token context window, it is a strong open source AI enterprise alternative that enterprises can use today without contracts, geographic limits, or reliance on US export rules. 

The clear difference between open-weight innovators and proprietary Western labs has caught the attention of developers, procurement officers, CIOs, and government IT buyers. Many just saw two of the world’s top AI models vanish from their pipelines in 48 hours. Z.ai’s Zhipu AI benchmark results 2026 landed at exactly the moment that argument needed empirical weight. The strategic window that was created is already closing Anthropic’s Mythos 5 is partially restored, Fable 5 negotiations continue  but the demonstration has been made. Next time Washington restricts access to a frontier AI model, enterprises will know they have alternatives that perform nearly as well as the restricted models. 

That is the real DeepSeek moment—not just the benchmark, but the backup plan.

Source: China’s Zhipu is closing in on top U.S. AI models with Anthropic and OpenAI held back